Specialty Amines Pricing Outruns Volume While Eastman Flags Record Earnings
Eastman's October 29 Results, Huntsman's Performance Amines Volume Gain and Balaji Amines' November 3 Filing Show Specialty Amine Producers Passing Middle East-Driven Feedstock Costs Into Price Before Volume Recovers
On October 29, 2026, Eastman Chemical Company reported third-quarter results in which its Additives & Functional Products segment, the home of its functional amines and amine-derivative care additives lines, grew sales revenue 9% to USD 784 million from USD 716 million a year earlier. Selling prices rose 10%, driven by cost-pass-through contracts adjusting to higher raw material and distribution costs, while sales volume and mix slipped 1%. On the company's earnings call on October 30, 2026, as recorded in the transcript published by The Motley Fool, Board Chair and Chief Executive Officer Mark Costa said the functional amines business is on track for record earnings this year, a statement that arrived in the same quarter Eastman attributed a sequential earnings decline to the escalation of the Middle East conflict.
According to Next Move Strategy Consulting's Specialty Amines Market report, the global specialty amines market was valued at USD 13.20 billion in 2025 and is projected to reach USD 23.40 billion by 2035, growing at a CAGR of 5.9% from 2026 to 2035. NextMSC primary research and analysis identifies Asia-Pacific as the largest regional market at USD 4.88 billion in 2025, and points to agrochemical formulation, personal care and cosmetics, and water treatment as the application areas carrying demand, with ether amines the fastest-growing type at a 9.2% CAGR through 2035.
For More Information: Download FREE Sample on Specialty Amines Market Report
The Financial Logic: Cost Pass-Through Turns Feedstock Inflation Into Earnings
The mechanism behind Eastman's result is contractual rather than cyclical. In its October 29 release, the company stated that higher selling prices in Additives & Functional Products reflected cost-pass-through contracts adjusting to higher raw material and distribution costs, and that segment earnings before interest and taxes rose on improvements in both price-cost and asset utilization. Adjusted segment EBIT reached USD 154 million at a 19.6% margin, against USD 128 million at 17.9% in the third quarter of the previous year. Across the whole company, Eastman said it remains on track to implement approximately USD 500 million of selling price increases in 2026 compared with its expectations before the Middle East conflict began.
Volume tells a more cautious story. Eastman prepared remarks of October 29 show Additives & Functional Products revenue falling 3% sequentially from the second quarter, with sales volume and mix down 7% and price up 4%, a decline the company attributed to seasonality across key end markets, primarily agriculture. For the fourth quarter, the company guided to seasonal declines and a segment EBIT lower than the third quarter. The pattern, in which price carries revenue while tonnage waits for the seasonal and macroeconomic backdrop to improve, appears across the producers that reported between July and November.
Huntsman Corporation's second-quarter release of July 30, 2026 shows the same sequence from the volume side. Performance Products revenue rose 5% to USD 283 million from USD 270 million, with a 3% volume gain that the company attributed primarily to favorable demand in its performance amines business, while higher raw material costs lifted average selling prices. Segment adjusted EBITDA increased 16% to USD 37 million. Peter R. Huntsman, Chairman, President and Chief Executive Officer, tied the quarter to higher volumes and the use of pricing actions to offset the raw material increase.
“pricing actions that offset a significant increase in raw material costs”
- Peter R. Huntsman, Chairman, President and Chief Executive Officer, Huntsman Corporation, Huntsman Announces Second Quarter 2026 Earnings, July 30, 2026.
Amine-Linked Segment Results Reported by Producers, Mid-2026
|
Producer and segment |
Reporting period |
Revenue (current vs prior year) |
Revenue change |
Company-stated driver |
|
Eastman, Additives & Functional Products |
Q3 2026 (to September 30) |
USD 784 million vs USD 716 million |
+9% |
Selling prices +10% on cost-pass-through contracts; volume and mix -1% |
|
Huntsman, Performance Products |
Q2 2026 (to June 30) |
USD 283 million vs USD 270 million |
+5% |
Volume +3% on performance amines demand; prices higher on raw material costs |
|
Balaji Amines, consolidated |
Q2 FY27 (to September 30, 2026) |
INR 472 crore vs INR 348 crore |
+35.6% |
Net profit +81.1% to INR 67 crore; sales volume -6.4% to 24,491 metric tonnes |
Key Industry Developments: Capacity Moves and Corporate Realignment
Capacity additions are being placed closer to the customers that absorb amine volume. Evonik Industries inaugurated the expansion of its specialty amine production facility in Nanjing, China on April 21, 2026, following an investment the company described as double-digit-million-euro, and positioned the plant for commercial-scale manufacturing of reactive specialty amines for polyurethane and epoxy applications facing stricter emission standards. The announcement is the earliest of the dated developments in this report, but it remains the clearest recent statement of where a European major is adding amine capacity.
Corporate structure is shifting as well. On June 16, 2026, Olin Corporation and Huntsman announced a definitive all-stock merger of equals, with closing expected in the first half of 2027, according to Olin's SEC Form 425 filing of the same date. The filing states that the combined company would hold a fully integrated epoxy value chain, a point of direct relevance to amines because epoxy curing is a core outlet for specialty amine grades. Huntsman's July 30 release confirmed that its stockholder vote was scheduled for August 25, 2026.
In India, Balaji Amines reported its second-quarter results for fiscal 2027 in a regulatory filing dated November 3, 2026. Consolidated revenue rose 35.6% to INR 472 crore, consolidated EBITDA increased 58.2% to INR 106 crore at a 22% margin, and net profit climbed 81.1% to INR 67 crore, according to the Free Press Journal's report on the filing. Sales volume, however, fell 6.4% to 24,491 metric tonnes from 26,165 metric tonnes, and Managing Director D. Ram Reddy acknowledged that external factors affected volumes during the quarter. The company also began commercial production at an expanded acetonitrile facility with installed capacity of 1,440 tonnes per month and highlighted the commissioning of a 100,000-tonne-per-annum dimethyl ether plant.
Dated Capacity and Corporate Actions Among Amine Producers
|
Company |
Date |
Action |
Stated purpose |
|
Evonik Industries |
April 21, 2026 |
Inaugurated expanded specialty amine production in Nanjing, China; double-digit-million-euro investment |
Commercial-scale reactive amines for polyurethane and epoxy applications with stricter emission limits |
|
Olin Corporation and Huntsman Corporation |
June 16, 2026 |
Signed all-stock merger of equals; closing expected in the first half of 2027 |
Integrated chlorine-to-epoxy value chain with downstream formulation expertise |
|
Balaji Amines |
November 3, 2026 |
Disclosed expanded acetonitrile capacity of 1,440 tonnes per month and a commissioned 100,000-tonne-per-annum dimethyl ether plant |
Broader specialty chemicals portfolio and import substitution in India |
Segment Dynamics: Where Amine Revenue Sits Inside the Producers
The Eastman Form 10-K for 2025 breaks down how much of its Additives & Functional Products segment depends on amine chemistry. Care additives, defined in the filing as amine derivative-based building blocks for flocculants, surfactant intermediates, fumigants, fungicides and plant growth regulators, accounted for 38% of segment sales in 2025, and functional amines, covering methylamines and salts and higher amines and solvents, accounted for 19%. Coatings additives represented 27% and specialty fluids and energy 16%.
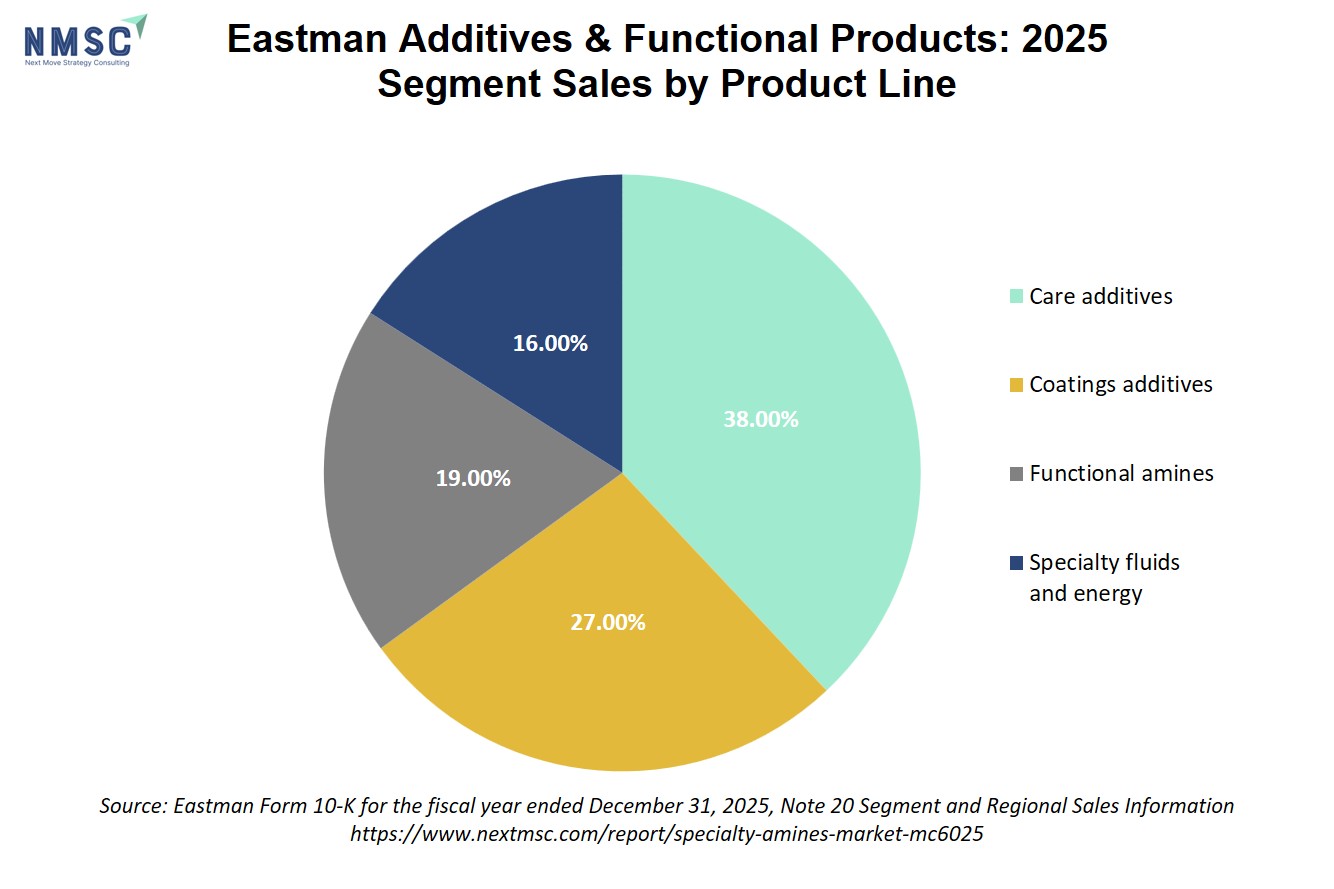
Within NextMSC primary research and analysis, ethanolamines held the largest share by type in 2025 at USD 3.83 billion, or 29% of the market, while ether amines are projected to expand fastest at a 9.2% CAGR through 2035 on epoxy curing demand from wind energy composites and advanced coatings. By application, agrochemicals led in 2025 at USD 3.17 billion, a 24% share, and personal care and cosmetics is projected to grow fastest at 8.2% CAGR as formulators specify low-odor and biodegradable amine derivatives. Those NextMSC figures describe the market as a whole; Eastman's filing shows how one integrated producer's own mix lines up with them, with amine-derivative care additives forming the largest single block.
The third-quarter comparison across Eastman's four segments isolates how unusual the price effect is in amine-heavy lines. Chemical Intermediates grew 16% as tight olefin and derivative markets followed the Middle East conflict, Additives & Functional Products grew 9% almost entirely on price, Advanced Materials grew 5%, and Fibers was unchanged, according to the release's revenue change table.

Regional Outlook: Asia-Pacific Scale, Latin America Pace
NextMSC primary research and analysis sizes Asia-Pacific at USD 4.88 billion in 2025, rising to USD 9.13 billion by 2035 at a 6.5% CAGR, supported by chemical manufacturing capacity growth in China and India. China is the largest national market at USD 2.05 billion in 2025, and India is the fastest-growing country at a 7.7% CAGR from 2026 to 2035. North America stood at USD 3.56 billion in 2025 and is projected to reach USD 5.62 billion by 2035 at a 4.6% CAGR, anchored in pharmaceutical and personal care manufacturing.
Europe, at USD 2.77 billion in 2025 and a 4.1% CAGR, is the slowest-growing region in the NextMSC analysis because REACH-linked compliance costs and energy-intensive production weigh on economics. Latin America is the fastest-growing region at an 8.8% CAGR from USD 0.93 billion in 2025, led by agrochemical consumption tied to soybean and grain cultivation, with Middle East and Africa at an 8.5% CAGR from USD 1.06 billion on oilfield corrosion inhibitors and water treatment. Eastman's company-wide third-quarter sales by customer location illustrate the divergence in current trading: United States and Canada sales rose to USD 1,094 million from USD 972 million, while Asia Pacific sales were flat at USD 535 million against USD 534 million.
Growth Drivers and Restraints: What the Mid-2026 Filings Show
Growth Driver and Restraint Evidence Matrix, Amine Producers
|
Factor |
Type |
Evidence from filings |
Source |
|
Cost-pass-through contracts convert feedstock inflation into price |
Driver |
Eastman Additives & Functional Products prices +10%; adjusted segment EBIT margin 19.6% vs 17.9% |
Eastman release, October 29, 2026 |
|
Demand for performance amines |
Driver |
Huntsman Performance Products volume +3%, attributed primarily to favorable demand in performance amines |
Huntsman release, July 30, 2026 |
|
Regional capacity placed near customers |
Driver |
Evonik Nanjing expansion; Balaji acetonitrile and dimethyl ether capacity |
Evonik, April 21, 2026; Free Press Journal, November 3, 2026 |
|
Seasonal agriculture softness |
Restraint |
Eastman segment volume and mix -7% sequentially, driven by seasonality primarily in agriculture |
Eastman prepared remarks, October 29, 2026 |
|
Inflation and interest-rate caution among customers |
Restraint |
Eastman cites customer caution as the Middle East conflict raises inflation and interest rates |
Eastman prepared remarks, October 29, 2026 |
|
Volume contraction at a regional producer |
Restraint |
Balaji Amines sales volume -6.4% to 24,491 metric tonnes |
Free Press Journal, November 3, 2026 |
NMSC Strategic Perspective: Pricing Power Is Running Ahead of Volume
NextMSC primary research and analysis reads the mid-2026 filings as evidence that specialty amine economics are being set by contract structure before demand. Eastman's amine-linked segment lifted revenue 9% on a 10% price effect, Balaji Amines grew revenue 35.6% on a 6.4% volume decline, and Huntsman's Performance Products segment is the only one of the three whose growth was led by volume. The common factor is that producers with indexed or pass-through pricing converted raw material inflation into revenue within one quarter, a protection that smaller regional producers without long-term feedstock agreements do not share.
That reading is consistent with the restraint NextMSC identifies in its report. Volatility in ethylene oxide and ammonia feedstock prices is the leading restraint, estimated by NextMSC to subtract 0.8 percentage points from the 2026 to 2035 CAGR, and the report notes that producers with integrated ethylene oxide and ammonia access sustain cost advantages that regional peers cannot replicate. The Middle East-driven cost escalation described by Eastman is therefore not only a margin event but a competitive filter, favoring integrated and contract-protected suppliers.
For the 5.9% CAGR in NextMSC's forecast, the near-term implication is a split between revenue and tonnage. Revenue growth in 2026 is being supported by price, while the volume growth that sustains the forecast depends on agricultural demand recovering from its seasonal trough and on customers regaining confidence as inflation and interest-rate concerns ease. Eastman prepared remarks state that the segment is well positioned to deliver growth in 2027 across a range of macroeconomic scenarios, and NextMSC treats ether amines, personal care derivatives and water treatment chemicals as the pathways most likely to convert that pricing strength into durable volume.
Competitive Landscape
NextMSC primary research and analysis characterizes the specialty amines market as moderately consolidated, with diversified chemical majors competing alongside cost-advantaged regional producers in India and China. The validated set of leading producers in the NextMSC report includes BASF SE, Huntsman Corporation, Dow Inc., Nouryon Chemicals Holding B.V., Eastman Chemical Company and Evonik Industries AG, among 20 profiled companies, and competition centers on feedstock integration, purity grade and technical service depth rather than price alone.
The dated events in this report map onto that structure. Eastman and Huntsman are defending margin through contract pricing while volumes recover, Evonik is adding Asia-based capacity for polyurethane and epoxy curing grades, and Balaji Amines is widening its specialty chemicals range while reporting a volume decline. Each development is traceable to a company release, a regulatory filing or a report on a filing, and none involves large-scale consolidation among the top amine producers, which NextMSC research describes as favoring selective capacity expansions and joint development over acquisitions.
Bottom Line
Specialty amine producers entered the final quarter of the year with pricing power but without a clean volume recovery. Eastman's Additives & Functional Products segment grew third-quarter revenue 9% on a 10% price effect, with functional amines on track for record earnings, while Huntsman's Performance Products segment added 3% volume on performance amines demand and Balaji Amines grew revenue 35.6% despite a 6.4% volume decline. The Middle East conflict is raising raw material and distribution costs, and contract-protected, integrated producers are passing those costs through faster than regional peers. NextMSC values the global market at USD 13.20 billion in 2025 and projects USD 23.40 billion by 2035 at a 5.9% CAGR, a path that now depends on agricultural, personal care and water treatment volumes recovering from seasonal and macroeconomic softness. Eastman guides to stable price-cost in the segment for the fourth quarter, and the open question for producers is whether capacity added in Nanjing and India meets recovering demand or outruns it.
About Next Move Strategy Consulting
Next Move Strategy Consulting is a premier market research and management consulting firm that has been committed to provide strategically analysed well documented latest research reports to its clients. The research industry is flooded with many firms to choose from, what makes NMSC different from the rest is its top-quality research and the obsession of turning data into knowledge by dissecting every bit of it and providing fact-based research recommendation that is supported by information collected from over 500 million websites, paid databases, industry journals and one on one consultations with industry experts across a diverse range of industry sectors. The high-quality customized research reports with actionable insights and excellent end-to-end customer service help our clients to take critical business decisions that enables them to move beyond time and have competitive edge in the industry.
We have been servicing over 1000 customers globally that includes 90% of the Fortune 500 companies over a decade. Our analysts are constantly tracking various high growth markets and identifying hidden opportunities in each sector or the industry. We provide one of the industry’s best quality syndicate as well as custom research reports across 10 different industry verticals. We are committed to deliver high quality research solutions in accordance to your business needs. Our industry standard delivery solutions that ranges from the pre consultation to after-sales services, provide an excellent client experience and ensure right strategic decision making for businesses.
For more information, please contact:
Next Move Strategy Consulting
5th Floor 867 Boylston St, STE 500,
Boston, MA 02116, U.S.
E-Mail: [email protected]
Direct: +1-217-650-7991
Website: www.nextmsc.com
About the Author
 Sanyukta Deb
— Sanyukta Deb is Digital Marketing Team Lead at Next Move Strategy Consulting, where she has led content strategy and technical SEO for the firm's B2B market research publications for over 2 years. Her editorial process translates NextMSC's primary and secondary research — spanning technology, industrial, and consumer sectors — into commercial narratives, backed by search-intent, keyword, and competitive analysis. She brings 5 years of overall experience in digital marketing and content strategy.
About the Reviewer
 Debashree Dey
— Debashree Dey is Assistant Manager at Next Move Strategy Consulting, where she supports cross-vertical market content and communications across diverse industries for 6 years. Her professional background includes senior content writing, communications, and published manuscript authorship, with experience developing audience-focused business narratives and maintaining clear, consistent messaging. Her role supports research-led content development and editorial quality across NextMSC publications.














Add Comment