Automotive On-Board Diagnostics (OBD) Market Analysis and Forecast (2026–2035)

Automotive On-Board Diagnostics (OBD) Market size was USD 68.14 Billion in 2025 and is projected to reach USD 181.77 Billion by 2035, expanding at 9.92% CAGR over 2026–2035, driven by emission regulation, fleet telematics and software content, with Asia-Pacific leading.

Download Free Sample PDF
Base Year (2025)
$68.14 Billion
Forecast (2035)
$181.77 Billion
CAGR (2026-2035)
9.9%
Top Region
Asia-Pacific

What Is the Automotive On-Board Diagnostics (OBD) Market Size?

The global Automotive On-Board Diagnostics (OBD) Market was valued at USD 68.14 Billion in 2025 and is estimated at USD 77.62 Billion in 2026, forecast to reach USD 181.77 Billion by 2035 at a CAGR of 9.92% between 2026 and 2035. Asia-Pacific leads with approximately 36% share, while Hardware dominates offerings at approximately 56%.

Our analysis shows the following segment and geographic leaders across the forecast window.

Automotive On-Board Diagnostics (OBD) Market Analysis and Forecast (2026–2035) Revenue Forecast

Values in USD Billion

2025 $68.14 Billion
2025
2026 $77.62 Billion
2026
2027 $85.32 Billion
2027
2028 $93.78 Billion
2028
2029 $103.09 Billion
2029
2030 $113.31 Billion
2030
2031 $124.55 Billion
2031
2032 $136.91 Billion
2032
2033 $150.49 Billion
2033
2034 $165.42 Billion
2034
2035 $181.77 Billion
2035

Key Takeaways

By Offering: Hardware held the largest share, expanding from USD 38.16 Billion in 2025 to USD 83.61 Billion by 2035; Software is the fastest growing at 12.68% CAGR from 2026–2035.

By Vehicle Type: Passenger cars held the largest share, expanding from USD 46.34 Billion in 2025 to USD 110.88 Billion by 2035; Medium and heavy commercial vehicles is the fastest growing at 12.67% CAGR from 2026–2035.

By Application: Emissions compliance and inspection held the largest share, expanding from USD 30.66 Billion in 2025 to USD 65.44 Billion by 2035; Fleet telematics and insurance is the fastest-growing application segment, with a projected CAGR of 14.78% from 2026 to 2035. Retain this figure only after verifying the underlying 2026 and 2035 segment revenues.

Dominant Region: Asia-Pacific held the largest share, expanding from USD 24.53 Billion in 2025 to USD 73.62 Billion by 2035.

Fastest-Growing Region: Middle East & Africa is the fastest growing at 11.57% CAGR from 2026–2035.

Dominant Country: U.S. led with USD 14.72 Billion in 2025, projected to reach USD 34.96 Billion by 2035.

Fastest-Growing Country: India is the fastest growing at 15.41% CAGR from 2026–2035.

[Source: www.nextmsc.com](

We observed that regulation, not discretionary demand, anchors this market. Every light vehicle sold under U.S. federal rules since model year 2017 must carry a certified-on board monitor, and Euro 7 extends comparable duties across European fleets. As that installed base ages, technicians, inspectors and fleet operators read ever more trouble codes, which keeps scan tool, software and service revenue rising together across every major region.

The Automotive On-Board Diagnostics (OBD) Market presents an absolute investment opportunity of approximately USD 104.15 Billion between 2026 and 2035, supported by growing demand for diagnostic software and fleet analytics.

According to NMSC analysis, Software is the fastest growing offering at 12.68% CAGR because every new diagnostic standard, from OBDonUDS to remote monitoring, converts a one-time hardware sale into recurring license and data revenue.

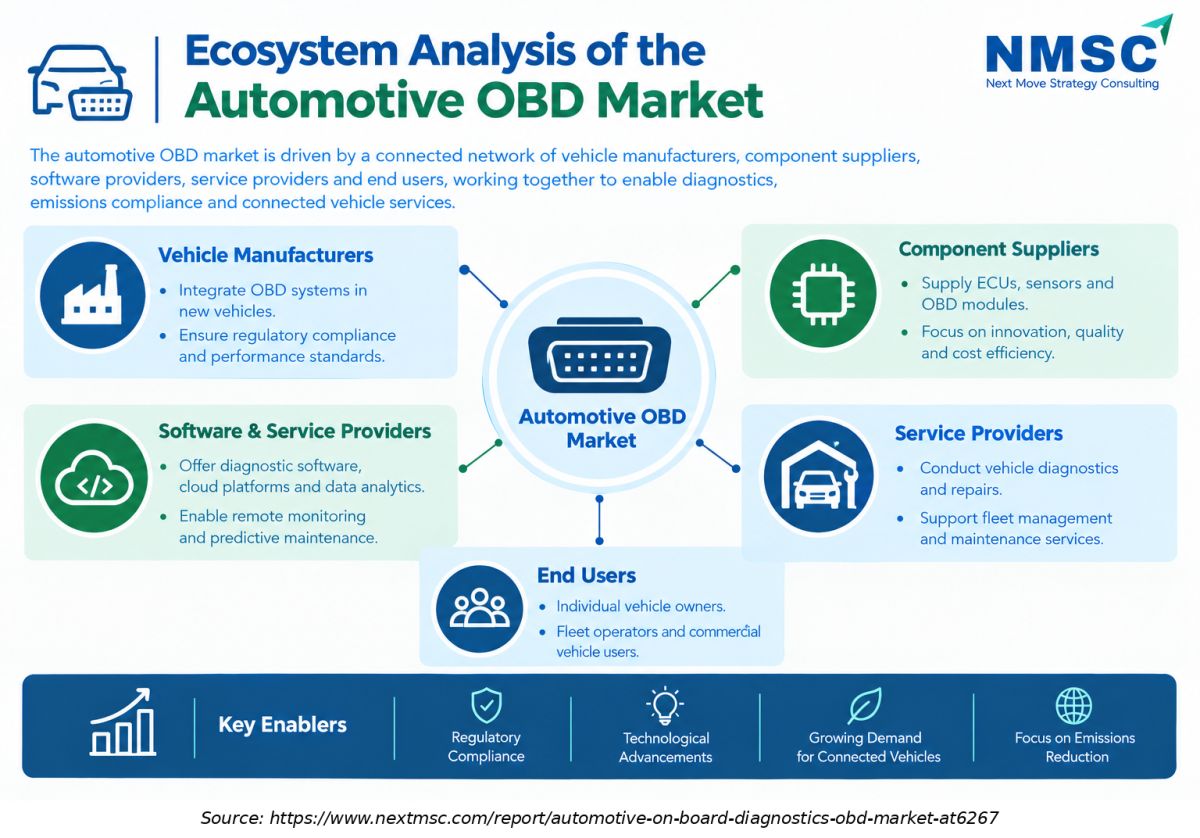
Ecosystem Analysis of the Automotive On-Board Diagnostics (OBD) Market

The infographic outlines the Ecosystem Analysis of the Automotive On-Board Diagnostics (OBD) Market, highlighting key stakeholders such as vehicle manufacturers, component suppliers, software and service providers, repair and maintenance service providers, and end users. It emphasizes how regulatory compliance, technological advancements, connected vehicle solutions, and emissions reduction support diagnostic innovation, vehicle performance, and long-term market growth

What Does the Automotive On-Board Diagnostics (OBD) Market Encompass?

The Automotive On-Board Diagnostics (OBD) Market covers the hardware, software and services used to monitor, read and act on the diagnostic data that vehicles generate through their on-board computers. Hardware includes scan tools, connectors, dongles and telematics gateways, software spans diagnostic applications and analytics, and services cover calibration, inspection and remote support. NMSC treats this stack as a distinct slice of the wider automotive electronics value chain, because revenue follows the diagnostic function and not the component.
The structural shift runs from fixed workshop testers toward connected, cloud linked diagnostics. Emission rules in the United States, Europe, China and India require vehicles to detect faults and store codes, and the Euro 7 implementing rules require monitoring data to remain readable through the standard port with a generic tool. Each electronic control unit added to a vehicle raises the number of diagnostic trouble codes that tools must decode, which expands demand for software and training.

Market Drivers & Dynamics

Interactive Dataset
Tightening emission and OBD regulation (Euro 7, U.S. EPA, China VI, Bharat Stage VI) driver +2.10% Global 2026–2035
Ageing vehicle parc increasing fault frequency driver +1.45% Europe, North America 2026–2032
Connected fleet telematics and OBD dongles driver +1.60% North America, Asia-Pacific 2026–2035
Rising ECU and software content per vehicle driver +1.25% Global 2026–2035
Battery electric vehicle share reducing combustion diagnostics restraint −1.10% Europe, China 2028–2035
Cybersecurity and privacy limits on OBD port access restraint −0.75% Europe, North America 2026–2030
Tool cost and technician skills gap restraint −0.60% Emerging markets 2026–2031
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Automotive On-Board Diagnostics (OBD) Market?

Regulation remains the primary driver. Under 40 CFR § 86.1806-17, covered model-year 2017 and later vehicles in the United States must have OBD systems that generally detect emission-control malfunctions, store corresponding diagnostic trouble codes, and alert operators. The regulation incorporates California's 2013 OBD-II requirements, subject to specified federal clarifications and exceptions. Commission Implementing Regulation (EU) 2025/1707, adopted on 25 July 2025 and published on 5 September 2025, requires specified on-board monitoring data to be accessible through the standard OBD port using a generic scan tool for covered vehicle categories. These rules sustain demand for the Automotive On-Board Diagnostics (OBD) Market in both new vehicle supply and inspection, and our model attributes +2.10% to CAGR.

How Is the Aging Vehicle Fleet Driving Market Growth?

Older vehicles throw more fault codes and spend more time in independent workshops, which are the main buyers of multi brand scan tools. According to ACEA's vehicle-fleet analysis based on 2022 data, the average age of EU cars was 12.3 years, light commercial vehicles were 12.5 years, and trucks were 13.9 years old. Operators of such assets, including those running fleet management systems, rely on diagnostics to defer replacement and control downtime. We found that this parc effect is strongest in Europe and North America through 2032.

Growth Inhibitors

What Is Restraining the Automotive On-Board Diagnostics (OBD) Market?

Two forces restrain growth. Battery-electric vehicles do not require conventional combustion-engine or tailpipe after-treatment diagnostics, reducing demand for those specific diagnostic functions. However, they create additional diagnostic requirements for battery systems, charging components, power electronics, and thermal management.Separately, manufacturers are restricting open port access to protect against intrusion, which complicates aftermarket tool and dongle use. Our assessment indicates a combined drag of about 1.85% on the CAGR of the Automotive On-Board Diagnostics (OBD) Market, partly offset by new software revenue.

What Are the Growth Opportunities?

How Can Vehicle Data Services Create New Revenue?

Diagnostic streams are becoming a monetizable asset. Insurers price risk from fault and driving behaviour, utilities and charging networks use battery health records, and OEMs sell subscription services built on vehicle data. Suppliers that package trouble code histories into licensed feeds, within consent and privacy rules, capture recurring income. The opportunity favours the software offering and the fleet and insurance application, where automotive data monetization models already show paying customers.

Where Does Remote Diagnostics Open Opportunities for Warranty and Service?

Remote monitoring lets service teams spot a failing component before the owner notices. Dealers and independent chains can schedule repairs, order parts in advance and reduce comebacks, which improves margins. Providers of extended warranty contracts gain a clearer view of claim risk and can price coverage more accurately. We found that services revenue, at a projected 11.22% CAGR, benefits most from this shift in service logic.

What Role Do Digital Twins and Emerging Markets Play?

Emerging economies are tightening emission rules and expanding periodic inspection, which creates first time demand for certified readers and training. Middle East and Africa are the fastest growing region at 11.57% CAGR. In developed markets, manufacturers are building digital twin models of vehicles that combine live diagnostic data with simulation to test software updates and predict wear. Vendors serving both groups can scale software across geographies with limited incremental cost.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Hardware 2025: $38.16 Billion | 2035: $83.61 Billion
Hardware
Software 2025: $19.08 Billion | 2035: $65.44 Billion
Software
Services 2025: $10.90 Billion | 2035: $32.72 Billion
Services
Hardware $38.16 Billion $83.61 Billion 7.75%
Software $19.08 Billion $65.44 Billion 12.68%
Services $10.90 Billion $32.72 Billion 11.22%

Which Offering Leads the Automotive On-Board Diagnostics (OBD) Market?

Hardware held about 56% of 2025 revenue at USD 38.16 Billion, supported by scan tools, connectors and telematics gateways sold into workshops, inspection lanes and fleets. Software is the fastest growing offering at 12.68% CAGR, rising to USD 65.44 Billion by 2035 as diagnostic applications, cloud analytics and edge AI features shift value from devices to licenses. Services follow at 11.22%, driven by calibration and remote support.

2025 (USD Billion)
2035 (USD Billion)
Passenger ca
Light commer
Medium and h
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Passenger cars $10.0 USD Billion $40.0 USD Billion 26.0%
Light commercial vehicles $17.1 USD Billion $51.1 USD Billion 16.0%
Medium and heavy commercial vehicles $24.2 USD Billion $62.2 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Vehicle Type.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Emissions co
Repair and m
Fleet telema
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Emissions compliance and inspection $10.0 USD Billion $40.0 USD Billion 18.0%
Repair and maintenance diagnostics $17.1 USD Billion $51.1 USD Billion 16.0%
Fleet telematics and insurance $24.2 USD Billion $62.2 USD Billion 22.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data

Growth Opportunities

NMSC identifies three opportunities that can lift the Automotive On-Board Diagnostics (OBD) Market above its base trajectory.

How Can Vehicle Data Services Create New Revenue?

Diagnostic streams are becoming a monetizable asset. Insurers price risk from fault and driving behaviour, utilities and charging networks use battery health records, and OEMs sell subscription services built on vehicle data. Suppliers that package trouble code histories into licensed feeds, within consent and privacy rules, capture recurring income. The opportunity favours the software offering and the fleet and insurance application, where automotive data monetization models already show paying customers.

Where Does Remote Diagnostics Open Opportunities for Warranty and Service?

Remote monitoring lets service teams spot a failing component before the owner notices. Dealers and independent chains can schedule repairs, order parts in advance and reduce comebacks, which improves margins. Providers of extended warranty contracts gain a clearer view of claim risk and can price coverage more accurately. We found that services revenue, at a projected 11.22% CAGR, benefits most from this shift in service logic.

What Role Do Digital Twins and Emerging Markets Play?

Emerging economies are tightening emission rules and expanding periodic inspection, which creates first time demand for certified readers and training. Middle East and Africa are the fastest growing region at 11.57% CAGR. In developed markets, manufacturers are building digital twin models of vehicles that combine live diagnostic data with simulation to test software updates and predict wear. Vendors serving both groups can scale software across geographies with limited incremental cost.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

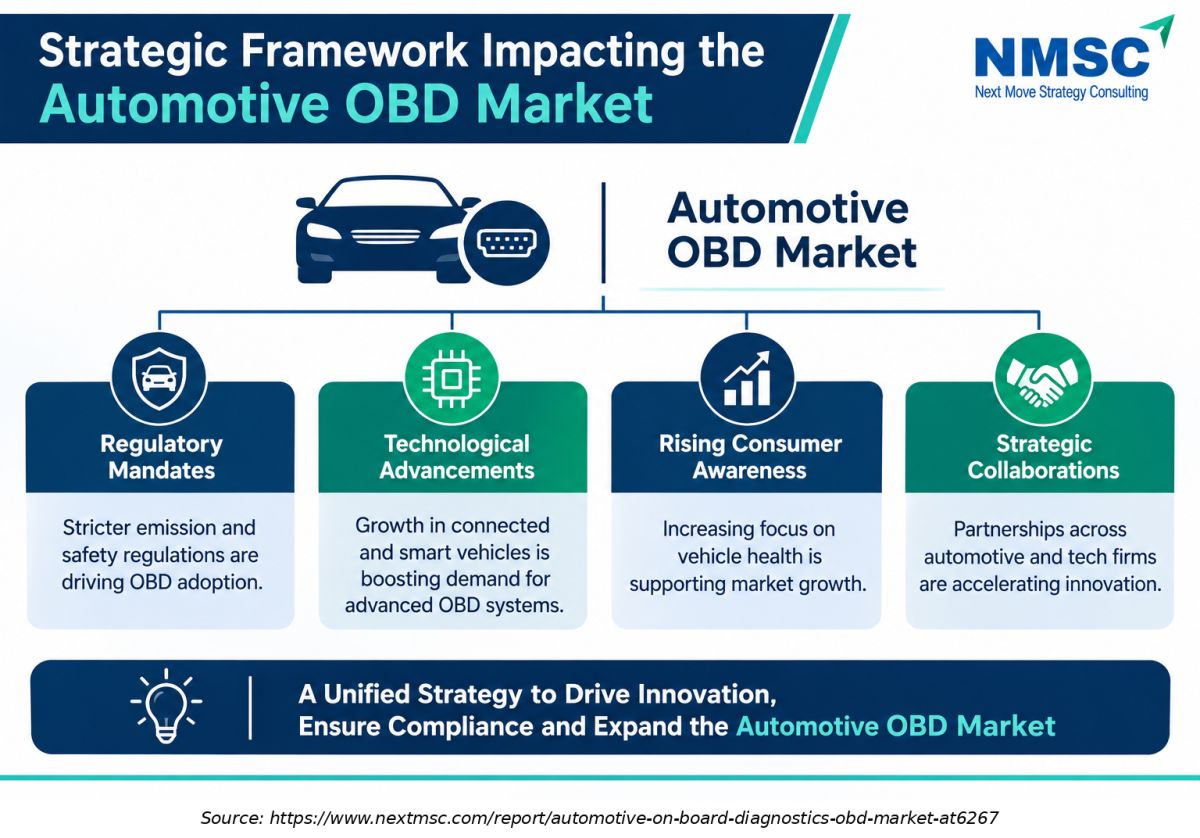
Strategic Framework Impacting the Automotive On-Board Diagnostics (OBD) Market

Strategic Framework Impacting the Automotive On-Board Diagnostics (OBD) Market
The infographic highlights the Strategic Framework Impacting the Automotive On-Board Diagnostics (OBD) Market, focusing on technological innovation, regulatory compliance, connected vehicle solutions, and strategic partnerships. It illustrates how advanced diagnostic tools, remote vehicle monitoring, predictive maintenance, emissions compliance, and growing demand for vehicle connectivity support product development, market expansion, and long-term growth

Competitive Landscape

Our assessment indicates that competition is shaped by regulatory depth, tool coverage and data access.

How Do Companies Compete in the Automotive On-Board Diagnostics (OBD) Market?

Competition runs along three lines: vehicle coverage, data access and channel reach. Workshop tool specialists such as Snap-on, Autel, Launch Tech, TEXA and Bosch sell multi brand coverage through distributors and direct sales forces, while telematics providers like Geotab compete on analytics and fleet integrations. Pricing differs by channel, with subscription updates replacing one off hardware sales in the Automotive On-Board Diagnostics (OBD) Market and local brands pressing prices in Asia-Pacific.

Which Competitor Archetypes Dominate the Market?

Three archetypes dominate. Global tier one suppliers, including Robert Bosch GmbH, DENSO Corporation, ZF Friedrichshafen AG and Aptiv PLC, embed diagnostics in engine controllers, gateways and vehicle architecture. Workshop tool specialists differentiate on coverage and repair information. Fleet and telematics providers differentiate on analytics and scale. Snap-on reported FY2025 net sales of approximately USD 4.74 Billion, while Aptiv reported FY2025 revenue of approximately USD 20.40 Billion. These figures reflect total company revenues rather than revenue specifically generated from automotive OBD products.

What Innovation and Differentiation Strategies Matter Most?

Winning strategies combine protocol breadth with software depth. Vector Informatik supports OBD II, OBDonUDS, ZEVonUDS, HD OBD and WWH OBD, while Snap-on launched the third-generation TRITON in May 2025 and the MT2600 in October 2025. ACTIA is sharing its Multi Diag roadmap for workshop tools, and Marelli added OBD II capable engine controllers in March 2026. Suppliers also expand geographic reach through local partners, notably in India and the Middle East.

What Is the Level of M&A Activity?

M&A activity is selective and mostly portfolio driven. Continental completed the spin-off of its Automotive group sector as AUMOVIO SE on 18 September 2025. Separately, BorgWarner completed its acquisition of Delphi Technologies in October 2020, with Delphi Technologies Aftermarket retaining its brand identity and continuing to offer diagnostic tools and test equipment. Tool specialists and telematics firms continue to add software and data capabilities through small acquisitions and partnerships. We expect further consolidation among regional tool makers as protocol requirements and cybersecurity obligations raise development costs.

Key Market Players

During our market evaluation, we validated the following companies from official filings and company sources, listed in ranked order.

Robert Bosch GmbH DENSO Corporation ZF Friedrichshafen AG AUMOVIO SE Aptiv PLC BorgWarner Inc. Marelli Holdings Co., Ltd. Snap-on Incorporated Autel Intelligent Technology Corp., Ltd. Geotab Inc. LAUNCH TECH COMPANY LIMITED Vector Informatik GmbH TEXA S.p.A. ACTIA Group

Latest Developments

We found that recent developments centre on regulation, workshop tools and fleet data scale.

Date Event
March 2026 Marelli launched port fuel injection engine control units for gasoline, flex fuel and CNG engines with OBD II diagnostics, targeting Brazil, India and EMEA.
October 2025 Snap-on introduced the MT2600 scan tool covering 50 makes back to 1983.
15 May 2025 Snap-on launched the third-generation TRITON scan tool.

Expert Insights

Mark Zachos

Mark Zachos

President | DG Technologies

"Most of the diagnostic trouble codes have to do with the battery pack and the charging system."

Analyst Interpretation

The statement highlights the expansion of vehicle diagnostics beyond conventional engine and emissions monitoring toward battery and charging-system diagnostics in electric vehicles. As electric and hybrid vehicle adoption increases, Automotive On-Board Diagnostics (OBD) Market technology providers will need to develop diagnostic capabilities that cover battery management systems, charging components and advanced electronic architectures. This transition creates opportunities for advanced diagnostic software, scanning devices and compatible communication technologies
Key Benefits for Stakeholders

How Does the Report Benefit Enterprise and Industry Leaders?

Executives gain a quantified view of offering, vehicle type, application and regional growth through 2035. The segment forecasts show where to place capacity, with Software at 12.68% CAGR and fleet and insurance applications at 14.78%. Country level figures for 14 markets support entry decisions, and the competitive analysis of 14 verified companies helps leaders benchmark protocol coverage, channel reach and pricing strategy.

How Does the Report Benefit Investors and Financial Analysts?

Investors receive a reconciled forecast from USD 68.14 Billion in 2025 to USD 181.77 Billion in 2035, with segment and region splits that sum to the total. The growth matrix quantifies each driver and restraint in percentage points of CAGR, helping analysts stress test assumptions. Latest developments and company profiles identify where recurring revenue, regulatory exposure and geographic mix differ among vendors.

How Does the Report Benefit Technology Vendors and Product Teams?

Product teams see which protocols, applications and regions drive demand. The analysis shows rising demand for OBDonUDS and ZEVonUDS support, guided repair software, and connected diagnostic devices used in vehicle repair and fleet management workflows. Regional insights guide localization, pricing and distribution choices, and the discussion of data access and cybersecurity limits informs design decisions before products reach regulators and customers.

Key Market Segments Evaluated

By Offering

  • Hardware
  • Software
  • Services

By Vehicle Type

  • Passenger cars
  • Light commercial vehicles
  • Medium and heavy commercial vehicles

By Application

  • Emissions compliance and inspection
  • Repair and maintenance diagnostics
  • Fleet telematics and insurance

By Region

  • North America 
    • U.S.
    • Canada
    • Rest of North America (Mexico)
  • Europe 
    • Germany
    • UK
    • France
    • Rest of Europe (Italy, Spain, Sweden, Denmark, Finland, Netherlands, Rest of Europe)
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Australia
    • Rest of APAC (Taiwan, Indonesia, Vietnam, Philippines, Malaysia, Rest of APAC)
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • South Africa
    • Rest of MEA (Egypt, Israel, Turkey, Nigeria, Rest of MEA)
  • Latin America 
    • Brazil
    • Argentina
    • Rest of LATAM (Chile, Colombia, Rest of LATAM)

Conclusion & Recommendations

The outlook is positive. The market grows from USD 77.62 Billion in 2026 to USD 181.77 Billion in 2035, adding about USD 104.15 Billion in absolute value. Regulation provides a durable floor, while software and fleet analytics supply the growth. Electrification trims combustion diagnostics after 2028, yet new battery and charging monitoring tasks replace much of that revenue, so the overall trajectory remains firmly upward.

What Strategic Positioning Recommendations Does NMSC Offer?

Vendors should pair hardware coverage with subscription software and prioritize OBDonUDS, ZEVonUDS and heavy-duty protocols. Positioning in Asia-Pacific and Middle East and Africa captures the fastest regional growth, while fleet and insurance applications offer the highest segment growth. Partnerships with OEMs and telematics providers secure data access, and investment in technician training turns tool sales into lasting customer relationships.

What Is the Investment Attractiveness of the Automotive On-Board Diagnostics (OBD) Market?

Attractiveness is high for software and services, and moderate for commodity hardware. Regulation supports demand across cycles, recurring revenue improves visibility, and fragmentation leaves room for consolidation. Valuations should reflect different growth rates, with Software at 12.68% CAGR against Hardware at 7.75%. Investors should favor companies with multi brand coverage, fleet analytics and exposure to Asia-Pacific, where the largest regional value is created.

What Are the Automotive On-Board Diagnostics (OBD) Market Shifts and Key Risks?
Key shifts include rising battery electric vehicle share, manufacturer control of vehicle data and migration to unified diagnostic protocols. The main risks are restrictions on OBD port access for cybersecurity, which our model values at −0.75% of CAGR, and a technician skills gap that slows adoption of advanced tools. Currency swings and import controls add risk in Latin America and parts of Africa.

What Are the Primary Growth Pathways Through 2035?

Growth pathways include connected fleet services, insurance and usage data, heavy duty and light commercial diagnostics, and expansion in India, China and the Gulf. Suppliers serving autonomous trucks and advanced fleets will need continuous diagnostic data to maintain uptime. Services and software should capture more than half of incremental revenue as vehicles add electronic content and regulators extend monitoring requirements.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market Growth Analysis
  • Historical revenue and unit shipment analysis of OBD hardware and software offerings across passenger cars, light commercial vehicles, and heavy commercial vehicles.
  • Identifies which offering and vehicle-type segments have grown fastest, setting a credible baseline for the 2026–2035 forecast.
Company-Level Product Share Analysis
  • Company-level share analysis of OBD devices, telematics modules, and software platforms by offering and vehicle type.
  • Highlights competitive positioning gaps and supports product portfolio and pricing decisions.
Country-Level Trade Assessment
  • Country-wise import and export analysis of OBD dongles, telematics control units, and related electronic components.
  • Supports sourcing strategy, manufacturing location decisions, and identification of import-dependent markets.
Regulatory Mandate Demand Mapping
  • Country-level mapping of OBD and emissions-monitoring mandates (such as EOBD, Euro 7, and India and China OBD rules) linked to vehicle type and compliance timelines.
  • Pinpoints mandate-driven demand windows and helps prioritize market entry and product certification investments.
Installed Base Connectivity Penetration Analysis
  • Analysis of the in-use OBD-compliant vehicle base by vehicle type, split between factory-embedded connectivity and aftermarket plug-in devices.
  • Quantifies the addressable aftermarket pool and guides retrofit versus OEM-channel strategy.
Application-Level Revenue Opportunity Assessment
  • Revenue pool estimates for fleet telematics, usage-based insurance, and predictive maintenance applications by offering and vehicle type, based on listed telematics providers' disclosures.
  • Shows which application use cases offer the highest software and service revenue potential, supporting partnership and investment priorities.

FAQs

Sources & References

1.

U.S. eCFR, 40 CFR 86.1806-17

ecfr.gov
2.

EUR-Lex, Implementing Regulation (EU) 2025/1707

eur-lex.europa.eu
3.

EUR-Lex, Regulation (EU) 2018/858

eur-lex.europa.eu
4.

UNECE GRPE, Euro 7

unece.org
5.

ACEA, Average age of EU vehicle fleet

acea.auto
6.

China MEE, GB 17691—2018

mee.gov.cn
7.

India ARAI, CMVR TAP

araiindia.com
8.

Geotab, 5 million subscriptions release

geotab.com
9.

Marelli, engine control units release

marelli.com
10.

Snap-on, Press Release Archive

snapon.com
11.

Snap-on, FY2025 Form 10-K

snapon.com
12.

Aptiv, Q4 2025 results

ir.aptiv.com
13.

Robert Bosch GmbH, Annual Report 2025

assets.bosch.com
14.

Bosch Aftermarket, ECU diagnostic tools

boschaftermarket.com
15.

DENSO, Integrated Report 2025

denso.com
16.

ZF Friedrichshafen AG, Annual Report 2025

zf.com
17.

AUMOVIO, Telematic control unit

engineering-solutions.aumovio.com/components/tcu
18.

BorgWarner, Annual Report

sec.gov
19.

Delphi Technologies, OBD diagnostics

delphiautoparts.com
20.

Autel, 2025 Annual Report

static.cninfo.com.cn
21.

Launch Tech, HKEX filing

www1.hkexnews.hk
22.

TEXA, Company

texa.com/company
23.

Vector Informatik, OBD

vector.com
24.

ACTIA, Multi Diag roadmap

actia.com

Investment Opportunities

Where Is Capital Flowing in the Automotive On-Board Diagnostics (OBD) Market?

Capital is flowing toward software, cloud analytics and fleet platforms. Geotab's 630 patents and 5 million subscriptions show how data scale attracts investment, while tool specialists direct research spending toward new protocol coverage and guided repair. Investors should favour vendors with recurring revenue, multi brand coverage and exposure to Asia-Pacific and fleet applications, since these segments grow faster than the overall market.

Which Infrastructure Investments Support Growth?

Infrastructure spending centres on cloud platforms, connectivity and inspection capacity. Governments widening periodic inspection and remote emission monitoring need certified readers, data centres and trained inspectors, while fleets invest in gateways and Internet of Things connectivity to stream diagnostic data. Workshops also need training, calibration equipment and high voltage safety tools for electrified vehicles, which creates demand for services alongside hardware.

How Do ESG Considerations Shape Investment?

Environmental performance is the core ESG link. OBD systems exist to catch emission control faults, and stronger enforcement under Euro 7 and U.S. rules reduces excess pollutants from in use vehicles. Right to repair and open data access support independent workshops and fair competition, while cybersecurity and privacy controls protect drivers. Investors increasingly screen vendors on compliance, data governance and product repairability.

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Mohit Agarwal

MOHIT AGARWAL

Chief Manager

DryChem India Pvt. Ltd.

Next Move Strategy Consulting is an amazing team of consultants. We required a market study report for our investors on top priority and the team went above and beyond our expectations to deliver the same with ample supporting data within a short time span enabling us to secure the investments and keep our project timeline maintained. Their professionalism, attention to detail, and timely delivery of actionable recommendations have left a lasting impression on our organization.

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖