Canada Fabric Care Market, By Product Type {Fabric Detergents (General Purpose, Baby Laundry Detergent, and Delicate Laundry Detergent), Fabric Softeners/Conditioners, and Others}, By Form (Liquid, Powder, Unit-Dose, Sheet & Wipe, and Spray), By Nature (Conventional and Eco-friendly / Organic), By Price Tier (Value, Mid-range, and Premium), By Distribution Channel (Online and Offline), and By End-User (Residential, Commercial, and Others) – Analysis & Forecast, 2025–2035
Industry: Retail and Consumer | Latest Edition: August 17, 2026 | No of Pages: 155 | No. of Tables: 49 | No. of Figures: 43 | Format: PDF | Report Code: RC4556
Canada Fabric Care Market Size & Forecast
|
Parameters |
Details |
|
Market Size in 2025 |
USD 3.35 billion |
|
Market Size in 2026 |
USD 3.78 billion |
|
Revenue Forecast in 2035 |
USD 5.37 billion |
|
Growth Rate |
CAGR of 4% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 companies |
Industry Outlook
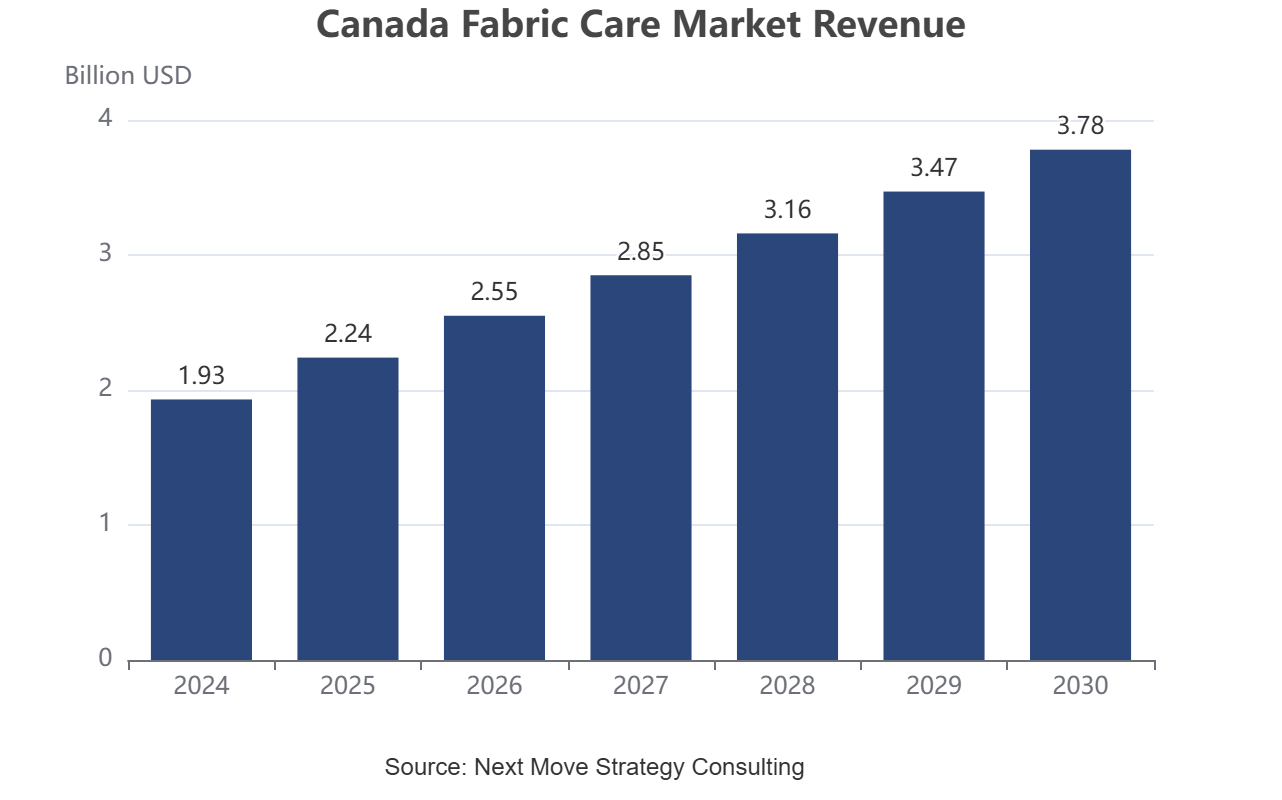
The Canada Fabric Care Market was valued at USD 3.35 billion in 2025 and is estimated to reach USD 3.78 billion in 2026, supported by steady household demand, premiumization across detergents and softeners, and the expanding reach of online retail. Looking ahead, the market is projected to grow to USD 5.37 billion by 2035, registering a CAGR of 4% between 2026 and 2035. This sustained expansion reflects a gradual shift toward eco-friendly formulations, concentrated and unit-dose formats, and value-added fabric care solutions across Canadian households and commercial laundry operators.
What Are the Key Growth Drivers, Restraints, and Opportunities Shaping the Canada Fabric Care Industry Through 2035?
Growth Catalyst & Risk Assessment Matrix
|
Drivers / Trends / Restraints |
(+/-) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Consumer premiumization toward concentrated and unit-dose fabric care formats driving higher average selling prices and value growth across Canadian retail channels |
+3.2% |
National (all provinces) |
Long term (4–7 years) |
|
Expansion of online and quick-commerce grocery retail channels enabling broader and more frequent fabric care purchasing occasions and brand-direct e-commerce growth |
+2.8% |
Urban centres (Toronto, Vancouver, Montreal) |
Medium to long term (3–6 years) |
|
Rising demand for VOC-compliant, eco-certified, and biodegradable fabric care formulations supported by Canada's regulatory framework and environmentally conscious consumer segments |
+2.4% |
British Columbia, Ontario, Quebec |
Medium term (2–5 years) |
|
Near-universal household penetration, flat-to-declining near-term population growth, and expanding private-label detergent offerings from major Canadian grocers restraining volume and pricing upside |
–1.8% |
National, concentrated in value and mid-range tiers |
Short to medium term (1–4 years) |
The Canada Fabric Care Market reflects a mature, brand-intensive home care category shaped by near-universal household penetration, a sophisticated retail infrastructure, and a steady shift toward sustainability-led product innovation. Growth is anchored less in volume expansion and more in value upgrading, as Canadian households trade up to concentrated formats, eco-certified formulations, and convenience-driven unit-dose products. Regulatory alignment around VOC and phosphorus limits, combined with the rapid build-out of online and quick-commerce grocery channels, is reshaping how fabric care products are formulated, packaged, and distributed nationwide, reinforcing a moderate but consistent long-term growth trajectory through 2035.
Growth Drivers
How Is Consumer Demand for Premium and Concentrated Fabric Care Formats Driving Market Value Growth in Canada?
Canadian consumers are increasingly trading up from standard detergents to concentrated liquids, unit-dose pods, and sachets that promise stronger cleaning performance with smaller pack sizes and reduced plastic use per wash. This shift mirrors a broader premiumization pattern across the household care aisle, where shoppers associate compact, technology-forward formats with superior fabric protection, fragrance retention, and cold-water efficacy. Manufacturers are responding with dose-concentration increases and recycled-content packaging redesigns, supporting higher average selling prices even as overall wash volumes remain largely flat across Canada's near-saturated household base.
How Is the Expansion of Online and Quick-Commerce Retail Reshaping Fabric Care Distribution in Canada?
E-commerce now accounts for a meaningful and growing share of Canadian retail sales, with major grocers expanding click-and-collect networks, dark-store fulfillment, and same-day delivery to meet rising convenience expectations. Fabric care products benefit directly from this shift, as bulky multi-load detergent packs and subscription-based replenishment translate well to online baskets, while quick-commerce platforms increasingly stock smaller-format detergents and stain removers for urgent, last-minute purchases. This expanding digital footprint is giving brand-e-commerce and marketplace channels a growing share of category sales alongside Canada's traditional supermarket and hypermarket networks.
How Is Sustainability-Led Reformulation Strengthening Demand for Eco-Friendly Fabric Care Products in Canada?
Health Canada's Volatile Organic Compound Concentration Limits and longstanding phosphorus restrictions are pushing manufacturers toward biodegradable surfactants, fragrance-free variants, and EcoLogo-certified formulations across the detergent and fabric softener aisle. Independent Canadian brands built around plastic-reduced packaging, such as laundry sheets and refillable concentrates, are capturing share from environmentally engaged shoppers, particularly in British Columbia and Ontario. While many Canadians remain skeptical of vague green marketing claims, demand for verifiable, third-party-certified eco-friendly fabric care continues to climb, encouraging both multinational and independent players to expand low-impact product lines.
Growth Inhibitor
What Factors Are Restraining Faster Growth in the Canada Fabric Care Market?
Canada's fabric care category faces near-universal household penetration and a softening near-term population growth outlook, with national population trends flattening through 2026 amid lower immigration admissions targets, constraining the volume upside available to manufacturers. Smaller average household sizes and a mild generational shift away from fabric softener use among younger consumers further limit per-capita consumption growth. At the same time, compliance with VOC and phosphorus regulations raises reformulation and testing costs, while private-label detergents from major grocers exert continuous downward pressure on branded pricing power across value and mid-range tiers.
Growth Opportunity
What Growth Opportunities Exist for Fabric Care Brands Expanding Within Canada Through 2035?
Significant white space remains in underserved regional markets, particularly Quebec, where French-language eco-positioned brands can capture first-mover advantage in a province representing close to a quarter of Canada's population. Premium and specialist product tiers, projected to expand from roughly a quarter to nearly half of category value by 2035, offer manufacturers room to introduce hypoallergenic, activewear-specific, and dermatologist-tested formulations. Direct-to-consumer subscription models, expanding quick-commerce penetration, and renewed immigration-driven population growth expected from 2027 onward together create durable channels for premium and eco-certified fabric care brands to scale nationally.
Consumer Behavior Analysis of the Canada Fabric Care Industry
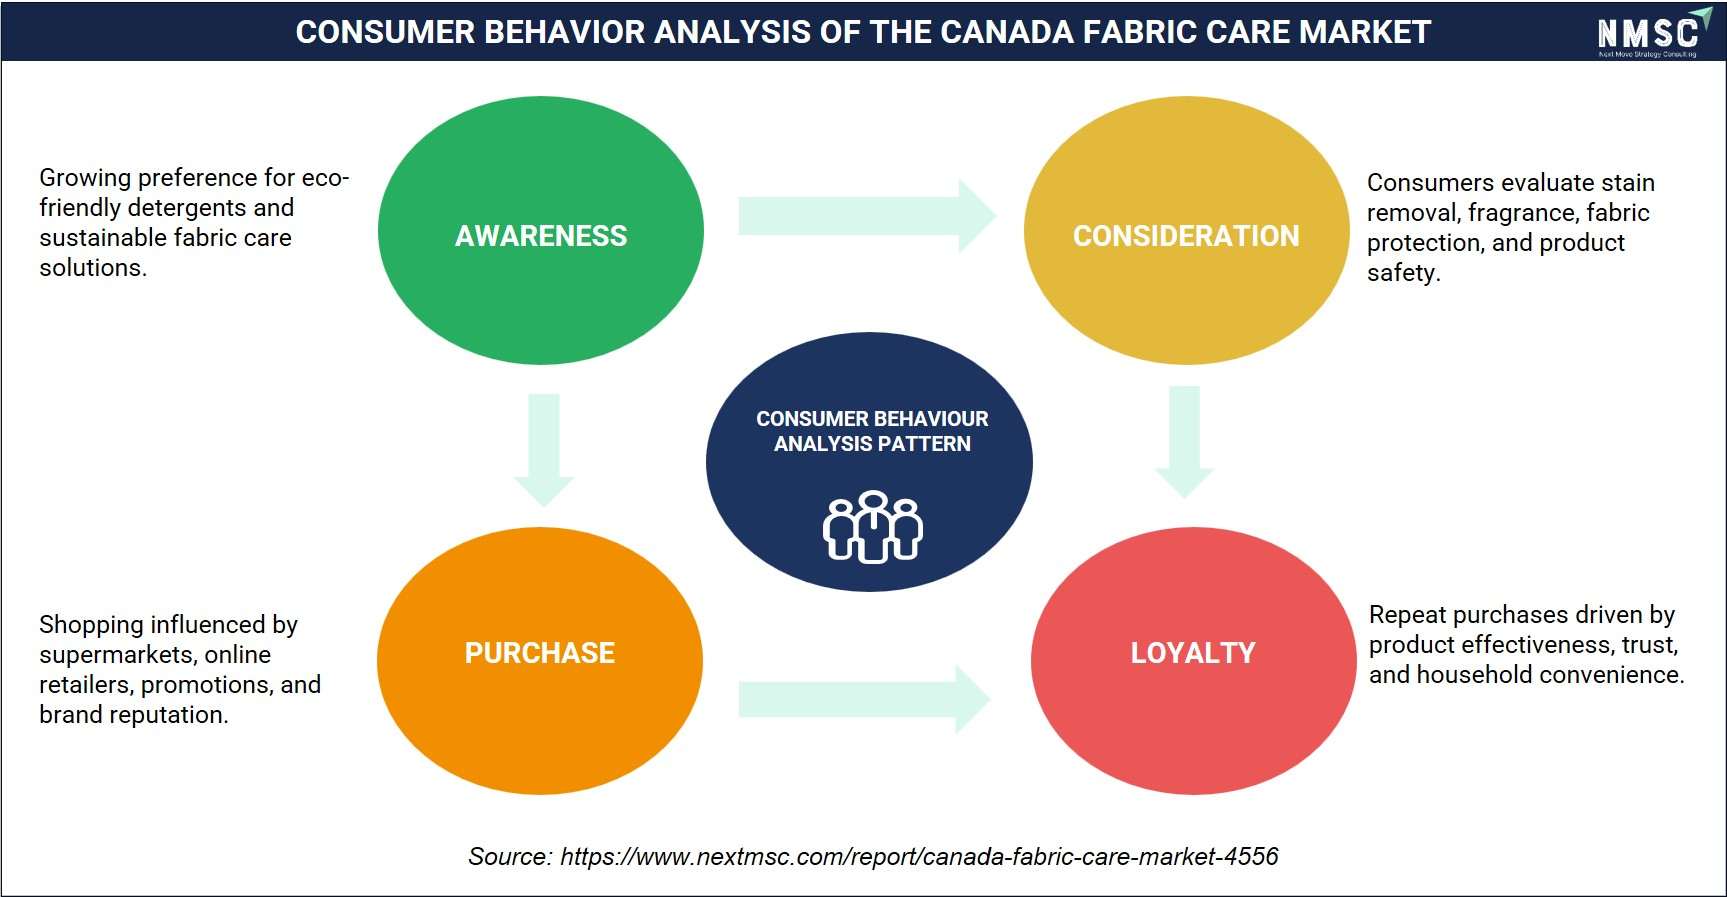
The above consumer behavior analysis maps the key decision-making stages, such as awareness, consideration, purchase, and loyalty, shaping the Canada fabric care market. From our analysis, we observed that awareness reflects a growing preference for eco-friendly detergents and sustainable fabric care solutions, while consideration involves shopping influenced by supermarkets, online retailers, promotions, and brand reputation. During purchase, consumers select these channels, whereas brand loyalty is ultimately driven by repeat purchases influenced by product effectiveness, trust, and household convenience.
How Is the Canada Fabric Care Market Segmented in This Report, and What Are the Key Insights from the Segmentation Analysis?
By Product Type Insights
Which Product Type Leads the Canada Fabric Care Market, and Why?
Based on product type, the Canada market is segmented into fabric detergents, general purpose, baby laundry detergent, and delicate laundry detergent, fabric softeners/conditioners, stain removers/bleach, sanitizer, and other products.
The market reflects a diverse product portfolio that addresses routine laundry, specialized fabric care, and evolving hygiene requirements across Canadian households. In our observation, fabric detergents are widely used across general purpose, baby laundry, and delicate laundry applications, catering to different washing needs and fabric types. Complementing these, fabric softeners and conditioners enhance fabric comfort and freshness, while stain removers, bleach, and sanitizers support targeted cleaning and hygiene-focused laundering. Other products further address niche fabric care requirements, contributing to a more comprehensive and performance-oriented laundry ecosystem.
By Price Tier Insights
How Does Price Tier Segmentation Reflect Consumer Spending Patterns Across the Canada Fabric Care Market?
Based on price tier, the Canada market is segmented into value, mid-range, and premium.
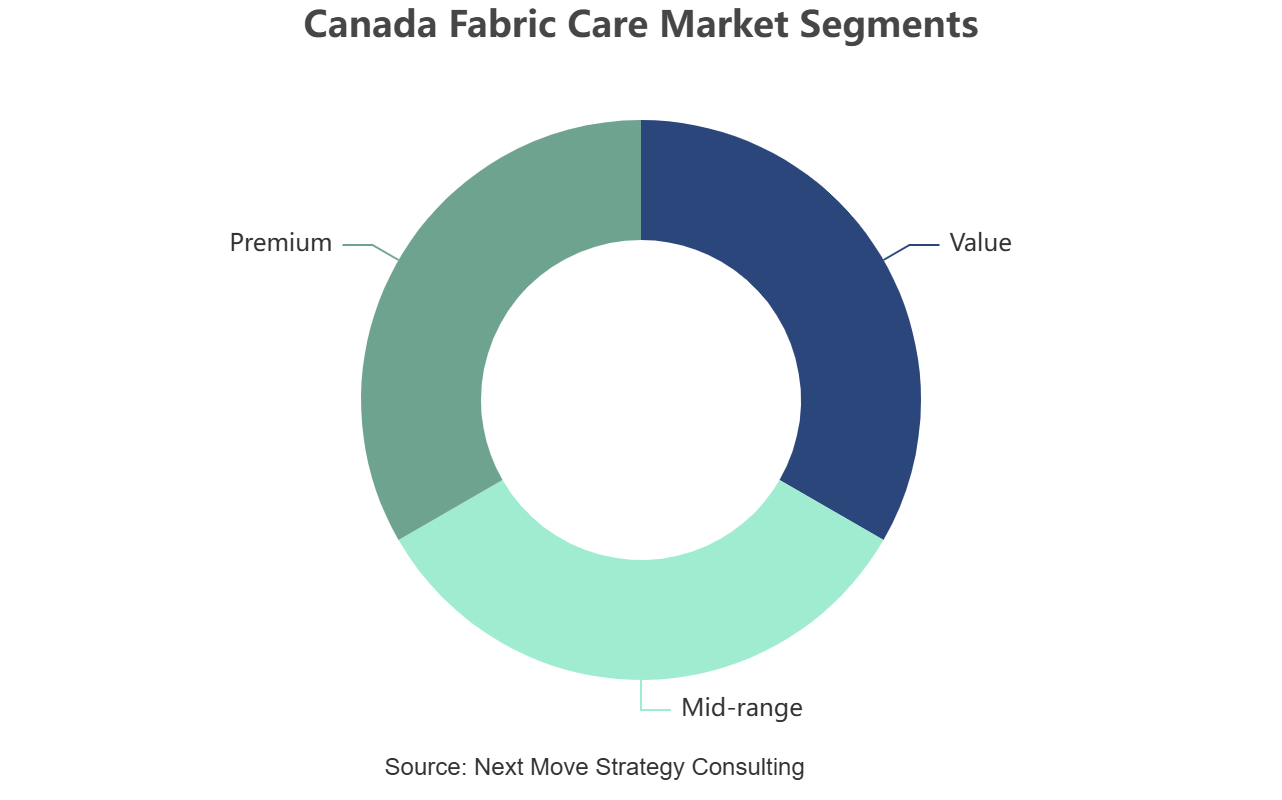
The market demonstrates a balanced pricing landscape as consumers increasingly evaluate fabric care products based on affordability, performance, and perceived value. According to our analysis, we found that value-tier products continue to attract price-conscious households seeking cost-effective everyday laundry solutions, while mid-range offerings appeal to consumers looking for an optimal balance between quality and price. At the same time, premium products are gaining wider acceptance as demand grows for specialized formulations, advanced stain removal, fabric protection, and sustainability-focused features.
Supply Chain Structure of the Canada Fabric Care Industry
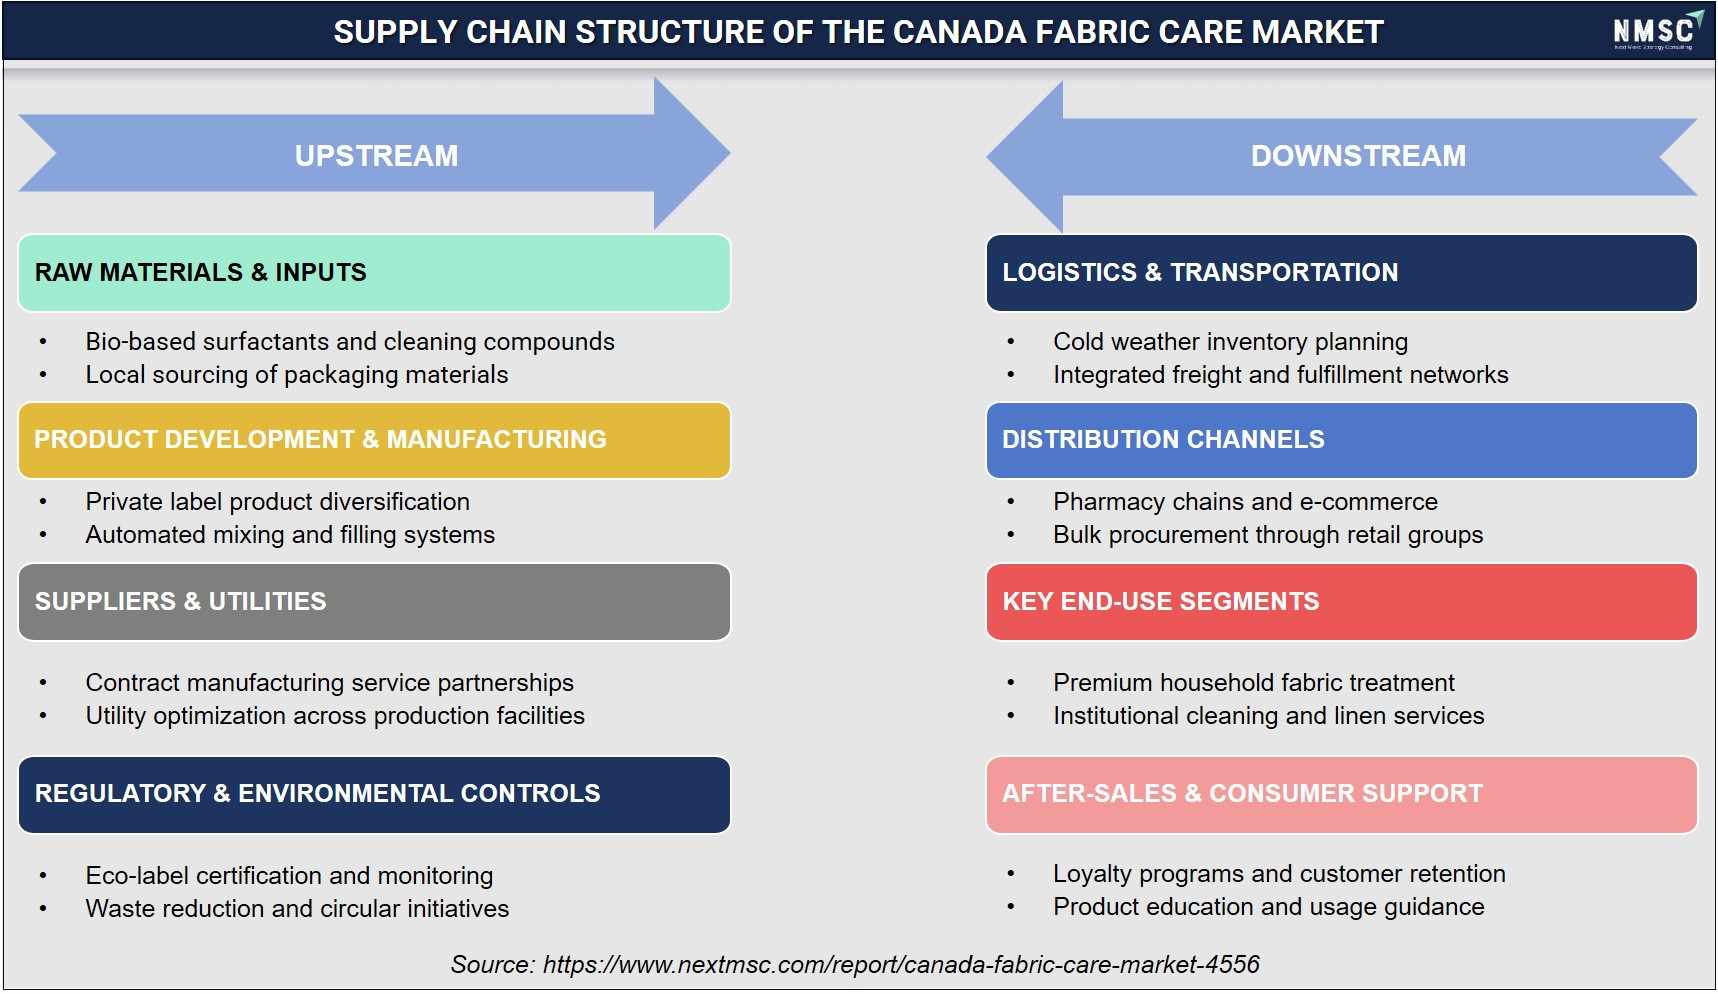
The above supply chain analysis maps the key stages, such as upstream, downstream, raw materials, manufacturing, logistics, distribution, end-use segments, and after-sales support, shaping the Canada fabric care market. From our analysis, we observed that upstream focuses on bio-based surfactants and local packaging materials, while manufacturing advances private label diversification and automated systems. Regulatory controls enforce eco-label certification and waste reduction. Downstream, logistics manages cold-weather inventory and integrated freight networks, while distribution penetrates pharmacy chains and e-commerce. Key end-users include premium households and institutional services, whereas after-sales support delivers loyalty programs and product education guidance.
Key Segments
By Product Type
-
Fabric Detergents
-
General Purpose
-
Baby Laundry Detergent
-
Delicate Laundry Detergent
-
-
Fabric Softeners/Conditioners
-
Stain Removers/Bleach
-
Sanitizer
-
Other Products
By Form
-
Liquid
-
Powder
-
Unit-Dose
-
Pods
-
Sachets
-
-
Sheet & Wipe
-
Spray
By Nature
-
Conventional
-
Eco-friendly / Organic
By Price Tier
-
Value
-
Mid-range
-
Premium
By Distribution Channel
-
Online
-
Marketplaces
-
Brand E-com
-
Quick Commerce
-
-
Offline
-
Supermarkets
-
Hypermarkets
-
Department Stores
-
By End-User
-
Residential
-
Commercial
-
Others
Competitive Landscape
The Canada Fabric Care Market features a layered competitive structure that blends large multinational consumer goods manufacturers with established regional players and a growing cohort of independent, sustainability-focused challenger brands. Competitive intensity centers on product innovation across concentrated and unit-dose formats, eco-certification credentials, and fragrance and fabric-protection technology, alongside aggressive promotional activity within Canada's major grocery and mass-retail channels. Private-label detergents from leading national grocers add further pricing pressure, prompting branded manufacturers to differentiate through premiumization, direct-to-consumer subscription models, and expanding e-commerce-specific packaging formats tailored to Canadian shoppers.
Strategic Developments
-
February 2026 – Tru Earth Environmental Products Inc. expanded into Costco Canada’s physical retail network, launching its Laundry Detergent Sheets in 14 British Columbia warehouse locations following its online presence on Costco.ca.
Key Players
-
Henkel Canada Corporation
-
Reckitt Benckiser (Canada) Inc.
-
The Clorox Company of Canada, Ltd.
-
Church & Dwight Canada Corp.
-
Kao Canada Inc.
-
S.C. Johnson and Son, Limited
-
Diversey Canada, Inc.
-
Colgate-Palmolive Canada Inc.
-
Patanjali Ayurved Limited
-
Amway Canada Corporation
-
Croda Canada Ltd.
-
Tru Earth Environmental Products Inc.
-
Nellie's All-Natural Inc.
-
Eco-Max Inc.
Key players shaping the Canada Fabric Care Market include Unilever Canada Inc., Henkel Canada Corporation, Reckitt Benckiser (Canada) Inc., The Clorox Company of Canada, Ltd., and Church & Dwight Canada Corp. Challenger and specialty brands such as Tru Earth Environmental Products Inc., Nellie's All-Natural Inc., Eco-Max Inc., Croda Canada Ltd., and Patanjali Ayurved Limited continue to expand their footprint through eco-positioned formulations and direct-to-consumer channels, intensifying competition across both conventional and sustainability-led segments of the market.
Key Benefits for Stakeholders
Next Move Strategy Consulting (NMSC) presents a comprehensive analysis of the Canada Fabric Care Industry, covering historical trends from 2025 through the base year and offering detailed forecasts through 2035. The study examines the market at the national level, providing quantitative projections and qualitative insights into key growth drivers, restraints, and opportunities across all major fabric care segments, including product type, form, nature, price tier, distribution channel, and end-user. This structured approach equips stakeholders with a clear, decision-ready view of where Canadian household and commercial demand for fabric care products is headed over the coming decade.
Manufacturers and retailers benefit from sustained demand anchored in one of North America's most stable household care markets, where regulatory clarity, established distribution infrastructure, and rising consumer sophistication reinforce long-term revenue visibility. Investors gain access to detailed segmentation and competitive profiling that clarify where premiumization, eco-certification, and channel-shift opportunities are concentrated, while brand owners and new entrants benefit from clear identification of underserved regional pockets and price tiers. Together, these insights support more confident decisions around market entry, product positioning, and channel investment across Canada's fabric care landscape.
|
Parameters |
Details |
|
Customization Scope |
Free customization (equivalent to up to 80 analyst-working hours) after purchase. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |
|
Approach |
In-depth primary and secondary research; proprietary databases; rigorous quality control and validation measures. |
|
Analytical Tools |
Porter’s Five Forces, SWOT, value chain, and Harvey ball analysis to assess competitive intensity, stakeholder roles, and relative impact of key factors. |
Conclusion
The Canada Fabric Care Market is positioned for steady, value-led growth, expanding from USD 3.78 billion in 2026 to USD 5.37 billion by 2035 at a CAGR of 4%. Growth will be driven less by volume and more by premiumization, eco-certified reformulation, and the continued build-out of online and quick-commerce retail channels, even as near-universal household penetration and regulatory compliance costs temper the pace of expansion. Competitive dynamics will intensify as multinational leaders, regional manufacturers, and independent sustainability-focused brands compete for share, with Quebec's underserved market and the premium tier offering the clearest runway for future opportunity.
About the Author
 Mayurima Roy
— Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

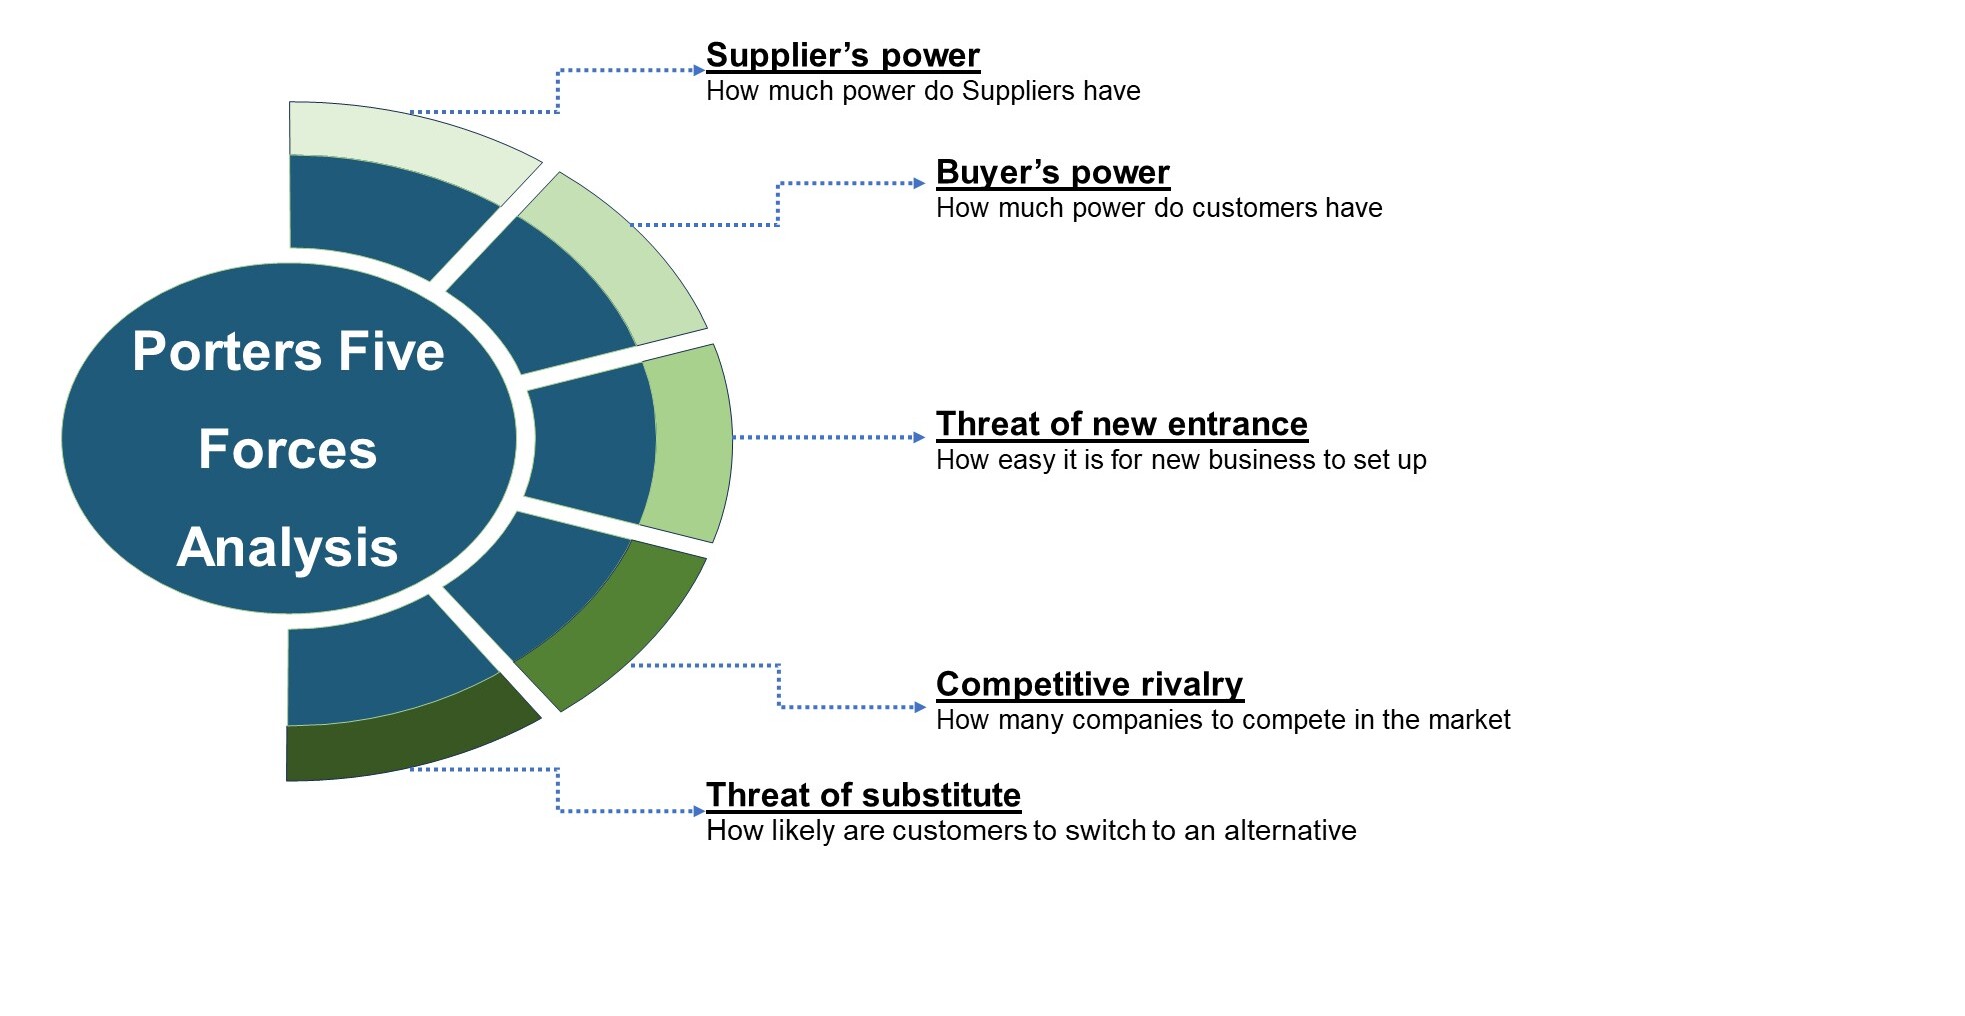
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.




 Speak to Our Analyst