Healthcare Provider Network Management Market Global Industry Analysis and Forecast (2026-2035)

Healthcare provider network management market size is estimated at USD 9.70 billion in 2026, projected to reach USD 41.20 billion by 2035, growing at a CAGR of 17.43% from 2026 to 2035. Key drivers include mandated network adequacy compliance, rising provider data accuracy regulation, and cloud-based credentialing automation, with North America leading the market and Asia-Pacific registering the fastest growth.

Download Free Sample PDF
Base Year (2025)
$6.20 Billion
Forecast (2035)
$41.20 Billion
CAGR (2026-2035)
17.4%
Top Region
North America

What Is the Healthcare Provider Network Management Market Size?

The global healthcare provider network management market size was valued at USD 6.20 billion in 2025 and is estimated at USD 9.70 billion in 2026, forecast to reach USD 41.20 billion by 2035, expanding at a 17.43% CAGR between 2026 and 2035. North America leads with approximately 58% share, while Software dominates all other components with approximately 68% share.

We observed that growth is broad-based across every segmentation axis, with network adequacy analytics and cloud-based deployment driving the most pronounced structural shifts through 2035.

Healthcare Provider Network Management Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $6.20 Billion
2025
2026 $7.28 Billion
2026
2027 $8.55 Billion
2027
2028 $10.04 Billion
2028
2029 $11.79 Billion
2029
2030 $13.84 Billion
2030
2031 $16.26 Billion
2031
2032 $19.09 Billion
2032
2033 $22.42 Billion
2033
2034 $26.33 Billion
2034
2035 $41.20 Billion
2035

Key Takeaways

By Component: Software held the largest share of approximately 68% (USD 4.22 Billion) in 2025; Services is the fastest-growing sub-segment at 19.5% CAGR from 2026–2035.

By Deployment Mode: Cloud held the largest share of approximately 71% (USD 4.40 Billion) in 2025; On-Premise declines in relative share while Cloud is also the fastest-growing sub-segment at 19.1% CAGR from 2026–2035.

By Application: Provider Data Management held the largest share of approximately 30% (USD 1.86 Billion) in 2025; Network Adequacy Analytics is the fastest-growing sub-segment at 19.9% CAGR from 2026–2035.

By End User: Health Plans and Payers held the largest share of approximately 58% (USD 3.60 Billion) in 2025; Government Health Programs is the fastest-growing sub-segment at 21.0% CAGR from 2026–2035.

By Organization Size: Large Enterprises held the largest share of approximately 66% (USD 4.09 Billion) in 2025; Small and Medium Enterprises is the fastest-growing sub-segment at 19.7% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 58% revenue share (USD 3.60 Billion) in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 21.9% during 2026–2035.

Dominant Country: U.S. led with approximately USD 3.35 Billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 24.8% CAGR from 2026–2035.

Market Opportunity: The healthcare provider network management market is expected to create an absolute dollar opportunity of USD 31.50 billion between 2026 and 2035, presenting significant investment potential across network adequacy analytics and government health program deployments.

According to NMSC analysis, health plans are increasingly consolidating point solutions around unified cloud-based platforms that combine credentialing, contracting, and directory management, a shift that favors full-suite vendors over single-function tools as regulatory scrutiny of provider directory accuracy intensifies through 2035.

What Does the Healthcare Provider Network Management Market Encompass?

The market encompasses software and services that help health plans, health systems, and third-party administrators manage the full lifecycle of provider relationships, including credentialing, contracting, network adequacy analytics, and directory accuracy. Our assessment indicates that the scope spans cloud and on-premise deployment models sold to health plans, provider organizations, government health programs, and third-party administrators across regulated healthcare markets worldwide. The category has evolved from fragmented, manually maintained provider spreadsheets into an integrated software category, driven by rising regulatory scrutiny of provider directory accuracy and network adequacy compliance mandates.

We observed that federal and state regulatory bodies increasingly enforce provider directory accuracy and network adequacy standards, while national quality accreditation organizations shape credentialing certification requirements. NMSC's analysis indicates that technology adoption is shifting toward cloud-native, API-integrated platforms that automate primary source verification and roster intake, a structural shift redefining sourcing criteria across the market.

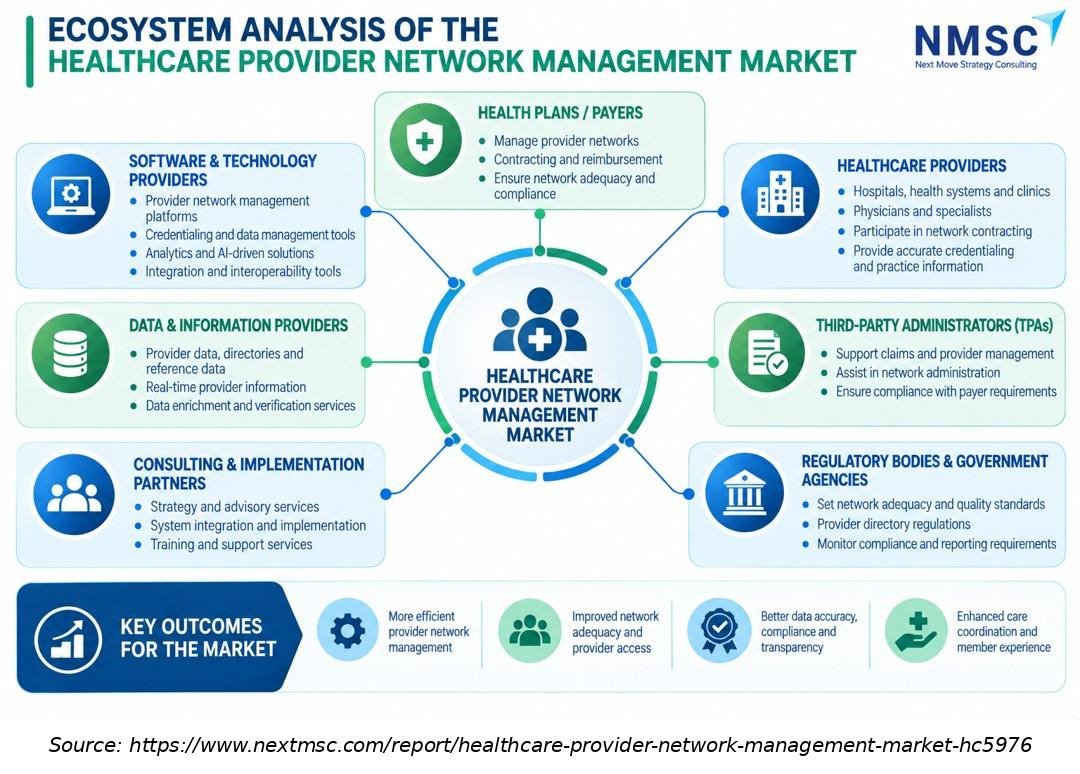
Ecosystem Analysis

Market Drivers & Dynamics

Interactive Dataset
Mandated provider directory accuracy and network adequacy compliance driver +3.8% North America 2026–2035
Rising cloud-based credentialing automation adoption driver +3.1% Global 2026–2032
Expanding value-based care network performance monitoring driver +2.6% North America, Europe 2026–2032
Growing government health program administration digitization driver +2.2% Asia-Pacific, North America 2026–2035
Rising multi-state health plan network complexity driver +1.8% North America 2026–2032
Expanding health IT infrastructure investment in emerging markets driver +1.5% Asia-Pacific 2026–2035
High integration cost with legacy core administration systems restraint −1.4% Global 2026–2032
Data privacy and interoperability compliance burden restraint −1.0% North America, Europe 2026–2035
Limited provider network management IT budgets among small payers restraint −0.8% Global 2026–2032
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Healthcare Provider Network Management Market?

Mandated provider directory accuracy and network adequacy compliance is the primary driver of the market. The U.S. Centers for Medicare & Medicaid Services enforces provider directory accuracy requirements under its Medicare Advantage and Marketplace network adequacy rules, requiring health plans to validate provider data on a defined cadence. We observed that this regulatory trajectory, reinforced by state-level network adequacy filing mandates, continues to anchor demand for provider network management platforms across developed healthcare markets.

How Is Value-Based Care Driving Healthcare Provider Network Management Market Growth?

Expanding value-based care network performance monitoring is accelerating growth in analytics-enabled platform categories. The U.S. Department of Health and Human Services continues to expand value-based payment models that require health plans to monitor provider performance against quality and cost benchmarks. Our assessment indicates that this policy pathway is compressing implementation timelines for network performance analytics modules across North American and European health plans.

Growth Inhibitors

What Is Restraining Healthcare Provider Network Management Market Expansion?

High integration cost with legacy core administration systems restrains market expansion, particularly among small and regional health plans. National health IT standards bodies indicate that interoperability requirements between provider network management platforms and legacy claims systems remain a persistent implementation barrier. We found that health plans lacking dedicated IT integration resources face particular exposure, as incomplete data synchronization reduces the accuracy benefits that modern platforms are designed to deliver.

What Are the Growth Opportunities?

How Can Continuous Monitoring Modules Unlock Value for Mid-Size Health Plans?

Continuous credentialing and sanction monitoring modules present a whitespace opportunity for suppliers serving mid-size regional health plans lacking dedicated compliance staff. Vendors that commercialize automated, always-on monitoring stand to capture recurring subscription contracts as regulators tighten re-credentialing cycle expectations.

Where Does Government Health Program Digitization Create New Demand?

Government health program network digitization represents an underpenetrated opportunity for suppliers targeting Medicaid managed care organizations and national health insurance administrators. Providers that package configurable, government-compliant network management platforms can secure long-term public sector contracts, benefiting from recurring maintenance revenue tied to multi-year procurement cycles.

How Can API-Based Interoperability Benefit Multi-Payer Data Exchange?

API-based interoperability between provider network management platforms and core administration systems creates an opportunity for suppliers serving multi-payer data exchange networks. Early movers that standardize provider data exchange formats can differentiate ahead of broader national interoperability rulemaking through 2035.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Software 2025: $4.22 Billion | 2035: $26.78 Billion
Software
Services 2025: $1.98 Billion | 2035: $14.42 Billion
Services
Software $4.22 Billion $26.78 Billion 16.8%
Services $1.98 Billion $14.42 Billion 19.5%

Which Component Dominates the Healthcare Provider Network Management Market?

Software led the market with USD 4.22 billion in 2025, supported by health plan preference for licensed platforms that centralize credentialing, contracting, and directory management. We observed that Services is the fastest-growing component, expanding at a 19.5% CAGR from 2026 to 2035, as health plans increasingly outsource implementation, data cleansing, and managed credentialing support to specialized service providers.

2025 (USD Billion)
2035 (USD Billion)
Cloud
On-Premise
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Cloud $10.0 USD Billion $40.0 USD Billion 9.0%
On-Premise $17.1 USD Billion $51.1 USD Billion 23.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Deployment Mode.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Provider Dat
Credentialin
Network Adeq
Provider Dir
Contracting
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Provider Data Management $10.0 USD Billion $40.0 USD Billion 18.0%
Credentialing and Primary Source Verification $17.1 USD Billion $51.1 USD Billion 16.0%
Network Adequacy Analytics $24.2 USD Billion $62.2 USD Billion 22.0%
Provider Directory Management $31.3 USD Billion $73.3 USD Billion 12.0%
Contracting and Fee Schedule Management $38.4 USD Billion $84.4 USD Billion 19.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data

Which Application Leads Healthcare Provider Network Management Market Demand?

Provider Data Management remained the dominant application across the market, reaching USD 1.86 billion in 2025 due to its foundational role underpinning credentialing, contracting, and directory functions. Our findings suggest that Network Adequacy Analytics is the fastest-growing application, registering a 19.9% CAGR from 2026 to 2035, as health plans scale automated adequacy modeling to meet expanding state and federal filing requirements.

2025 (USD Billion)
2035 (USD Billion)
Health Plans
Provider Org
Third-Party
Government H
Other End Us
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Health Plans and Payers $10.0 USD Billion $40.0 USD Billion 26.0%
Provider Organizations and Health Systems $17.1 USD Billion $51.1 USD Billion 16.0%
Third-Party Administrators $24.2 USD Billion $62.2 USD Billion 18.0%
Government Health Programs $31.3 USD Billion $73.3 USD Billion 8.0%
Other End User $38.4 USD Billion $84.4 USD Billion 23.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data

Which End User Drives the Healthcare Provider Network Management Market?

Health Plans and Payers remained the leading end user within the market, valued at USD 3.60 billion in 2025 on sustained regulatory obligation to maintain accurate provider networks. Based on research conducted by NMSC, we found that Government Health Programs is the fastest-growing end user, registering a 21.0% CAGR from 2026 to 2035, as public health agencies scale digitized network administration for Medicaid managed care and national health insurance programs.

2025 (USD Billion)
2035 (USD Billion)
Large Enterp
Small and Me
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Large Enterprises $10.0 USD Billion $40.0 USD Billion 10.0%
Small and Medium Enterprises $17.1 USD Billion $51.1 USD Billion 24.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Organization Size.

Unlock Full Data

Growth Opportunities

Three forward-looking whitespace opportunities stand out for suppliers positioning ahead of 2035 demand across the healthcare provider network management market.

How Can Continuous Monitoring Modules Unlock Value for Mid-Size Health Plans?

Continuous credentialing and sanction monitoring modules present a whitespace opportunity for suppliers serving mid-size regional health plans lacking dedicated compliance staff. Vendors that commercialize automated, always-on monitoring stand to capture recurring subscription contracts as regulators tighten re-credentialing cycle expectations.

Where Does Government Health Program Digitization Create New Demand?

Government health program network digitization represents an underpenetrated opportunity for suppliers targeting Medicaid managed care organizations and national health insurance administrators. Providers that package configurable, government-compliant network management platforms can secure long-term public sector contracts, benefiting from recurring maintenance revenue tied to multi-year procurement cycles.

How Can API-Based Interoperability Benefit Multi-Payer Data Exchange?

API-based interoperability between provider network management platforms and core administration systems creates an opportunity for suppliers serving multi-payer data exchange networks. Early movers that standardize provider data exchange formats can differentiate ahead of broader national interoperability rulemaking through 2035.

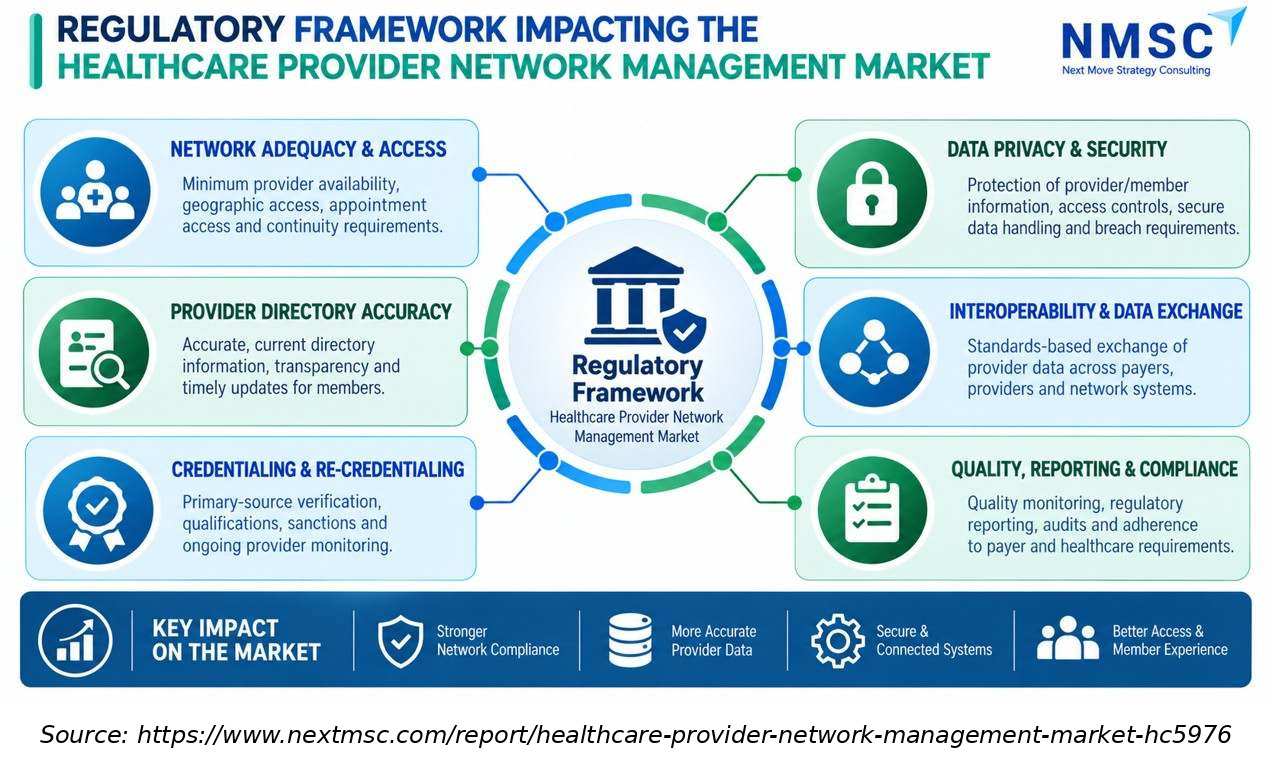
Regulatory Framework Impacting The Healthcare Provider Network Management Market

This infographic presents the Regulatory Framework impacting the Healthcare Provider Network Management Market, covering network adequacy and access, provider directory accuracy, credentialing and re-credentialing, data privacy and security, interoperability and data exchange, and quality, reporting, and compliance. It highlights how regulatory requirements influence provider data management, network design, secure information exchange, ongoing provider verification, reporting practices, and member access, supporting compliant and transparent healthcare network operations.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the healthcare provider network management market features a moderately fragmented competitive landscape, with established U.S. health IT vendors competing alongside diversified healthcare technology majors on platform breadth, analytics depth, and payer relationship scale.

Dimension Description
Dimension Assessment
Market Structure Moderately fragmented; leading companies profiled in this report account for a meaningful share of Industry revenue, while numerous regional health IT vendors and consultancies serve fragmented national demand.
Innovation Focus Network adequacy analytics, continuous credentialing monitoring, and API-based interoperability dominate current innovation pipelines across leading suppliers.
M&A Activity Selective consolidation through platform acquisition, exemplified by Medallion's acquisition of CredSimple and continued credentialing and provider data platform consolidation among health IT vendors.

How Do Companies Compete in the Healthcare Provider Network Management Market?

Companies compete primarily on platform breadth, analytics depth, and payer relationship scale across the Industry. Established vendors such as Quest Analytics and symplr leverage deep health plan compliance relationships to serve mature North American markets, while diversified health IT majors such as IQVIA and UnitedHealth Group compete on cross-portfolio integration with broader claims and care management systems.

Which Competitive Archetypes Dominate the Healthcare Provider Network Management Market?

Two archetypes dominate the market: established provider network management specialists with deep regulatory compliance expertise, and diversified healthcare technology majors offering provider network capabilities as part of broader payer administration portfolios. Quest Analytics and symplr exemplify the specialist archetype, while IQVIA and UnitedHealth Group exemplify the diversified healthcare technology archetype.

How Are Companies Differentiating Through Innovation in Provider Network Management?

Innovation and differentiation strategy increasingly center on network adequacy analytics precision and continuous credentialing monitoring. Kyruus Health's provider search and scheduling integration and Medallion's automated primary source verification both demonstrate how vendors differentiate through certified compliance accuracy and reduced onboarding cycle times. Our analysis shows that suppliers unable to demonstrate credible regulatory compliance risk exclusion from health plan procurement shortlists.

What M&A and Expansion Activity Is Shaping the Healthcare Provider Network Management Market?

Strategic acquisitions, platform integration, and geographic expansion continue to consolidate capabilities within the Industry. Medallion's acquisition of CredSimple and Cotiviti's continued provider data and payment integrity platform consolidation illustrate how specialized vendors pursue rapid capability scaling through consolidated credentialing and analytics ownership.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping platform innovation, regulatory compliance capability, and geographic expansion within the global healthcare provider network management market.

Quest Analytics, LLC symplr LLC Kyruus Health, Inc. Medallion, Inc. HealthEdge Software, Inc. Zelis Healthcare, LLC MacroHealth, Inc. Virsys12, LLC Infosys Limited HealthStream, Inc. Availity, LLC Verisys Corporation IQVIA Holdings Inc. Cotiviti, Inc. UnitedHealth Group Incorporated CAQH NantHealth, Inc. Edifecs, Inc. Inovalon, Inc. Waystar Holding Corp.

Latest Developments

We found that recent product developments within the healthcare provider network management market are concentrated on analytics platform launches and credentialing automation upgrades, reflecting the industry's broader compliance-driven transition.

Date Event
Sept. 2026 Medallion acquired Andros, an NCQA-certified credentials verification organization. The transaction brings more than one million providers across nearly 400 healthcare organizations and health plans onto one credentialing platform, combining credentialing, enrollment, licensing, and provider data management capabilities.
May, 2026 Quest Analytics introduced Quinn, a conversational AI assistant within Quest Enterprise Services. The capability enables users to query provider data, access information on providers and access points, review gap-closure activity, and understand provider-level impacts on network adequacy for faster network planning and analysis.

Investment Opportunities

What Capital Inflows Are Targeting the Healthcare Provider Network Management Market?

Capital inflows into the healthcare provider network management market are increasingly directed toward analytics platform development and credentialing automation. We observed that strategic investors continue to fund platform consolidation, as seen in Medallion's acquisition of CredSimple to expand automated verification capability. Investors favor vendors demonstrating validated regulatory compliance credentials, viewing health plan retention rates as a proxy for long-term market access.

How Is Infrastructure Investment Supporting Healthcare Provider Network Management Deployment?

Infrastructure investment is expanding cloud hosting and data integration capacity to serve rising health plan and government program demand. Our findings suggest that vendors are scaling API integration frameworks to improve interoperability with core administration and claims systems across North American and Asia-Pacific markets.

What ESG Considerations Are Shaping Healthcare Provider Network Management Investment Decisions?

Environmental, social, and governance considerations are increasingly central to investment decisions across the industry, with data privacy compliance and equitable network access as key criteria. We found that investors increasingly favor vendors demonstrating measurable improvements in network adequacy for underserved populations, treating it as a governance indicator alongside data security compliance.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and vendor-selection decisions across the healthcare provider network management Industry. Our analysis shows that detailed component, application, and end user breakdowns help procurement teams align specifications with regulatory compliance requirements while identifying underserved organization size and deployment segments for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the healthcare provider network management supply chain. We observed that the report's regional and segment-level growth differentials help identify which vendors are best positioned to capture above-market growth in analytics and Asia-Pacific categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including continuous credentialing monitoring and network adequacy analytics, that are reshaping the industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around regulatory compliance automation increasingly required by health plan and government program procurement processes.

Key Market Segments Evaluated

By Component

  • Software
  • Services

By Deployment Mode

  • Cloud
  • On-Premise

By Application

  • Provider Data Management
  • Credentialing and Primary Source Verification
  • Network Adequacy Analytics
  • Provider Directory Management
  • Contracting and Fee Schedule Management
  • Other Application

By End User

  • Health Plans and Payers
  • Provider Organizations and Health Systems
  • Third-Party Administrators
  • Government Health Programs
  • Other End User

By Organization Size

  • Large Enterprises
  • Small and Medium Enterprises

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico.
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe.
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC.
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA.
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM.

Conclusion & Recommendations

The long-term outlook for the healthcare provider network management market remains highly positive, supported by a USD 31.50 billion absolute dollar opportunity between 2026 and 2035 and sustained regulatory compliance momentum. NMSC's analysis indicates that vendors combining network adequacy analytics with continuous credentialing monitoring will be best positioned to capture the market's projected growth from USD 9.70 billion in 2026 to USD 41.20 billion by 2035.

What Strategic Positioning Should Suppliers Pursue in the Healthcare Provider Network Management Market?

Suppliers should prioritize regulatory compliance automation to secure long-term access to health plan and government program procurement channels. Our assessment indicates that vendors investing early in cloud-native architecture and API-based interoperability, alongside expanded services capacity, will be best positioned to capture premium pricing within the healthcare provider network management market as compliance scrutiny intensifies.

How Attractive Is the Healthcare Provider Network Management Market for New Investment?

The healthcare provider network management Industry presents a highly attractive investment case, supported by a USD 31.50 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and government health program categories. We found that investment attractiveness is highest for vendors combining validated regulatory compliance with scaled cloud infrastructure, positioning them to serve both mature North American and emerging Asia-Pacific segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor legacy system integration cost, data privacy compliance burden, and competitive pressure from diversified core administration platform incumbents as key risks to the healthcare provider network management market. Our analysis shows that vendors unable to demonstrate seamless interoperability risk losing market access to competitors with certified, pre-integrated platforms, particularly within increasingly consolidated North American health plan markets.

What Are the Key Growth Pathways for the Healthcare Provider Network Management Market?

Key growth pathways include expanding network adequacy analytics and continuous monitoring portfolios, scaling government health program digitization contracts, and deepening penetration into Asia-Pacific health insurance markets. NMSC's analysis indicates that vendors pursuing these pathways while maintaining cost competitiveness in standard credentialing modules will be best positioned to capture the healthcare provider network management market's projected growth through 2035.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖