Metaverse in Healthcare Market Size, Share, Growth Trends and Segmentation Analysis, By Offering (Software, Content, Devices and Peripherals, Services), By Technology, By Application, By Revenue Model, By End-User, By Sales Channel, and By Region — Global Industry Report and Forecast, 2026–2035
Industry: Healthcare | Publishing Date: October 28, 2025 | Last Updated: August 18, 2026 | No of Pages: N/A | No. of Tables: N/A | No. of Figures: N/A | Format: PDF | Report Code: HC3630
What Is the Metaverse in Healthcare Market Size?
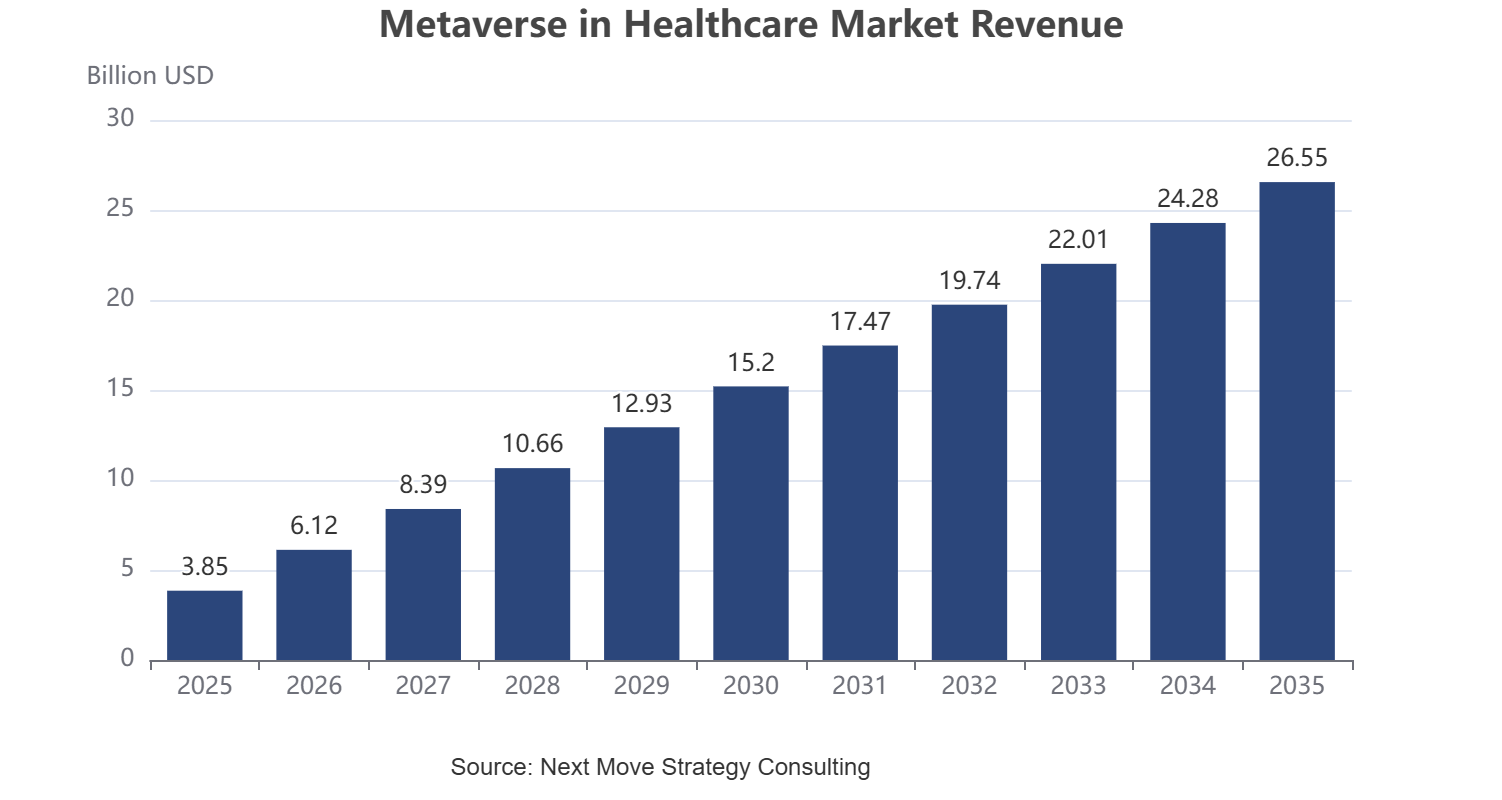
The global Metaverse in Healthcare Market size was valued at USD 3.85 billion in 2025 and is estimated at USD 4.67 billion in 2026, forecast to reach USD 26.55 billion by 2035, expanding at a 21.3% CAGR between 2026 and 2035. North America leads with approximately a 43% share, while Devices and Peripherals dominate all other offerings with approximately a 38% share.
We observed that growth is broad-based across every segmentation axis, with digital twin adoption and spatial computing integration driving the dominant structural shifts through 2035.
|
Key Takeaways |
|
By Offering: Devices and Peripherals held the largest share of approximately 38% (USD 1.46 Billion) in 2025; Services is the fastest-growing sub-segment at 23.6% CAGR from 2026-2035. |
|
By Technology: VR held the largest share of approximately 38% (USD 1.46 Billion) in 2025; Digital Twin is the fastest-growing sub-segment at 26.8% CAGR from 2026-2035. |
|
By Application: Medical Education and Training held the largest share of approximately 28% (USD 1.08 Billion) in 2025; Facility Planning is the fastest-growing sub-segment at 24.0% CAGR from 2026-2035. |
|
By End-User: Healthcare Providers held the largest share of approximately 54% (USD 2.08 Billion) in 2025; Patients and Caregivers is the fastest-growing sub-segment at 24.3% CAGR from 2026-2035. |
|
Dominant Region: North America dominated with approximately 43% revenue share (USD 1.66 Billion) in 2025. |
|
Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 25.4% during 2026-2035. |
|
Dominant Country: The U.S. led with approximately USD 1.03 Billion in 2025. |
|
Fastest-Growing Country: India is the fastest-growing country at approximately 32.2% CAGR from 2026-2035. |
Market Opportunity: The Metaverse in Healthcare Market is expected to create an absolute dollar opportunity of USD 21.88 billion between 2026 and 2035, presenting significant investment potential across digital twin platforms, surgical training simulation, and spatial computing infrastructure.
According to NMSC analysis, hospital systems are increasingly consolidating immersive training, surgical planning, and patient engagement tools onto unified platform software rather than deploying disconnected point solutions, a shift that favors vendors with broad software and content portfolios over single-application developers as health systems scale metaverse deployment across departments through 2035.
Ecosystem Analysis of the Metaverse in Healthcare Industry
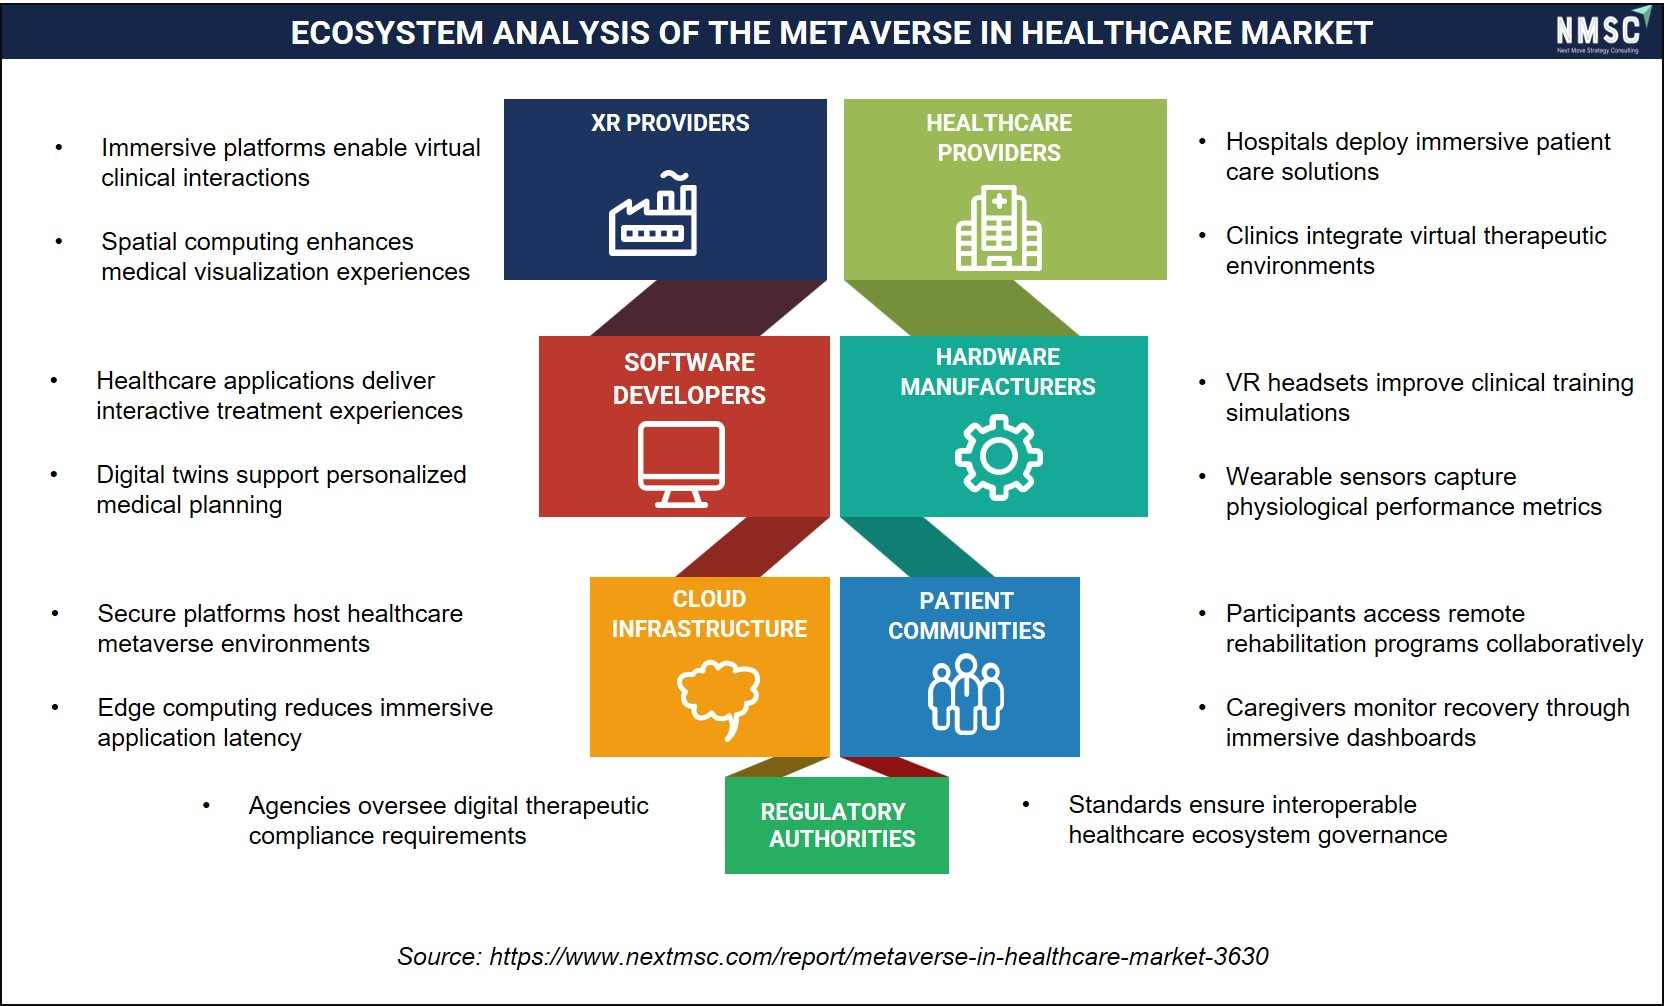
The above infographic presents an ecosystem analysis of the metaverse in healthcare market, covering XR providers, software developers, hardware manufacturers, cloud infrastructure, patient communities, healthcare providers, and regulatory authorities. Virtual reality headsets and wearable sensors support clinical training, personalized planning, and performance monitoring, while secure platforms host immersive therapeutic environments. Edge computing reduces latency for remote rehabilitation and recovery tracking, and regulatory oversight ensures compliance with digital therapeutic standards. Looking ahead, we observed that collaboration across stakeholders and adherence to interoperability standards will remain essential for the continued evolution of healthcare metaverse applications.
What does the Metaverse in Healthcare Market Encompass?
The Metaverse in Healthcare Market encompasses platform software, immersive content, devices and peripherals, and implementation services that enable virtual, augmented, and mixed reality applications across clinical training, surgical planning, and patient engagement. We observed that the scope spans digital twin simulation, spatial computing, and haptic feedback technologies deployed across hospitals, medical schools, and life sciences organizations, evolving from standalone simulation tools into interconnected, persistent virtual care and training environments.
Regulatory frameworks such as the U.S. Food and Drug Administration's guidance on software as a medical device and the European Union's Medical Device Regulation shape approval pathways for therapeutic and diagnostic immersive applications. Our assessment indicates that technology adoption is shifting toward spatial computing and digital twin-based facility planning, with vendors increasingly bundling hardware, content libraries, and managed services into unified deployment packages to support health system-wide immersive technology rollouts.
|
Parameters |
Details |
|
Market Size in 2025 |
USD 3.85 Billion |
|
Market Size in 2026 |
USD 4.67 Billion |
|
Revenue Forecast in 2035 |
USD 26.55 Billion |
|
Growth Rate |
CAGR of 21.3% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
USD Billion |
|
Companies Profiled |
20 |
|
Countries Covered |
38 |
|
Market Share |
Available for Top 10 Companies |
Key Emerging Trends
Based on research conducted by NMSC, we found that four structural trends are reshaping platform design, technology adoption, and stakeholder engagement across the industry.
How Is Digital Twin Technology Transforming Surgical Planning?
Digital twin models of patient anatomy are replacing static imaging review for complex preoperative planning cases. We observed that Siemens Healthineers AG has expanded digital twin capability integrated with its medical imaging portfolio, letting surgeons rehearse procedures on patient-specific virtual models before entering the operating room, reducing intraoperative uncertainty for complex cases.
Why Is Immersive Surgical Training Gaining Momentum in Medical Education?
Immersive surgical training platforms are gaining momentum as medical schools and hospital systems seek scalable alternatives to cadaver-based and apprenticeship training models. We found that Osso VR, Inc. has expanded its virtual reality surgical training library across multiple specialties, positioning immersive simulation as a structural complement to traditional residency training for skill acquisition and assessment.
How Are Spatial Computing Platforms Reshaping Clinical Collaboration in the Metaverse in Healthcare Market?
Spatial computing platforms are compressing the gap between remote specialist consultation and in-person multidisciplinary review. During our market evaluation, we noticed that mixed reality headset integration with hospital imaging systems is improving remote proctoring capability, with Microsoft Corporation expanding HoloLens-based clinical collaboration tools for multidisciplinary case review.
What Role Is Virtual Reality Playing in Pain Management and Rehabilitation?
Virtual reality-based pain management and physical rehabilitation applications are extending beyond pilot programs into reimbursed clinical pathways. Our findings suggest that AppliedVR, Inc. has expanded FDA-cleared virtual reality therapeutics for chronic pain management, positioning prescription-grade immersive therapy as a growing category within the broader therapeutics and rehabilitation application segment.
Growth Drivers and Restraints
Growth Catalyst and Risk Assessment Matrix
|
Factors |
Type |
(+/-) % Impact on CAGR |
Geographic Relevance |
Impact Timeline |
|
Rising adoption of immersive surgical training platforms |
Driver |
+4.2% |
Global |
2026–2035 |
|
Growing digital twin adoption for surgical planning and facility design |
Driver |
+3.6% |
North America, Europe |
2026–2035 |
|
Expansion of spatial computing hardware capability |
Driver |
+3.1% |
Global |
2026–2033 |
|
Rising healthcare digitization investment in Asia-Pacific |
Driver |
+3.4% |
Asia-Pacific |
2026–2035 |
|
Growth of reimbursed VR-based therapeutics |
Driver |
+2.2% |
North America, Europe |
2026–2032 |
|
High upfront hardware and implementation costs |
Restraint |
-2.0% |
Global |
2026–2030 |
|
Limited clinical evidence for some emerging applications |
Restraint |
-1.6% |
Global |
2026–2031 |
|
Data privacy and interoperability concerns with health systems |
Restraint |
-1.4% |
North America, Europe |
2026–2031 |
|
Shortage of clinical staff trained in immersive technology use |
Restraint |
-1.1% |
Global |
2026–2030 |
What Is the Primary Growth Driver for the Metaverse in Healthcare Market?
The primary growth driver is rising adoption of immersive surgical training platforms, which is expanding use cases well beyond early pilot deployments into standard residency curricula. We observed that the U.S. Health Resources and Services Administration has documented growing emphasis on simulation-based competency assessment in medical education since 2024, reinforcing demand for platforms capable of supporting standardized, scalable surgical skill training.
How Is Digital Twin Adoption Driving Metaverse in Healthcare Market Growth?
Digital twin adoption is driving market growth as health systems apply patient-specific and facility-level virtual models to both clinical and operational planning. Based on research conducted by NMSC, we found that hospitals increasingly rely on digital twin for construction -adjacent workflow simulation to optimize facility layouts before construction, a shift expanding the addressable market for digital twin content beyond direct patient care applications.
What Is Restraining the Metaverse in Healthcare Market?
High upfront hardware and implementation costs restrain adoption pace, particularly for smaller hospital systems lacking dedicated capital budgets for immersive technology programs. The U.S. Centers for Medicare and Medicaid Services has not established standardized reimbursement codes for most immersive training and planning applications as of 2024, complicating return-on-investment justification. Our analysis shows that vendors offering managed services and leasing models face growing demand as health systems seek to offset upfront capital constraints.
Segmentation Analysis
Segment Sizing: By Offering
|
Segment |
2025 (USD) |
2035 (USD) |
CAGR% (2026-2035) |
|
Software |
USD 1.23 Billion |
USD 9.56 Billion |
22.9% |
|
Content |
USD 0.54 Billion |
USD 4.25 Billion |
23.2% |
|
Devices and Peripherals |
USD 1.46 Billion |
USD 7.70 Billion |
17.7% |
|
Services |
USD 0.62 Billion |
USD 5.04 Billion |
23.6% |
|
Total |
USD 3.85 Billion |
USD 26.55 Billion |
21.3% |
Which Offering Dominates the Metaverse in Healthcare Market?
Devices and Peripherals dominate the offering axis, contributing USD 1.46 billion in 2025 and projected to reach USD 7.70 billion by 2035. We found that headsets and haptic devices remain the largest revenue contributor as health systems build out augmented reality and virtual reality headset fleets for training programs, while Services grows fastest as implementation and content production demand scales alongside hardware deployment.
Segment Sizing: By Technology
|
Segment |
2025 (USD) |
2035 (USD) |
CAGR% (2026-2035) |
|
VR |
USD 1.46 Billion |
USD 7.96 Billion |
18.2% |
|
AR |
USD 0.85 Billion |
USD 5.58 Billion |
20.7% |
|
MR |
USD 0.54 Billion |
USD 3.72 Billion |
21.4% |
|
Spatial Computing |
USD 0.46 Billion |
USD 4.25 Billion |
25.3% |
|
Digital Twin |
USD 0.39 Billion |
USD 3.98 Billion |
26.8% |
|
Other Immersive Technologies |
USD 0.15 Billion |
USD 1.06 Billion |
21.0% |
|
Total |
USD 3.85 Billion |
USD 26.55 Billion |
21.3% |
Which Technology Is Growing Fastest in the Metaverse in Healthcare Market?
VR remains the largest technology category at USD 1.46 billion in 2025, while Digital Twin is the fastest-growing at a 26.8% CAGR through 2035. Our findings suggest that expanding spatial computing and digital twin integration is enabling health systems to move beyond isolated training simulations toward persistent, data-connected virtual models of patients and facilities.
Segment Sizing: By End-User
|
Segment |
2025 (USD) |
2035 (USD) |
CAGR% (2026-2035) |
|
Healthcare Providers |
USD 2.08 Billion |
USD 12.74 Billion |
19.7% |
|
Life Sciences |
USD 0.85 Billion |
USD 6.11 Billion |
21.9% |
|
Patients and Caregivers |
USD 0.46 Billion |
USD 3.98 Billion |
24.3% |
|
Payers and Employers |
USD 0.23 Billion |
USD 1.86 Billion |
23.4% |
|
Government and Public Health |
USD 0.15 Billion |
USD 1.33 Billion |
24.1% |
|
Other End-Users |
USD 0.08 Billion |
USD 0.53 Billion |
21.8% |
|
Total |
USD 3.85 Billion |
USD 26.55 Billion |
21.3% |
Why Does the Patients and Caregivers End-User Grow Fastest in the Metaverse in Healthcare Market?
Healthcare Providers lead with USD 2.08 billion in 2025, reflecting the broad base of hospitals and medical schools already deploying immersive training and surgical planning tools. We observed that Patients and Caregivers form the fastest-growing end-user category at a 24.3% CAGR through 2035, as prescribed VR-based rehabilitation and pain management applications extend immersive technology use directly into home and outpatient settings.
Growth Opportunities
Beyond the core drivers outlined above, three forward-looking whitespace opportunities stand out for stakeholders positioning within the metaverse in the healthcare market over the 2026-2035 forecast period.
Can Digital Twin Facility Planning Unlock Value for Health System Capital Projects?
Digital twin-based facility planning presents a whitespace opportunity for health systems designing new or renovated clinical spaces. Vendors that expand workflow simulation and digital twin planning tools stand to capture recurring engagement as hospital administrators prioritize evidence-based layout optimization before committing capital to construction projects.
Where Does Reimbursed VR Therapeutics Create New Demand?
Reimbursed VR-based therapeutics represent an underpenetrated opportunity as payers begin establishing coverage pathways for prescription digital therapeutics. Companies such as AppliedVR, Inc. and XRHealth Ltd. that secure digital healthcare reimbursement codes for pain management and mental health applications can capture recurring revenue from payer-covered patient populations.
How Can Surgical Training Platforms Benefit Emerging Market Medical Schools?
Surgical training platforms create a mechanism to serve medical schools in emerging markets that lack cadaver-based training infrastructure. This category benefits vendors such as SimX, Inc. and Osso VR, Inc., offering scalable, low-infrastructure training content, directly supporting the fast-growing Medical Education and Training application segment across Asia-Pacific and Latin America.
Regional Outlook
|
Region |
2025 (USD) |
2035 (USD) |
CAGR% (2026-2035) |
Key Driver |
|
North America |
USD 1.66 Billion |
USD 10.09 Billion |
19.6% |
Concentration of medical technology innovation and hospital capital investment |
|
Europe |
USD 1.00 Billion |
USD 6.11 Billion |
19.7% |
EU Medical Device Regulation compliance-driven adoption |
|
Asia-Pacific |
USD 0.89 Billion |
USD 8.23 Billion |
25.4% |
Rapid healthcare digitization and medical school expansion |
|
Middle East & Africa |
USD 0.19 Billion |
USD 1.33 Billion |
21.5% |
National healthcare digitization strategy investment |
|
Latin America |
USD 0.11 Billion |
USD 0.79 Billion |
22.2% |
Expanding medical education infrastructure investment |
|
Total |
USD 3.85 Billion |
USD 26.55 Billion |
21.3% |
|
North America Metaverse in Healthcare Market
North America remains the most mature metaverse in the healthcare market, anchored by a dense concentration of medical technology innovation and hospital capital investment capacity. We observed that U.S. Food and Drug Administration guidance on software as a medical device sustains demand for compliant, clinically validated immersive applications. Technology adoption remains advanced, with digital twin and spatial computing widely deployed across large academic medical centers.
Europe Metaverse in Healthcare Market
Europe's market reflects a mature, regulation-intensive landscape shaped by the European Union's Medical Device Regulation, which governs approval pathways for therapeutic immersive applications. Our findings suggest that health systems across Germany, France, and the UK increasingly prioritize digital twin-based surgical planning for complex procedures. Technology adoption favors AR and MR platforms, supported by vendors investing in regulatory consulting infrastructure.
Asia-Pacific Metaverse in Healthcare Market
Asia-Pacific is the fastest-growing metaverse in healthcare market region, propelled by rapid healthcare digitization and medical school infrastructure expansion in China and India. We found that regulatory frameworks remain less harmonized than in Europe, giving vendors flexibility to scale training and content platforms rapidly. Technology adoption is accelerating as regional providers expand localized surgical training content to serve growing medical education demand.
Middle East & Africa Metaverse in Healthcare Market
Middle East & Africa is expanding as regional governments invest in national healthcare digitization strategies tied to economic diversification programs. Our analysis shows that Saudi Arabia and the UAE are attracting metaverse in healthcare investment linked to smart hospital initiatives. Regulatory influence remains moderate, while technology adoption is gradually shifting toward immersive training platforms as regional hubs align with international medical education standards.
Latin America Metaverse in Healthcare Market
Latin America's market is supported by expanding medical education infrastructure investment in Brazil and Argentina and growing hospital interest in digital transformation. We observed that regulatory frameworks are less stringent than in North America or Europe, though multinational vendors operating locally are introducing training-focused platform options. Technology adoption remains centered on VR-based training, with competitive intensity increasing as regional distributors partner with global immersive technology vendors.
U.S. Metaverse in Healthcare Market
Based on our estimates, the U.S. Metaverse in Healthcare Market was valued at approximately USD 1.03 billion in 2025 and is projected to reach USD 5.85 billion by 2035, growing at an 18.7% CAGR. Demand is anchored by a mature academic medical center and medical school base, with high digital twin adoption and strong competitive intensity among domestic and global vendors. Technology penetration favors spatial computing, and strategic outlook favors continued surgical training platform expansion.
Canada Metaverse in Healthcare Market
The market in Canada reached roughly USD 0.40 billion in 2025 and is forecast to hit USD 2.72 billion by 2035 at a 21.3% CAGR. Demand structure mirrors U.S. medical education digitization patterns, while Health Canada regulatory guidance shapes software as a medical device compliance. Technology penetration is rising as hospitals request integrated training and planning platforms, with competitive intensity moderate given reliance on cross-border capacity from U.S.-based vendors.
UK Metaverse in Healthcare Market
The market in the UK market stood at about USD 0.26 billion in 2025, advancing toward USD 1.53 billion by 2035 at a 19.4% CAGR. Demand is driven by established National Health Service-affiliated medical schools navigating post-Brexit medical device approval requirements. Regulatory influence is significant, technology penetration favors AR-based clinical collaboration tools, and competitive intensity remains steady among domestic and European vendors serving UK health systems.
Germany Metaverse in Healthcare Market
Germany's market was valued at near USD 0.28 billion in 2025 and is set to reach USD 1.65 billion by 2035, expanding at a 19.2% CAGR. Demand structure benefits from a strong domestic medical device manufacturing and academic medicine base. Germany's alignment with EU Medical Device Regulation mandates drives regulatory influence, while technology penetration favors digital twin surgical planning among leading vendors headquartered domestically.
France Metaverse in Healthcare Market
As per our estimate, France's market reached approximately USD 0.16 billion in 2025, projected to climb to USD 1.04 billion by 2035 at a 20.8% CAGR. Demand is supported by France's established medical simulation training network, which shapes surgical training and nursing education adoption. Regulatory influence from French health authority modernization is notable, and competitive intensity remains high given the concentration of vendors serving domestic medical schools.
China Metaverse in Healthcare Market
The market in China stood at roughly USD 0.28 billion in 2025 and is forecast to reach USD 2.30 billion by 2035, registering a 23.7% CAGR. Demand is fueled by expanding domestic medical school infrastructure and a dense base of regional immersive technology developers. Regulatory influence is increasing gradually, technology penetration is accelerating through spatial computing upgrades, and competitive intensity remains elevated among vendors expanding local content production capacity.
India Metaverse in Healthcare Market
According to our analysis, India's market was valued at about USD 0.12 billion in 2025, projected to reach USD 1.73 billion by 2035 at a 32.2% CAGR, the fastest among covered countries. Demand structure reflects rapidly expanding medical education capacity and rising adoption of scalable surgical training alternatives to cadaver-based programs. Regulatory influence remains developing, while technology penetration is rising quickly as vendors localize training content to serve India's growing medical school base.
Japan Metaverse in Healthcare Market
Japan's market reached close to USD 0.18 billion in 2025 and is expected to hit USD 1.32 billion by 2035, growing at a 22.7% CAGR. Demand is supported by Japan's advanced medical technology research base, led by domestic providers coordinating closely with global immersive technology vendors. Regulatory influence is well established, technology penetration is advancing, and competitive intensity remains moderate among long-standing domestic and multinational vendors.
South Korea Metaverse in Healthcare Market
Based on our estimates, South Korea's market stood at approximately USD 0.12 billion in 2025, forecast to reach USD 1.15 billion by 2035 at a 26.4% CAGR. Demand structure benefits from the country's advanced electronics and medical device manufacturing base. Technology penetration is high, with domestic providers supplying integrated immersive healthcare platforms, and competitive intensity remains pronounced amid rapid medical education modernization.
Australia Metaverse in Healthcare Market
The metaverse in healthcare market in Australia reached about USD 0.07 billion in 2025 and is projected to reach USD 0.58 billion by 2035, expanding at a 23.0% CAGR. Demand is supported by a well-established medical education network and growing preference for simulation-based clinical training. Regulatory influence stems from Australia's Therapeutic Goods Administration approval framework, while technology penetration favors VR-based training amid moderate competitive intensity.
UAE Metaverse in Healthcare Market
The market in the UAE market was valued at near USD 0.06 billion in 2025, projected to reach USD 0.40 billion by 2035 at a 21.4% CAGR. Demand structure is shaped by the UAE's national smart hospital initiatives and expanding medical education infrastructure. Regulatory influence remains moderate, technology penetration is improving through hospital digitization programs, and competitive intensity is rising as vendors expand Gulf market coverage.
Saudi Arabia Metaverse in Healthcare Market
Saudi Arabia's market reached roughly USD 0.06 billion in 2025 and is expected to hit USD 0.39 billion by 2035, growing at a 21.0% CAGR. Demand is driven by Vision 2030-linked healthcare infrastructure investment and rising medical school digitization activity. Regulatory influence is developing under Saudi Food and Drug Authority modernization guidelines, and technology penetration is advancing as domestic institutions scale immersive training availability.
South Africa Metaverse in Healthcare Market
As per our estimate, South Africa's market stood at about USD 0.03 billion in 2025, forecast to reach USD 0.21 billion by 2035 at a 20.2% CAGR. Demand structure reflects a developing medical education base serving regional Southern African training needs. Regulatory influence remains moderate, technology penetration is gradually improving, and competitive intensity is limited given reliance on established international immersive technology vendors.
Brazil Metaverse in Healthcare Market
The market in Brazil reached approximately USD 0.05 billion in 2025 and is projected to reach USD 0.33 billion by 2035, registering a 20.9% CAGR. Demand is underpinned by Brazil's large domestic medical education system and expanding hospital digitization investment. Regulatory influence stems from Brazilian health regulatory modernization initiatives, technology penetration favors VR-based surgical training, and competitive intensity remains moderate among regional vendors.
Argentina Metaverse in Healthcare Market
According to our analysis, Argentina's market was valued at near USD 0.02 billion in 2025, projected to reach USD 0.19 billion by 2035 at a 22.8% CAGR. Demand structure is supported by steady medical education modernization despite macroeconomic volatility. Regulatory influence remains limited, technology penetration is modest, and competitive intensity is centered on a small number of regional distributors serving domestic medical schools.
Regulatory Framework Impacting the Metaverse in Healthcare Industry
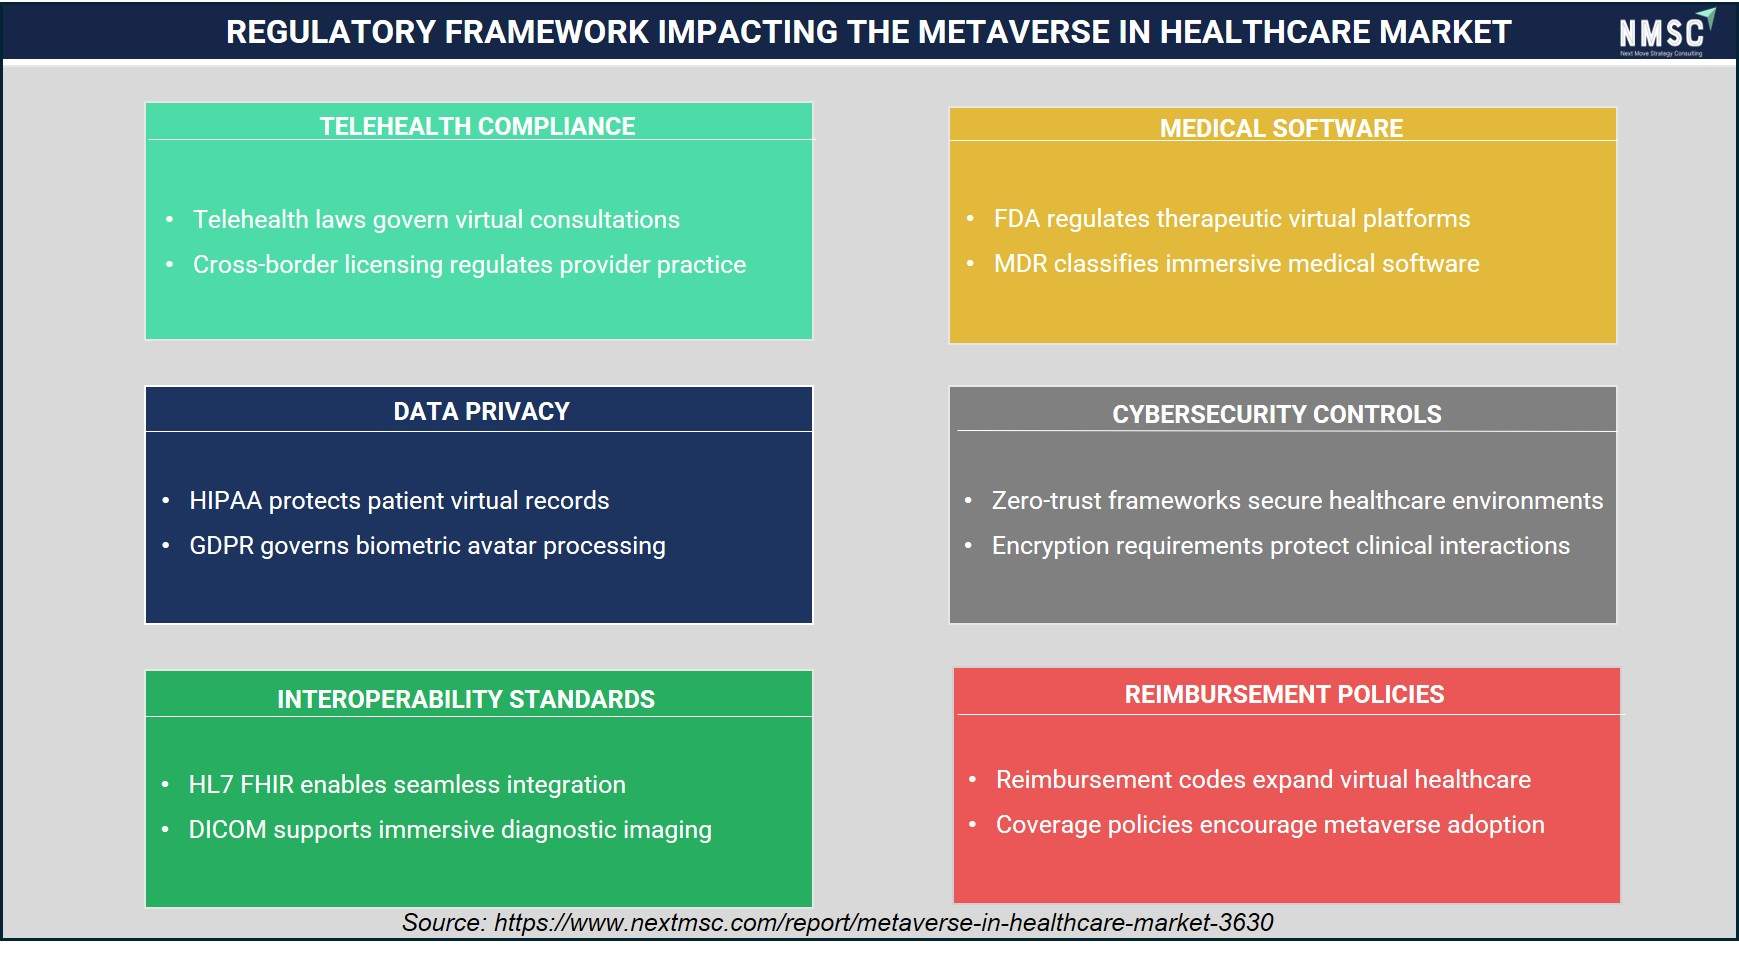
The above infographic presents a regulatory framework impacting the metaverse in healthcare market, wherein telehealth compliance and cross-border licensing are shaping virtual consultation practices. Data privacy is upheld through HIPAA and GDPR, while interoperability standards such as HL7 FHIR and DICOM support seamless integration with diagnostic imaging. The FDA and MDR regulate therapeutic virtual platforms and immersive medical software, while zero-trust frameworks and encryption ensure cybersecurity. Reimbursement policies and coverage codes are further encouraging adoption. Looking ahead, we observed that regulatory evolution will remain instrumental in balancing innovation with patient safety and data protection across the healthcare sector.
Competitive Landscape
We observed that the metaverse in healthcare market features a moderately consolidated competitive landscape, with global technology conglomerates competing alongside specialized immersive healthcare vendors on platform breadth, clinical validation, and pricing flexibility.
|
Dimension |
Description |
|
Market Structure |
Moderately consolidated; the top companies profiled in this report collectively account for a significant share of global metaverse in healthcare revenue, while numerous specialized vendors serve application-specific training and therapeutics demand |
|
Innovation Focus |
Digital twin surgical planning, spatial computing integration, and reimbursed VR therapeutics dominate current innovation pipelines across leading vendors |
|
M&A Activity |
Selective consolidation through specialized platform acquisitions, exemplified by Medtronic plc's continued integration of surgical visualization and planning capabilities |
How Do Companies Compete in the Metaverse in Healthcare Market?
Companies compete primarily on platform breadth, clinical validation depth, and pricing flexibility across health system tiers. We observed that global players such as Microsoft Corporation and NVIDIA Corporation leverage broad spatial computing and simulation infrastructure to serve multinational health system deployments, while specialized vendors such as Osso VR, Inc. compete on clinical content depth and surgical specialty coverage.
Which Competitive Archetypes Dominate the Metaverse in Healthcare Market?
Two archetypes dominate the market: diversified technology conglomerates offering integrated hardware, platform, and content ecosystems, and specialized clinical immersive vendors focused on specific applications such as surgical training or pain management. Meta Platforms, Inc. exemplifies the diversified archetype through integrated headset and platform capability, while SimX, Inc. exemplifies the specialized clinical simulation archetype serving medical education demand.
How Are Companies Differentiating Through Innovation?
Innovation and differentiation strategy increasingly center on clinical outcome validation and surgical robotics integration for procedural training accuracy. Intuitive Surgical, Inc. and Brainlab AG have both expanded immersive surgical planning capability to secure hospital system contracts, while vendors unable to demonstrate peer-reviewed clinical evidence risk exclusion from academic medical center procurement.
What M&A and Expansion Activity Is Shaping the Metaverse in Healthcare Market?
Mergers, acquisitions, and geographic expansion continue to consolidate metaverse in healthcare capabilities within the industry. Medtronic plc's ongoing integration of surgical visualization platforms broadened its immersive planning capability, while GE HealthCare Technologies Inc.'s continued investment in digital twin imaging integration illustrates how diversified companies pursue geographic expansion and platform breadth across clinical application segments.
Key Market Players
We observed that the following twenty companies represent the core competitive set shaping platform innovation, geographic expansion, and pricing strategy across the Metaverse in Healthcare Market.
-
Microsoft Corporation
-
NVIDIA Corporation
-
Siemens Healthineers AG
-
GE HealthCare Technologies Inc.
-
Medtronic plc
-
Koninklijke Philips N.V.
-
Meta Platforms, Inc.
-
Johnson & Johnson
-
Intuitive Surgical, Inc.
-
Brainlab AG
-
Laerdal Medical AS
-
Elevate Healthcare
-
SimX, Inc.
-
Osso VR, Inc.
-
XRHealth Ltd.
-
AppliedVR, Inc.
-
FundamentalVR Ltd.
-
Medivis Inc.
-
Augmedics Inc.
-
Novarad Corporation
Latest Developments
We found that recent product and partnership announcements underscore accelerating vendor investment in digital twin and surgical training capability.
|
Date |
Event |
|
November 2025 |
Siemens Healthineers unveiled new AI-enabled radiology services together with ActExcell Operational Twin, which uses digital simulation to model hospital operations and optimize workflows. |
|
March 2025 |
NVIDIA and GE HealthCare announced an expanded collaboration to develop autonomous X-ray and ultrasound systems using the NVIDIA Isaac for Healthcare platform. The partnership leverages physics-based digital simulation, virtual environments, and AI to train and validate medical imaging systems before deployment |
Expert Insights
 “Artificial intelligence and physical AI offer an incredible opportunity to expand global access to GE HealthCare's advanced imaging systems. Working together to train and test autonomous solutions, we will accelerate the future of medical imaging capabilities, starting with the two most widely used modalities: X-ray and ultrasound.”
— Kimberly Powell, Vice President of Healthcare, NVIDIA Corporation
Statement made during the GE HealthCare and NVIDIA Reimagine Diagnostic Imaging with Autonomous X-ray and Ultrasound Solutions.
Market Interpretation
Kimberly Powell's statement underscores the growing convergence of physical AI, digital simulation, and autonomous medical imaging, which are foundational technologies supporting the evolution of the Metaverse in Healthcare Market. By leveraging virtual environments to train, test, and validate imaging systems before real-world deployment, the collaboration advances immersive healthcare ecosystems, digital twin applications, and AI-enabled clinical workflows. These developments are expected to accelerate the adoption of connected, simulation-driven healthcare platforms, strengthening the market's long-term growth trajectory.
Investment Opportunities
Where Are Capital Inflows Concentrated in the Metaverse in Healthcare Market?
Capital inflows are concentrated in digital twin platform developers and reimbursed VR therapeutics companies, with strategic acquirers targeting firms offering proprietary clinical content and regulatory clearance. Our analysis shows that established vendors are increasingly funding internal spatial computing development, reflecting confidence in the segment's 21.3% CAGR through 2035 as a durable, fundamentals-supported growth trajectory.
How Significant Is Infrastructure Investment Supporting Metaverse in Healthcare Market Growth?
Infrastructure investment supporting spatial computing and augmented reality cloud capacity underpins the market's Digital Twin and Asia-Pacific growth, projected at a 26.8% and 25.4% CAGR, respectively, through 2035. We observed that hospital digitization infrastructure expansion across North America and Asia-Pacific is directly enabling faster adoption of connected immersive healthcare platforms.
What ESG Considerations Are Shaping Investment Decisions?
Environmental, Social, and Governance considerations increasingly factor into health system and investor decisions, as immersive training reduces reliance on cadaver-based programs and associated resource consumption. Our assessment indicates that investors favor vendors demonstrating measurable improvements in training accessibility for underserved medical education markets, aligning metaverse in healthcare adoption with broader corporate social responsibility reporting requirements.
Key Benefits for Stakeholders
How Does This Report Benefit Enterprise and Industry Leaders?
Enterprise and industry leaders gain access to segment-level revenue forecasts across offering, technology, and application axes, enabling informed prioritization of internal immersive technology investment and vendor selection decisions. Our analysis shows that benchmarking against the 21.3% market CAGR through 2035 helps healthcare technology leaders justify budget allocation relative to peers, while regional data supports deployment and procurement decisions.
How Does This Report Benefit Investors and Financial Analysts?
Investors and financial analysts benefit from reconciled market sizing across twenty companies and thirty-eight countries, supporting due diligence on competitive positioning and growth trajectory. NMSC's analysis indicates that the report's segment-level CAGR data, including the 26.8% growth rate for Digital Twin technology, helps identify underappreciated growth pockets ahead of broader market recognition.
How Does This Report Benefit Technology Vendors and Product Teams?
Technology vendors and product teams gain visibility into which offerings and applications are growing fastest, directly informing product roadmap and go-to-market prioritization. Our findings suggest that the report's competitive landscape and latest developments sections help product teams benchmark feature investment against direct competitors, reducing the risk of misallocating R&D spend toward slower-growing segments.
Key Market Segments
By Offering
-
Software
-
Platform Software
-
Applications Software
-
-
Content
-
Anatomy Content
-
Scenario Library
-
Digital Twin Content
-
Other Content
-
-
Devices and Peripherals
-
Headsets
-
Haptics
-
Cameras and Sensors
-
Tracking Systems
-
Compute and Accessories
-
-
Services
-
Implementation and Integration
-
Custom Development
-
Content Production
-
Support and Managed Services
-
By Technology
-
VR
-
AR
-
MR
-
Spatial Computing
-
Digital Twin
-
Other Immersive Technologies
By Application
-
Medical Education and Training
-
Surgical Training
-
Nursing Training
-
EMS Training
-
Other Clinical Training
-
-
Surgical Planning and Guidance
-
Preoperative Planning
-
Intraoperative Guidance
-
-
Medical Imaging
-
3D Visualization
-
Collaborative Review
-
-
Therapeutics and Rehabilitation
-
Pain Management
-
Mental Health
-
Physical Rehabilitation
-
Other Therapy
-
-
Patient Engagement
-
Education
-
Consent Support
-
-
Clinical Collaboration
-
Remote Proctoring
-
Multidisciplinary Review
-
-
Facility Planning
-
Workflow Simulation
-
Digital Twin Planning
-
-
Research and Clinical Trials
By Revenue Model
-
Subscription
-
License
-
Usage-Based
-
Project-Based Fees
-
Device Sales
-
Equipment Leases
-
Reimbursed Therapy
-
Other Revenue Models
By End-User
-
Healthcare Providers
-
Hospitals and Health Systems
-
Medical Schools
-
Nursing Schools
-
Ambulatory Surgery Centers
-
Diagnostic Centers
-
-
Life Sciences
-
Pharma and Biotech
-
Medtech
-
CROs and Research Institutions
-
-
Patients and Caregivers
-
Payers and Employers
-
Government and Public Health
-
Other End-Users
By Sales Channel
-
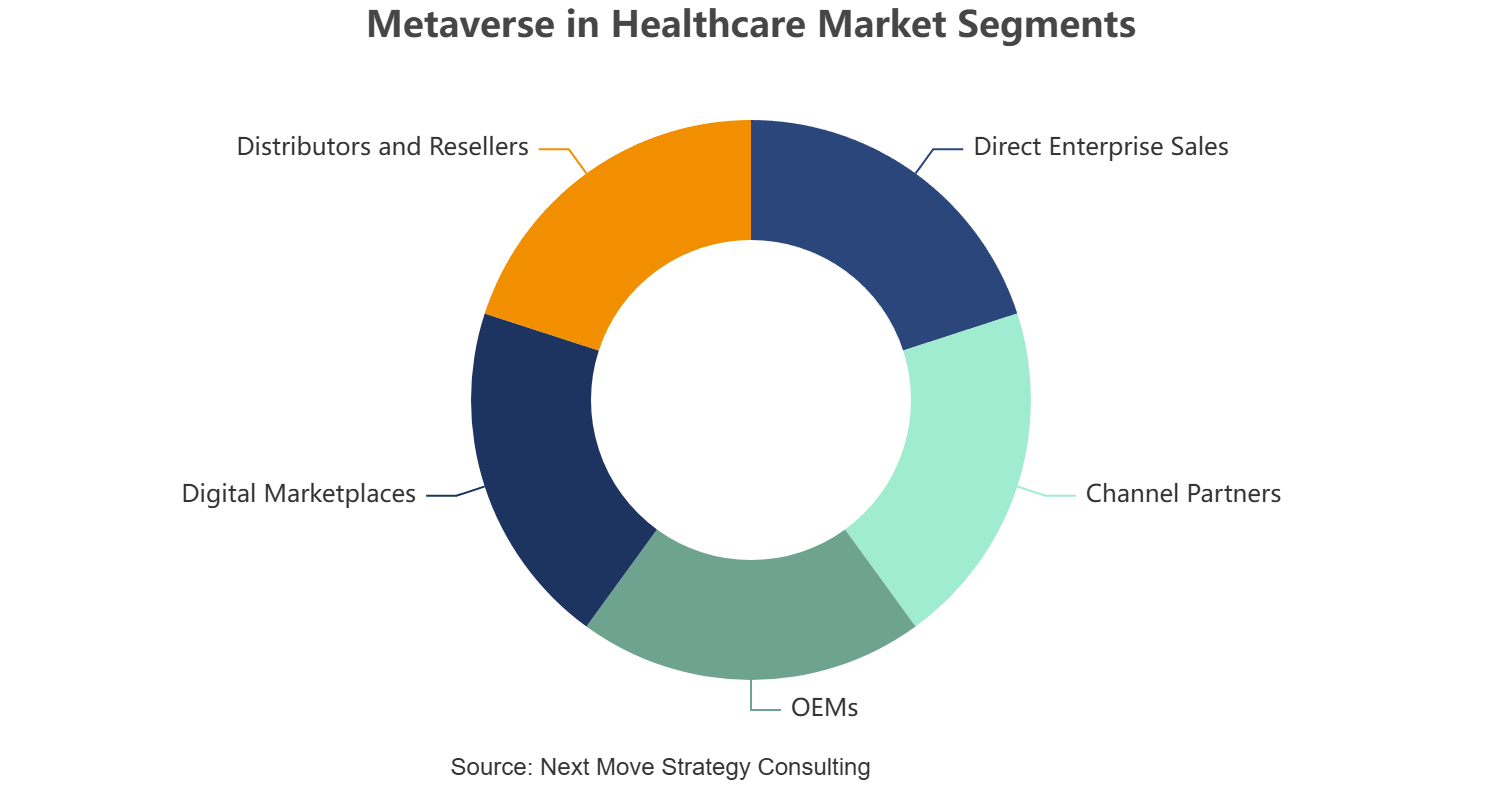
Direct Enterprise Sales
-
Channel Partners
-
OEMs
-
Digital Marketplaces
-
Distributors and Resellers
By Region
-
North America: U.S., Canada, Mexico
-
Europe: UK, Germany, France, Italy, Spain, Sweden, Denmark, Finland, Netherlands, Rest of Europe
-
Asia-Pacific: China, India, Japan, South Korea, Taiwan,Indonesia, Vietnam, Australia, Philippines, Malaysia, Rest of APAC
-
Middle East & Africa: Saudi Arabia, UAE, Egypt, Israel, Turkey, Nigeria, South Africa, Rest of MEA
-
Latin America: Brazil, Argentina, Chile, Colombia, Rest of LATAM
Conclusion and Recommendations
What Is the Long-Term Outlook for the Metaverse in Healthcare Market?
The long-term outlook for the market remains highly positive, with global revenue projected to expand from USD 4.67 billion in 2026 to USD 26.55 billion by 2035 at a 21.3% CAGR. We observed that sustained digital twin adoption, immersive surgical training expansion, and reimbursed VR therapeutics growth will continue underpinning growth across end-user segments through the forecast period.
What Strategic Positioning Should Vendors Pursue?
Vendors should prioritize clinical validation and digital twin capability while pursuing spatial computing integration to secure long-term health system contracts. Our assessment indicates that mid-sized vendors without peer-reviewed clinical evidence face a competitive disadvantage, making strategic alliances with academic medical centers an increasingly important positioning lever heading into the later years of the forecast period.
How Attractive Is the Metaverse in Healthcare Market for New Investment?
The metaverse in healthcare industry presents a highly attractive investment case, supported by a USD 21.88 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and Digital Twin categories. We found that investment attractiveness is highest for vendors combining clinical validation credentials with scaled platform and hardware capacity.
What Market Shifts and Key Risks Should Stakeholders Monitor?
Stakeholders should monitor high upfront hardware costs, limited clinical evidence for emerging applications, and reimbursement uncertainty as key factors shaping the metaverse in the healthcare market. Our analysis shows that vendors unable to demonstrate measurable clinical outcomes risk losing procurement share to competitors with stronger peer-reviewed evidence and established regulatory clearance.
What Are the Key Growth Pathways for the Metaverse in Healthcare Market?
Key growth pathways include expanding Digital Twin and Services portfolios, scaling reimbursed VR therapeutics, and deepening penetration into patient and caregiver-facing rehabilitation channels. NMSC's analysis indicates that vendors pursuing these pathways while maintaining cost competitiveness in standard device categories will be best positioned to capture the market's projected growth through 2035.
About the Author
 Saista Faiyaz
— Bidhudhyoti Nag is a seasoned researcher with over two years of experience, specializing in various industry verticals such as healthcare, construction and manufacturing, automotive & transportation. With a strong passion for writing, he views blogging as a valuable platform to share her industry insights and expertise. Outside of tracking market trends and developments, Bidhudhyoti is interested in sports, travelling, and exploring new experiences.
About the Reviewer
 Supradip Baul
— Supradip Baul is the CEO and Founder of Next Move Strategy Consulting, driving the firm’s mission to provide data-driven insights and strategic intelligence. With extensive experience in market research and consulting, he has helped global organizations make informed decisions and achieve sustainable growth.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

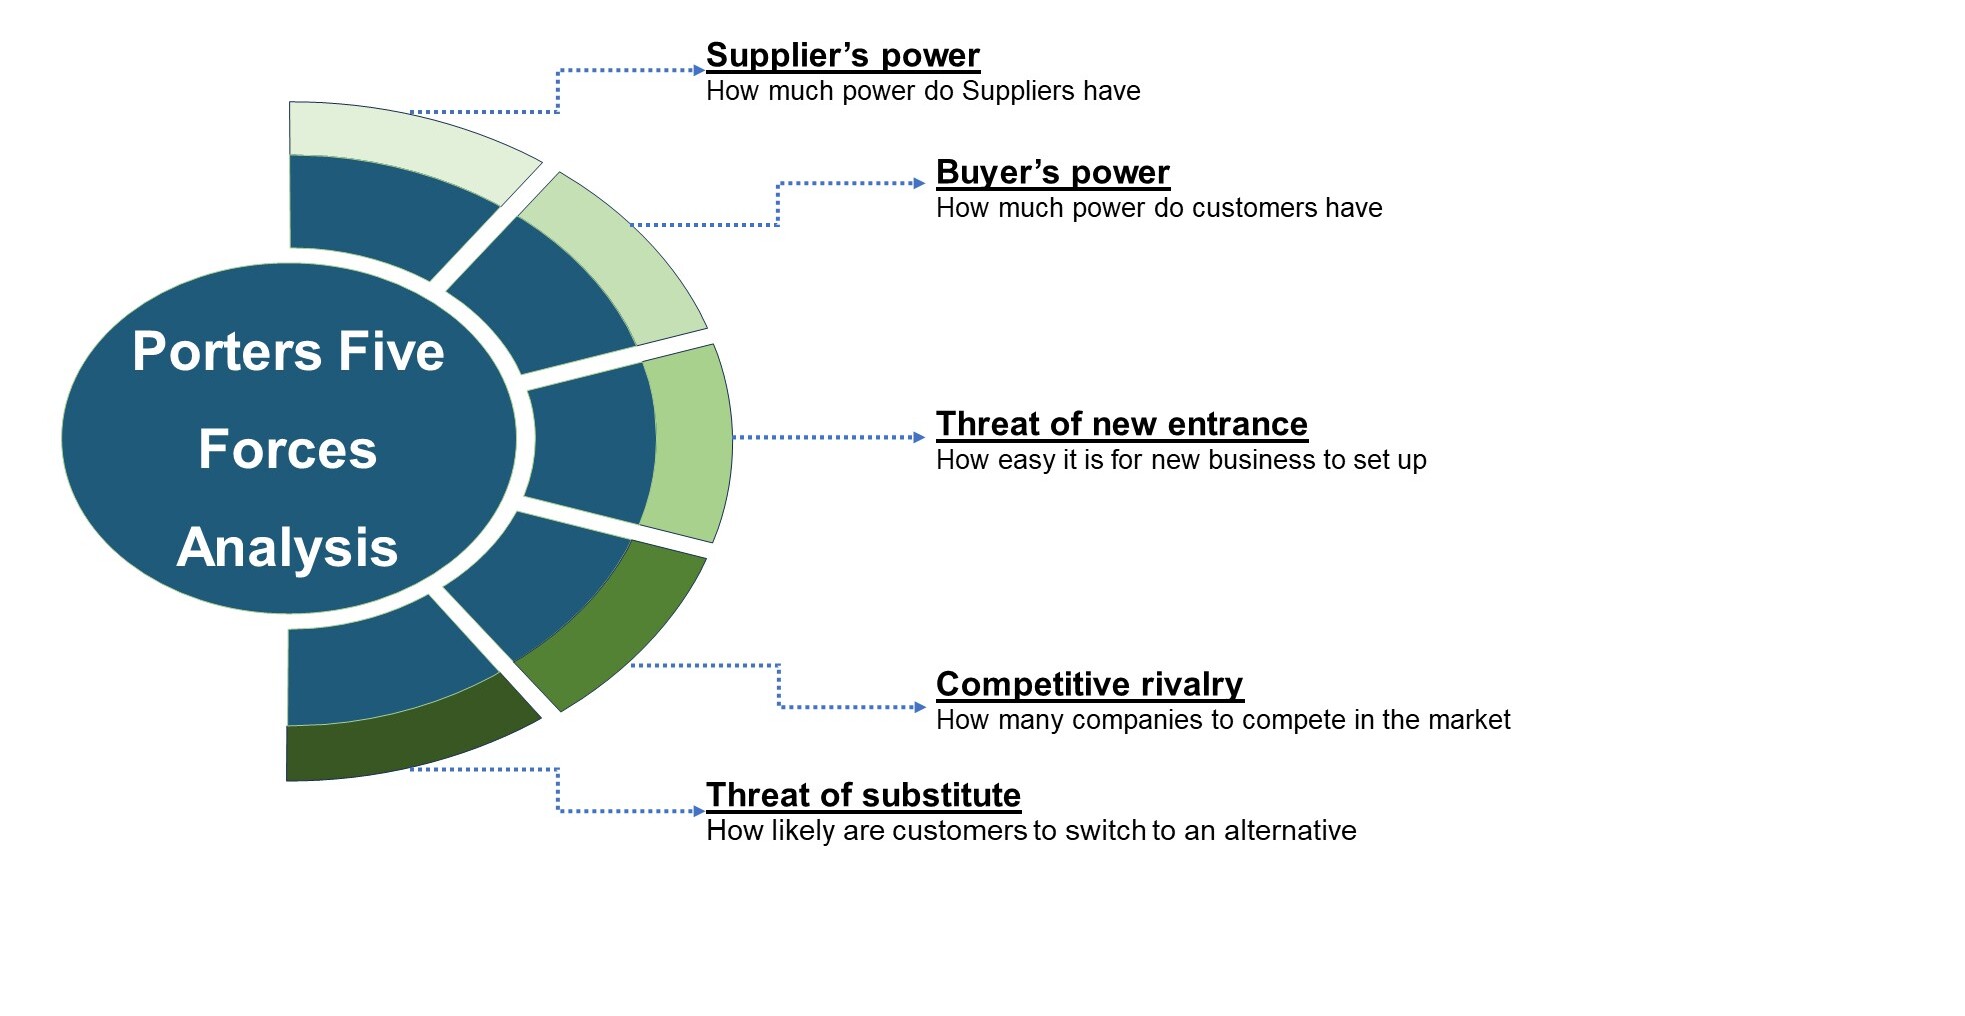
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.



 Speak to Our Analyst