Spain Agriculture Robots Market By Type (Unmanned Aerial Vehicles (UAVs), Milking Robots, Driverless Tractors, Automated Harvest Robots and Others), By Farming Type (Indoor Farming, Outdoor Farming and Indoor & Outdoor), and By Application (Aerial Monitoring & Scouting, Dairy & Livestock Automation, Field Operations, Harvest Management and Others): Opportunity Analysis & Industry Forecast, 2025–2035
Industry: Agriculture | Latest Edition: August 20, 2026 | No of Pages: 179 | No. of Tables: 66 | No. of Figures: 60 | Format: PDF | Report Code: AG562
Market Size & Forecast
|
Parameters |
Details |
|
Market Size in 2025 |
USD 452.52 Million |
|
Market Size in 2026 |
USD 595.93 Million |
|
Revenue Forecast in 2035 |
USD 2,936.43 Million |
|
Growth Rate |
19.39% |
|
Market Volume in 2025 |
4 thousand Units |
|
Market Volume in 2026 |
5 thousand Units |
|
Volume Forecast in 2035 |
41 thousand Units |
|
Growth Rate |
26.12% |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Million (USD) |
|
Companies Profiled |
15 |
|
Market Share |
Available for Top 10 Companies |
Industry Outlook
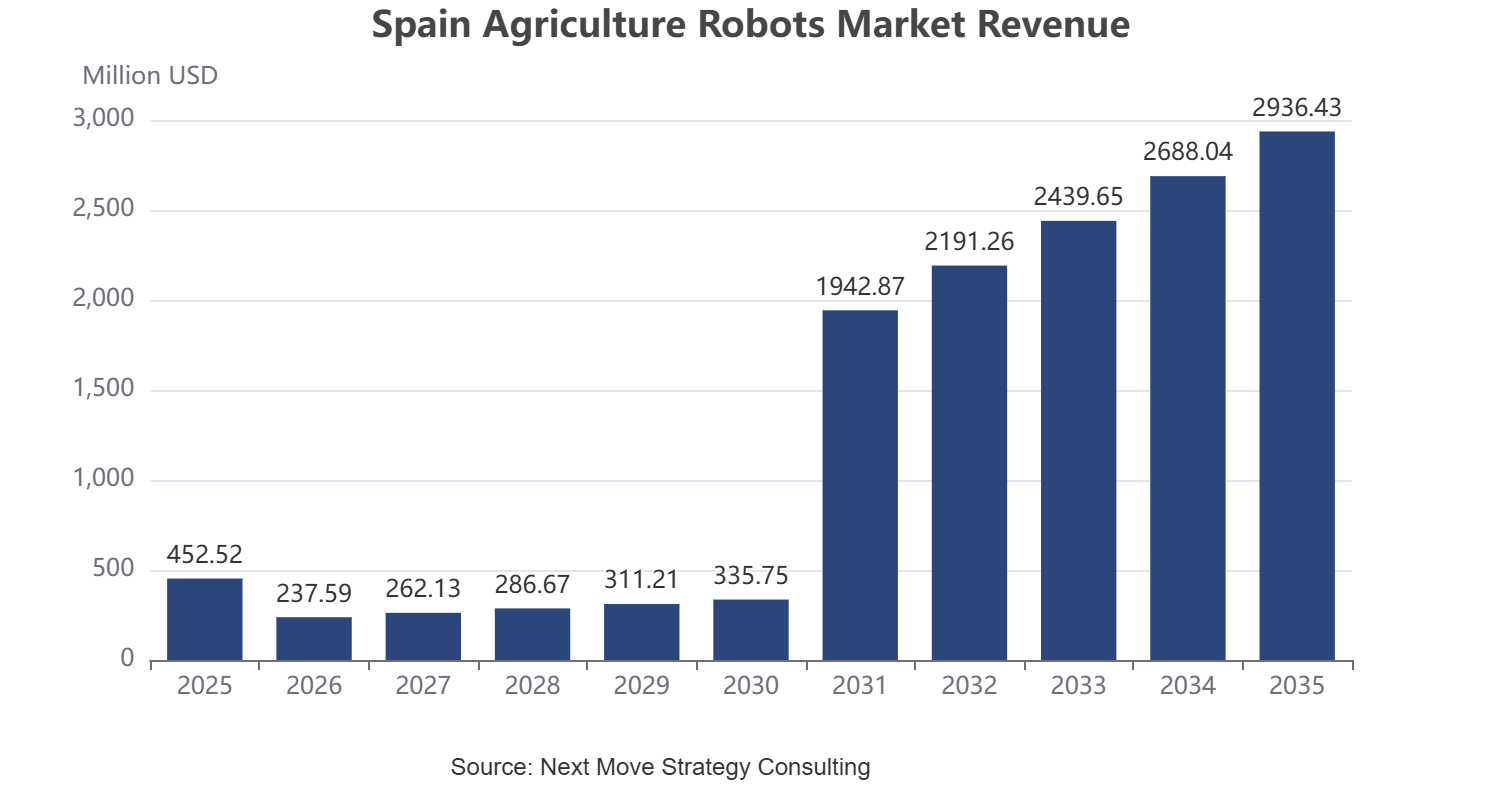
The Spain Agriculture Robots Market was valued at USD 452.52 million in 2025 and is expected to reach USD 595.93 million in 2026. Driven by escalating water scarcity concerns, expanding greenhouse agriculture operations, and increasing labor shortages across Spain’s horticulture sector, the market is projected to reach USD 2,936.43 million by 2035, advancing at a CAGR of 19.39% from 2026 to 2035. In volume terms, the market was estimated at 4 thousand units in 2025 and is projected to increase from 5 thousand units in 2026 to 41 thousand units by 2035, registering a CAGR of 26.12% during the forecast period.
Consumer Behavior Analysis of the Spain Agriculture Robots Market
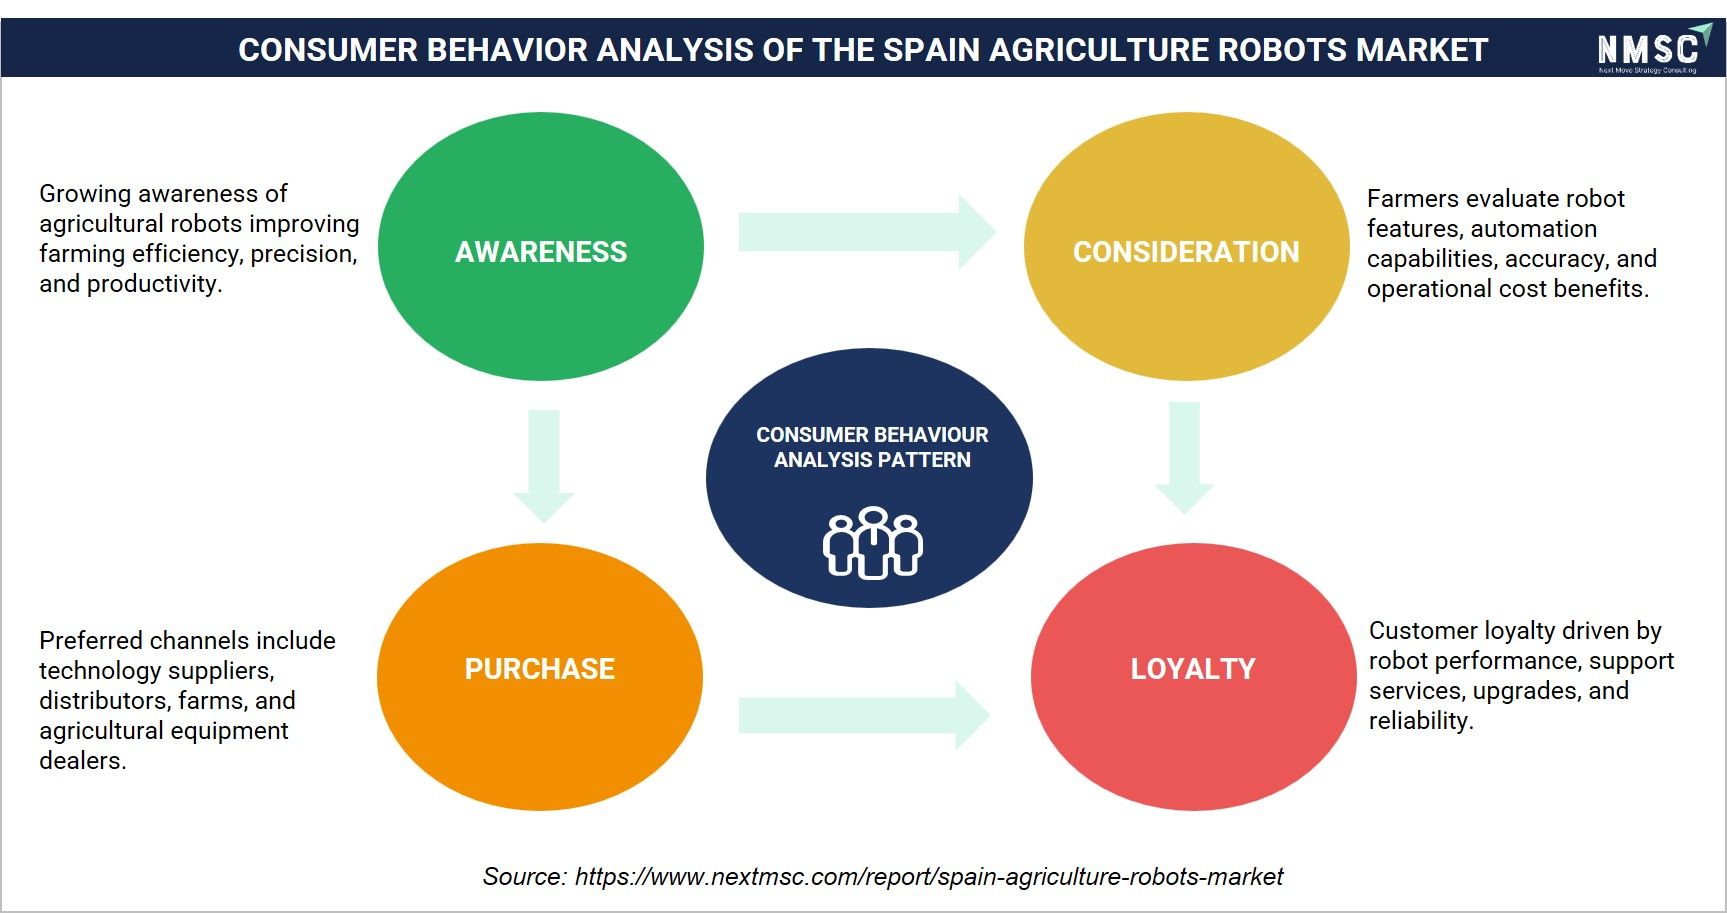
The consumer behavior analysis illustrates how Spanish farmers progress from awareness to long-term loyalty when adopting agricultural robots. Purchasing decisions are primarily influenced by automation capabilities, precision, operational efficiency, and cost-effectiveness, while dealer networks and technology providers remain preferred purchasing channels. Post-purchase satisfaction depends on equipment reliability, technical support, software upgrades, and measurable improvements in farm productivity, reinforcing repeat investments and sustained adoption.
What Are the Key Growth Catalysts, Restraints, and Opportunities Shaping the Spain Agriculture Robots Market?
Growth Catalyst & Risk Assessment Matrix
|
Drivers / Trends / Restraints |
(+/-) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Stringent environmental regulations promoting precision spraying, water conservation, and low-emission farming practices are accelerating the adoption of agricultural robots across Spain. |
2.20% |
Spain |
Short to medium term (1–4 years) |
|
Expansion of greenhouse farming and high-value horticulture production is increasing demand for autonomous harvesting, monitoring, and precision farming robots. |
1.90% |
Spain |
Medium term (2–5 years) |
|
Persistent labor shortages and rising seasonal labor costs are driving investment in robotic harvesting and automated field operations. |
2.10% |
Spain |
Medium to long term (3–7 years) |
|
High upfront investment costs and limited affordability among small and medium-sized farms continue to restrain widespread deployment of advanced agricultural robotic systems. |
-1.50% |
Spain |
Short to medium term (1–4 years) |
|
Rising demand for AI-enabled precision irrigation, greenhouse automation, and crop monitoring solutions presents significant market expansion opportunities. |
1.80% |
Spain |
Medium term (2–5 years) |
The Spain Agriculture Robots Market is influenced by a dynamic set of growth catalysts, restraints, and strategic opportunities. Escalating water scarcity, acute labor shortages in horticulture, and a rapidly expanding greenhouse farming sector are collectively accelerating the adoption of robotic technologies in Spanish agriculture. However, the high capital investment required for deploying advanced robotic systems poses a significant challenge for small and medium-scale farming operations. Rising demand for automation in controlled-environment agriculture simultaneously presents substantial untapped growth opportunities for stakeholders across the entire agricultural technology value chain.
Growth Driver:
How Are Water Scarcity Concerns Driving Adoption of Precision Irrigation and Monitoring Robots in Spain?
Spain faces persistent water scarcity challenges, making efficient water management a critical agricultural priority. Precision irrigation robots equipped with advanced sensors and real-time monitoring systems help farmers optimize water usage while maintaining crop yields. These technologies enable targeted water delivery, soil moisture tracking, and early detection of irrigation inefficiencies. As climate change intensifies drought conditions across Spanish agricultural regions, demand for precision irrigation and monitoring robotic solutions continues to rise, positioning water efficiency technology as a core catalyst for sustained market expansion throughout the forecast period from 2026 to 2035.
How Is the Expanding Greenhouse Agriculture Sector Increasing Demand for Automated Farming Technologies in Spain?
Spain is one of Europe's largest greenhouse agriculture producers, with significant production concentrated in Almería, Murcia, and Valencia. The continued expansion of greenhouse crop production creates substantial demand for automated farming technologies including robotic planting, environmental monitoring, and harvesting systems. Greenhouse environments offer controlled conditions that facilitate seamless robotic integration, enhancing operational efficiency and yield consistency. As greenhouse acreage expands and operators seek greater productivity with reduced labor dependence, deployment of agricultural robots in controlled-environment farming settings is expected to accelerate considerably throughout the forecast period.
How Are Labor Shortages in Horticulture Production Driving Robotic Harvesting Adoption Across Spain?
Spain's horticulture sector faces acute labor shortages, particularly for harvesting operations that traditionally require intensive manual effort. An aging rural population, reduced seasonal migration, and rising labor costs are compelling growers to adopt robotic harvesting solutions. Automated harvest robots equipped with computer vision and precision manipulation systems perform repetitive harvesting tasks with high efficiency and consistency. These solutions are increasingly viable for crops such as strawberries, tomatoes, and peppers, significantly reducing dependence on manual labor and improving overall harvest efficiency across Spanish Spain Agriculture Robots Market throughout the forecast period.
Growth Inhibitor
Why Do Capital-Intensive Robotic Systems Remain a Significant Challenge for Many Spanish Farming Operations?
The high upfront capital investment required to procure, install, and maintain advanced agricultural robotic systems represents a significant barrier to widespread adoption across Spain. Many small and medium-sized farming operations lack the financial resources necessary to integrate robotic technologies, limiting market penetration beyond large-scale commercial farms. Ongoing maintenance requirements, technical expertise needs, and limited access to specialized financing solutions further compound affordability challenges. Without targeted government subsidies or accessible financing programs, capital cost constraints are expected to moderately restrain market growth throughout the forecast period from 2026 to 2035.
Growth Opportunity
What Growth Opportunities Do Automation Solutions for Greenhouse Crop Production Present in the Spain Agriculture Robots Market?
The rapid expansion of Spain's greenhouse farming sector presents significant growth opportunities for agricultural automation solution providers. Greenhouse environments, characterized by controlled conditions and high crop density, are particularly suited for robotic integration across planting, monitoring, pest management, and harvesting operations. As growers seek to improve production efficiency and reduce labor dependency, demand for specialized greenhouse automation solutions is expected to surge. Companies offering scalable, cost-effective robotic platforms tailored for greenhouse applications are well-positioned to capture substantial market share within Spain's thriving controlled-environment agriculture segment.
How Is the Spain Agriculture Robots Market Segmented in This Report, and What Are the Key Insights from the Segmentation Analysis?
By Type
Which Type Segment Is Expected to Dominate the Spain Agriculture Robots Market During the Forecast Period?
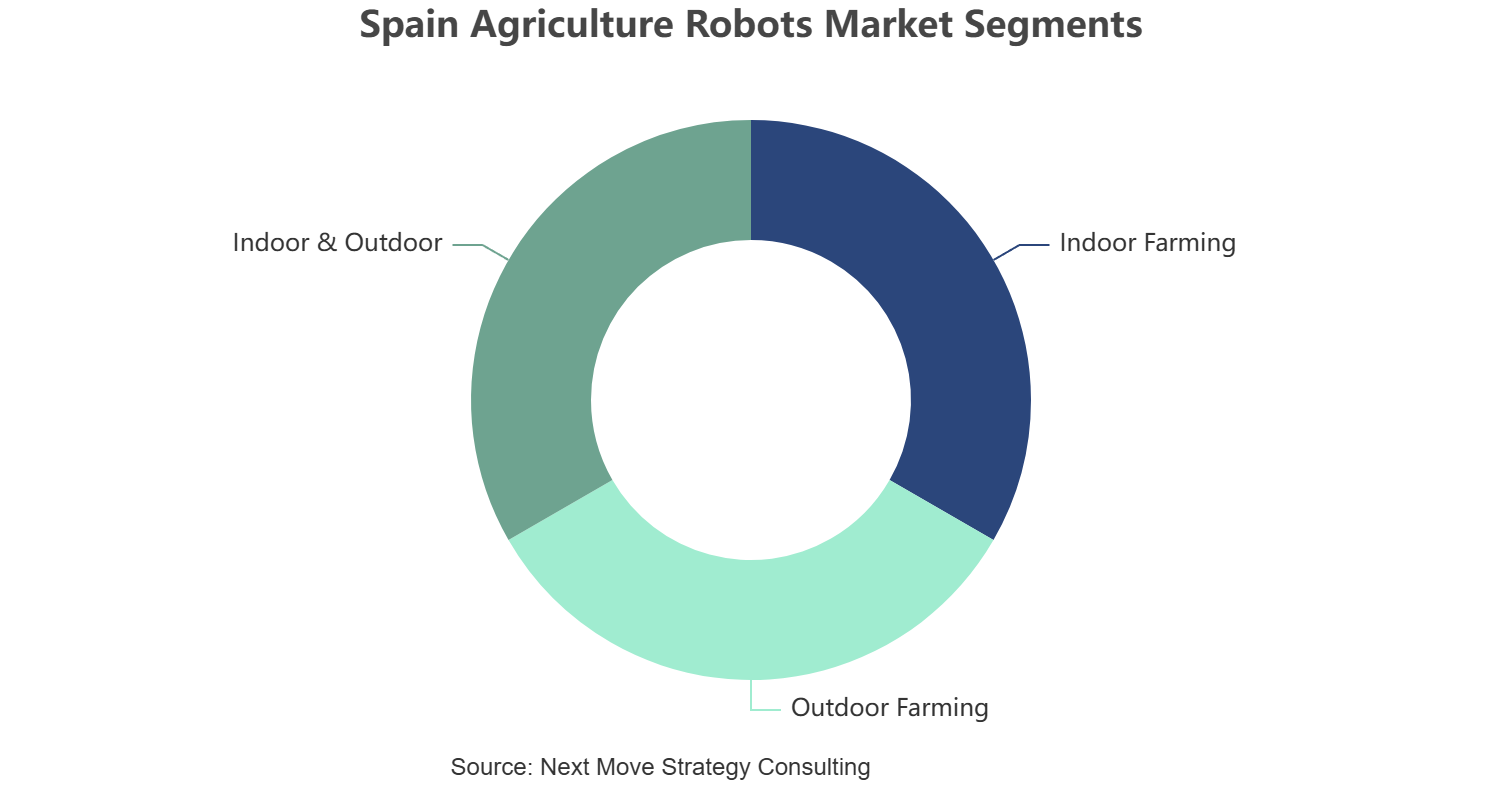
The Spain Agriculture Robots Market by type is segmented into Unmanned Aerial Vehicles (UAVs), Milking Robots, Driverless Tractors, Automated Harvest Robots, and Others.
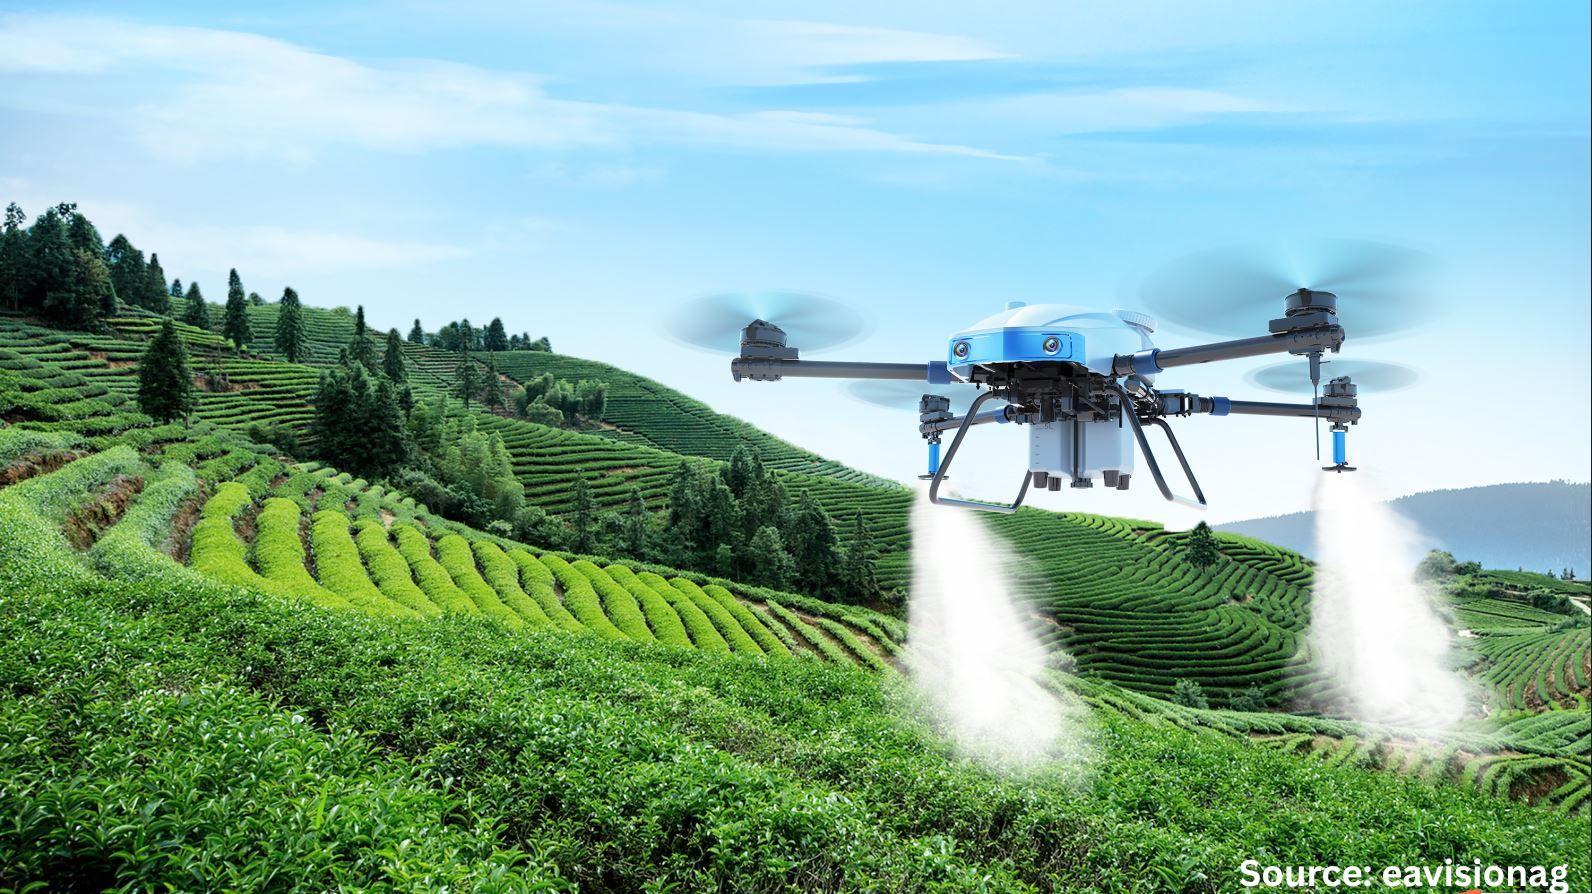
Unmanned Aerial Vehicles (UAVs) represent a leading segment within the Spain Agriculture Robots Market, driven by their versatile applications across crop monitoring, scouting, and protection activities. Automated Harvest Robots are also gaining significant traction as labor costs rise and technological advancements improve their performance across diverse crop varieties. Driverless Tractors and Milking Robots are witnessing growing adoption, particularly among large-scale cereal and dairy farming operations seeking to enhance operational efficiency, reduce manual labor dependence, and improve overall productivity across the Spanish agricultural value chain throughout the forecast period.
By Application
How Does Application Segmentation Influence Market Dynamics Within the Spain Agriculture Robots Market?
The Spain Agriculture Robots Market by application is segmented into Aerial Monitoring & Scouting, Dairy & Livestock Automation, Field Operations, Harvest Management, and Others.
Field Operations constitutes a major application segment, encompassing plowing, seeding, field farming, and soil and irrigation management activities. Aerial Monitoring & Scouting is a high-growth application, enabling precise crop protection, weed control, weather tracking, and inventory management through drone-based systems. Dairy & Livestock Automation, particularly milking and dairy management, is witnessing increased adoption across Spain's dairy farming regions. Harvest Management is emerging as a critical segment as automated solutions reduce post-harvest losses and improve overall agricultural supply chain efficiency across the country.
Key Segments
By Type
-
Unmanned Aerial Vehicles (UAVs)
-
Milking Robots
-
Driverless Tractors
-
Automated Harvest Robots
-
Others
By Farming Type
-
Indoor Farming
-
Outdoor Farming
-
Indoor & Outdoor
By Application
-
Aerial Monitoring & Scouting
-
Crop Protection & Weed Control
-
Crop Scouting & Monitoring
-
Weather Tracking
-
Inventory Management
-
-
Dairy & Livestock Automation
-
Milking
-
Dairy Management
-
Shepherding and Herding
-
-
Field Operations
-
Plowing
-
Seeding
-
Field Farming
-
Soil & Irrigation Management
-
-
Harvest Management
-
Others
Competitive Landscape Overview
The Spain Agriculture Robots Market features a diverse and competitive landscape comprising global agricultural machinery leaders, specialized robotics companies, and regional technology innovators. Leading players are actively investing in research and development to introduce advanced robotic platforms tailored for Spain's unique agricultural environment, including greenhouse and horticulture operations. Strategic partnerships, mergers, acquisitions, and targeted product launches are reshaping competitive dynamics. Companies are also focusing on comprehensive after-sales support and accessible financing solutions to enhance product adoption and expand their customer base across Spanish agricultural regions throughout the forecast period.
Key Players
-
John Deere Ibérica, S.A.
-
CNH Industrial Maquinaria Spain S.A.
-
Robotnik Automation S.L.
-
Soluciones Robóticas Agrícolas S.L.
-
AgXeed B.V.
-
SZ DJI Technology Co., Ltd.
-
DeLaval Holding AB
-
GEA Group AG
-
Lely Holding B.V.
-
BouMatic LLC
-
Kubota España, S.A.
-
CLAAS Ibérica, S.A.
-
AGROINTELLI A/S
-
YANMAR EQUIPMENT IBERICA, S.L.
-
Topcon Positioning Spain SL
The competitive arena features prominent global and regional players including John Deere Ibérica, S.A., CNH Industrial Maquinaria Spain S.A., and Robotnik Automation S.L., alongside emerging innovators such as Soluciones Robóticas Agrícolas S.L. and AgXeed B.V. Aerial technology leader SZ DJI Technology Co., Ltd. and precision agriculture specialist Topcon Positioning Spain SL are strengthening their market presence. Dairy automation leaders DeLaval Holding AB, GEA Group AG, Lely Holding B.V., and BouMatic LLC, together with Kubota España, S.A., CLAAS Ibérica, S.A., AGROINTELLI A/S, and YANMAR EQUIPMENT IBERICA, S.L., collectively drive innovation and competitive dynamics throughout the market.
PESTEL Analysis of the Spain Agriculture Robots Market
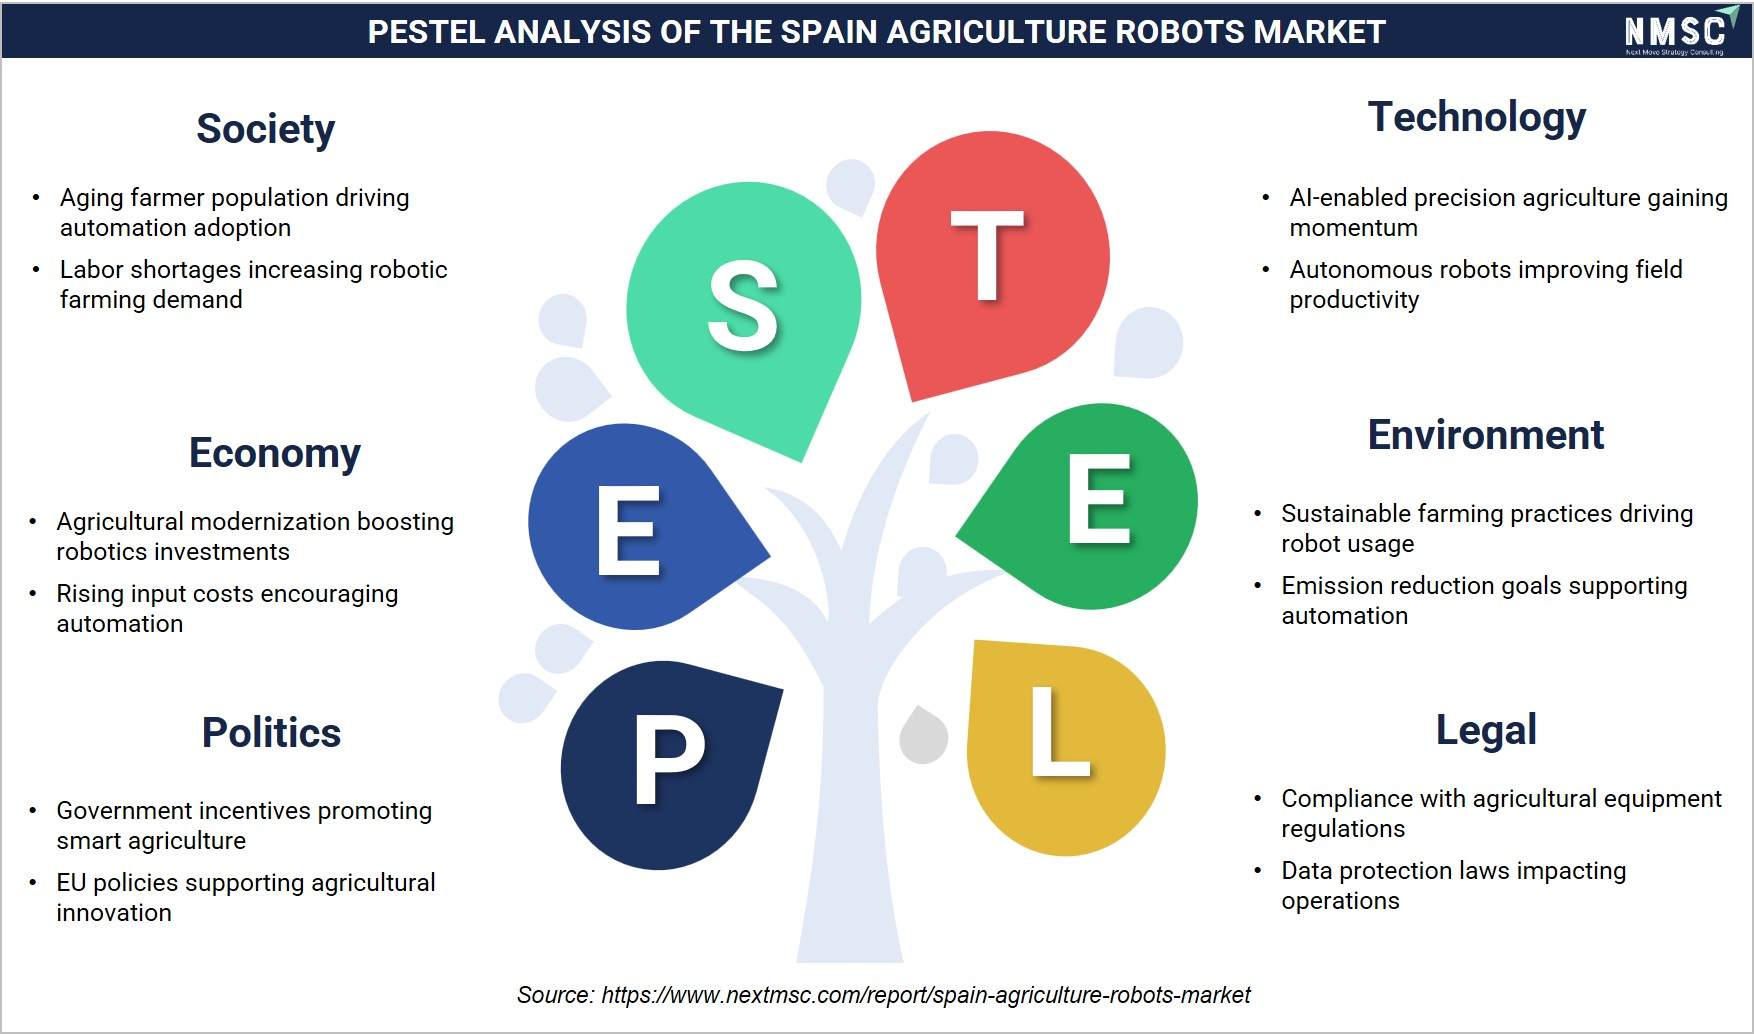
The PESTEL analysis highlights the external factors shaping the Spain Agriculture Robots Market, including supportive agricultural policies, labor shortages, sustainability priorities, digital farming advancements, environmental regulations, and evolving equipment standards. It demonstrates how political, economic, social, technological, environmental, and legal developments collectively influence technology adoption, investment decisions, operational efficiency, and the long-term growth trajectory of agricultural robotics across Spain.
Key Benefits for Stakeholders
This report on the Spain Agriculture Robots Market provides comprehensive insights and actionable intelligence for businesses, investors, and policymakers in the agricultural technology sector. The study delivers detailed analysis of market size, growth trajectories, segmentation dynamics, and competitive landscape, enabling stakeholders to make informed strategic decisions. Historical data from 2025 and market forecasts through 2035 offer thorough understanding of current market conditions and future growth potential, facilitating long-term planning and investment prioritization across key segments including robotics, precision agriculture, and automated farming technologies.
The report enables market participants to identify key growth opportunities, understand competitive positioning, and evaluate potential entry points within the Spain Agriculture Robots Market. Detailed segmentation analysis by type, farming environment, and application provides granular insights necessary for targeted product development and marketing strategies. Additionally, the report's comprehensive assessment of market drivers, restraints, and opportunities equips stakeholders with intelligence required to navigate challenges, capitalize on emerging trends, and sustain long-term competitive advantage within Spain's rapidly evolving agricultural robotics industry.
Report Customization Options
|
Parameters |
Details |
|
Customization Scope |
Free customization (equivalent to up to 80 analyst-working hours) after purchase. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |
|
Approach |
In-depth primary and secondary research; proprietary databases; rigorous quality control and validation measures. |
|
Analytical Tools |
Porter's Five Forces, SWOT, value chain, and Harvey ball analysis to assess competitive intensity, stakeholder roles, and relative impact of key factors. |
Conclusion
The Spain Agriculture Robots Market is poised for substantial growth over the forecast period, driven by escalating water scarcity pressures, rapid expansion of greenhouse agriculture, and persistent labor shortages in horticulture production. With revenues projected to grow from USD 595.93 million in 2026 to USD 2,936.43 million by 2035 at a CAGR of 19.39%, significant opportunities exist for technology providers, investors, and agricultural stakeholders. A dynamic competitive landscape featuring established global players and innovative regional companies will continue to shape market development, fostering technological advancement and broader adoption of robotic solutions across Spain's agricultural sector.
About the Author
 Mihul Sharma
— Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

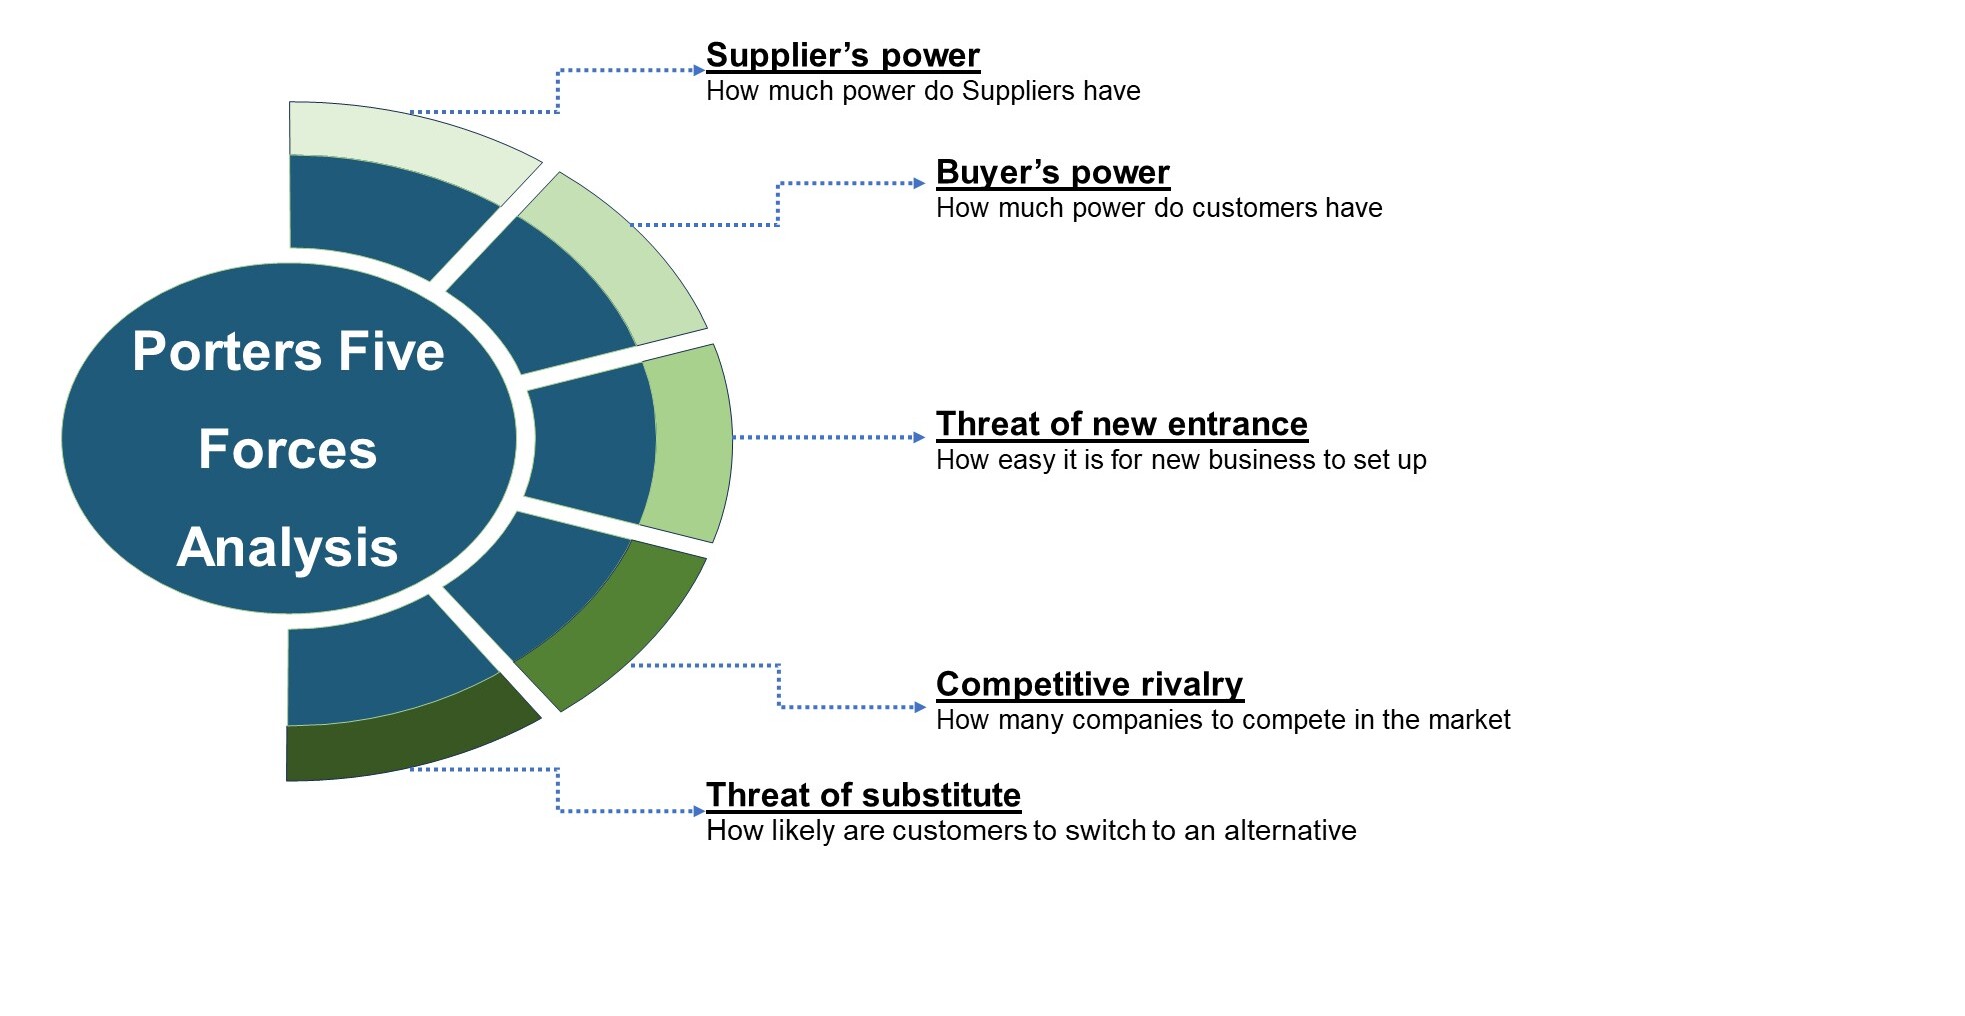
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.



 Speak to Our Analyst