Supply Chain Management Market

Supply Chain Management Market size is estimated at USD 64.45 billion in 2026, projected to reach USD 147.40 billion by 2035, growing at a CAGR of 9.63% from 2026 to 2035. Key drivers include rising enterprise adoption of AI-driven planning and orchestration, with North America leading the market and Middle East & Africa and Latin America registering the fastest growth .
Download Free Sample PDF
Base Year (2025)
$55.24 Billion
Forecast (2035)
$147.40 Billion
CAGR (2026-2035)
9.6%
Top Region
North America

What Is the Supply Chain Management Market Size?
The global supply chain management market size was valued at USD 55.24 Billion in 2025 and is estimated to grow from USD 64.45 Billion in 2026 to USD 147.40 Billion by 2035, expanding at a CAGR of 9.63% between 2026 and 2035. North America led the supply chain management market with an approximate 40% revenue share in 2025, while Software remained the dominant offering segment with an approximate 72% share of global revenue.

We observed that the supply chain management market's momentum is best captured through a concise set of indicators before deeper analysis follows.

Supply Chain Management Market Revenue Forecast
Values in USD Billion

2025 $55.24 Billion
2025
2026 $60.56 Billion
2026
2027 $66.39 Billion
2027
2028 $72.79 Billion
2028
2029 $79.79 Billion
2029
2030 $87.48 Billion
2030
2031 $95.90 Billion
2031
2032 $105.14 Billion
2032
2033 $115.26 Billion
2033
2034 $126.36 Billion
2034
2035 $147.40 Billion
2035

Key Takeaways

By Offering: Software held the largest share of approximately 72% (USD 39.77 billion) in 2025; Services is the fastest-growing offering at 11.79% CAGR from 2026–2035.

By Deployment: Cloud held the largest share of approximately 58% (USD 32.04 billion) in 2025; Cloud is also the fastest-growing deployment mode at 12.73% CAGR from 2026–2035.

By Customer Size: Large Enterprise held the largest share of approximately 62% (USD 34.25 billion) in 2025; Small and Medium Enterprise is the fastest-growing customer size at 14.28% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 40% revenue share (USD 22.10 billion) in 2025.

Fastest-Growing Region: Middle East & Africa and Latin America are expected to register the highest CAGR of 14.06% during 2026– 2035. .

Dominant Country: U.S. led as the largest single national contributor within North America in 2025.

Fastest-Growing Country: Saudi Arabia is among the fastest-growing countries, with a CAGR of approximately 14.4% from 2026–2035 .

Market Opportunity: The supply chain management market is projected to generate an incremental revenue opportunity of approximately USD 82.95 Billion between 2026 and 2035, reflecting the absolute dollar gap between the 2035 forecast and the 2026 base value a signal of accelerating enterprise investment in cloud-native planning and visibility platforms.

According to NMSC analysis, small and medium enterprises are adopting cloud supply chain management platforms at a materially faster rate than large enterprises upgrading legacy on-premises systems, a dynamic reshaping vendor go-to-market priorities beyond what aggregate revenue figures alone convey.

What does the Supply Chain Management Market Encompass?
The supply chain management market encompasses software and services that plan, execute, and monitor the flow of goods, information, and finances across procurement, production, warehouse management , transportation, and order fulfillment functions. Our assessment indicates that the market's scope spans planning, procurement, order and inventory management, warehouse management, transportation and trade management, and supply chain visibility software, delivered through cloud, on-premises, and hybrid deployment models to enterprises of all sizes.

Structurally, the market has evolved from siloed, function-specific planning tools toward integrated, cloud-native platforms connecting demand planning through last-mile execution in near real time. We found that regulatory environments administered by trade and customs authorities continue to shape global trade management functionality, while technology adoption trends in AI-driven demand forecasting and control tower visibility are reshaping how enterprises prioritize platform investment across increasingly complex, multi-tier supplier networks.

Market Drivers & Dynamics

Interactive Dataset
Rising enterprise investment in cloud-native SCM platforms driver +2.6% Global 2026–2035
Growing demand for AI-driven planning and forecasting accuracy driver +1.8% North America, Europe 2026–2033
Expanding supply chain visibility requirements post-disruption driver +1.3% Global 2026–2032
Rising SME adoption of subscription-based SCM software driver +1.0% Asia-Pacific, Latin America 2027–2035
Increasing global trade compliance complexity driver +0.7% North America, Europe, Asia-Pacific 2026–2035
High implementation cost and complexity for large enterprise deployments restraint -0.8% Global 2026–2032
Data integration challenges across legacy multi-vendor IT landscapes restraint -0.6% North America, Europe 2026–2030
Cybersecurity risk associated with cloud-connected supplier networks restraint -0.4% Global 2026–2033
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver for the Supply Chain Management Market?

Rising enterprise investment in cloud-native platforms is the primary growth driver, as organizations replace fragmented, function-specific tools with integrated planning-to-execution suites. The U.S. Census Bureau's e-commerce retail sales data continues to show rising online commerce penetration, underscoring the order volume complexity driving enterprise investment in the fulfillment and visibility software this market provides.

How Is AI-Driven Planning Driving the Market Growth?

AI-driven demand and supply planning is driving growth by materially improving forecast accuracy relative to legacy statistical planning methods. Company analysis indicates that vendors embedding machine learning directly into core planning modules are winning larger enterprise contracts than providers offering AI only as a bolt-on module. Based on research conducted by NMSC, we found that this shift is most pronounced among large enterprise customers replacing decade-old planning systems.

Growth Inhibitors

What Is Restraining the Supply Chain Management Market?

High implementation cost and complexity for large enterprise deployments is restraining adoption timelines, as multi-module platform rollouts across global operations require extensive configuration and change management. We observed that this restraint is most pronounced among enterprises with complex, multi-entity organizational structures, extending implementation timelines well beyond initial vendor estimates and delaying revenue realization for platform providers.

Ecosystem Analysis of Supply Chain Management Market
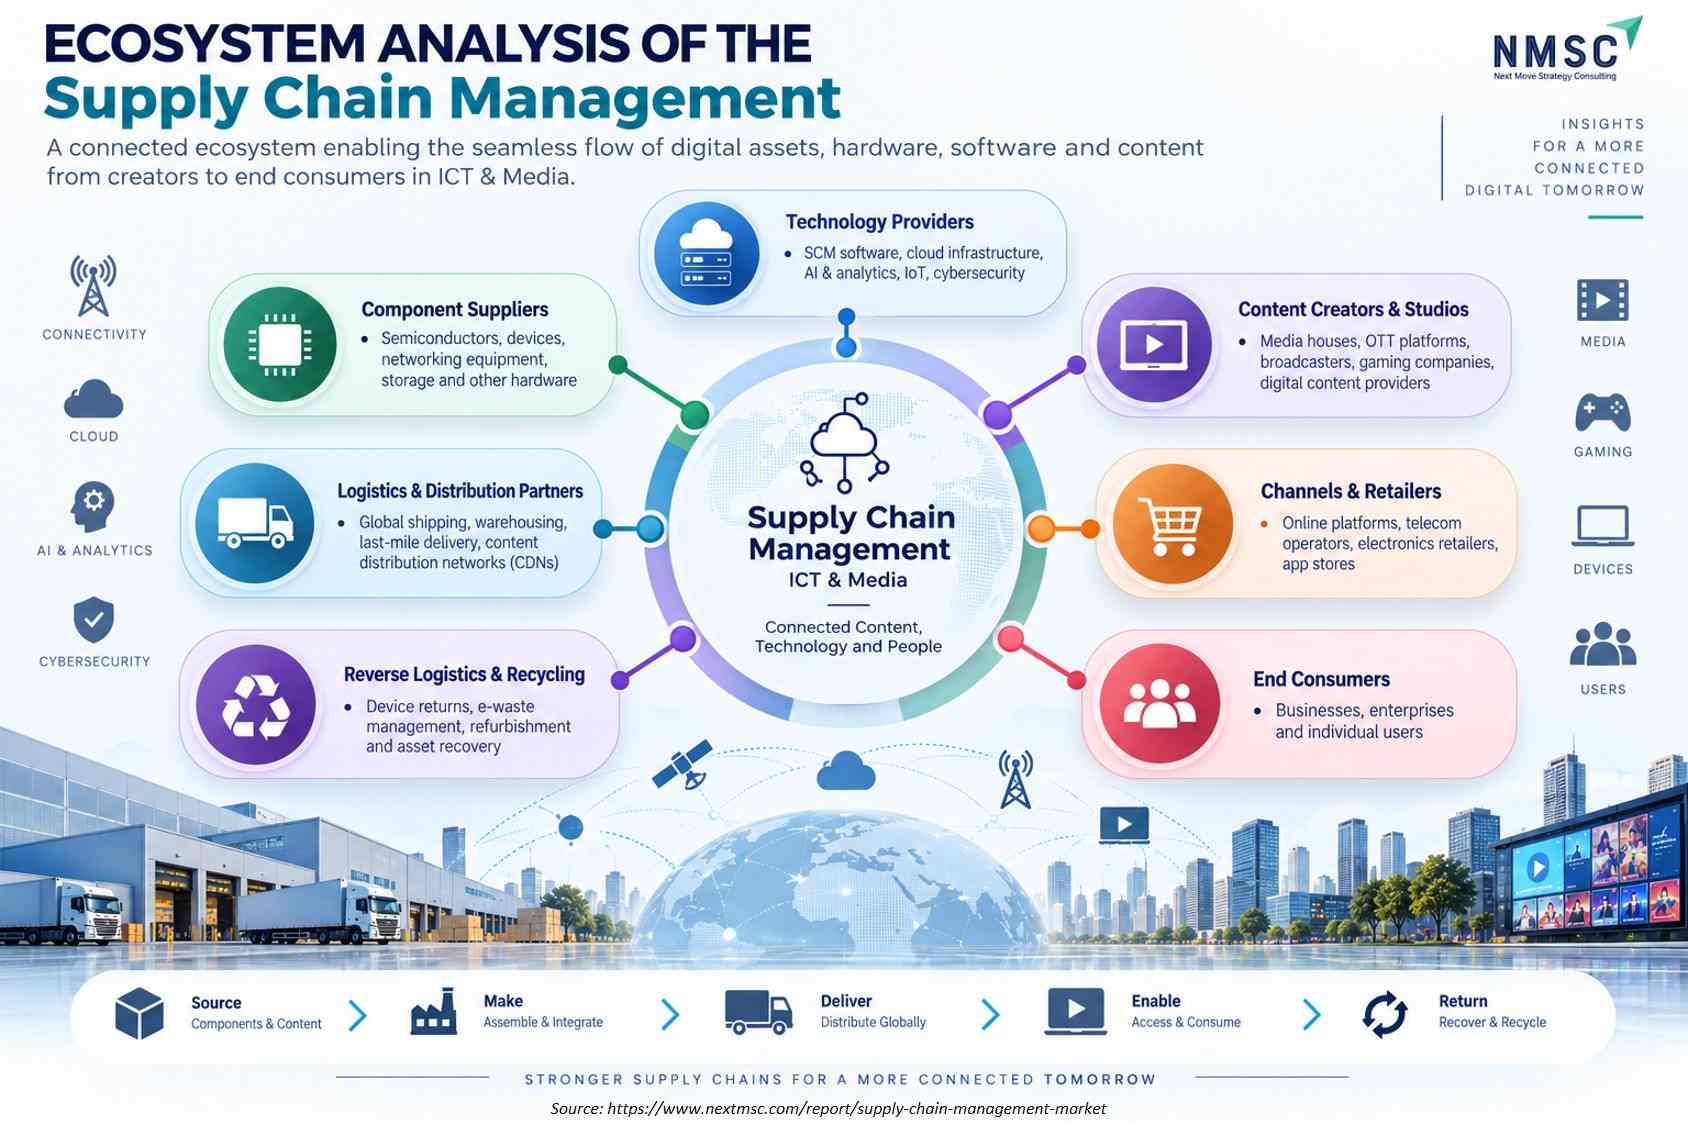
The infographic illustrates the Supply Chain Management Market in ICT & Media, highlighting the flow of digital assets, hardware, software, and content from suppliers to end consumers. It maps key ecosystem participants, including technology providers, component suppliers, content creators, logistics and distribution partners, retailers, and reverse logistics providers. The central SCM framework connects planning, sourcing, manufacturing, delivery, and returns, emphasizing integrated digital networks, efficient distribution, and seamless content delivery.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Software 2025: $39.77 Billion | 2035: $100.23 Billion
Software
Services 2025: $15.47 Billion | 2035: $47.17 Billion
Services
Software $39.77 Billion $100.23 Billion 9.70%
Services $15.47 Billion $47.17 Billion 11.79%

Which Offering Dominates the Supply Chain Management Market?

Software dominates offering segmentation with an estimated USD 39.77 Billion in 2025, rising to USD 100.23 Billion by 2035, reflecting platform licensing and subscription fees as the core revenue category. Services is the fastest-growing segment at a 11.79% CAGR, reflecting rising demand for implementation, integration, and managed services as enterprises deploy increasingly complex, multi-module platforms.

2025 (USD Billion)
2035 (USD Billion)
Cloud 2025: $32.04 Billion | 2035: $106.13 Billion
Cloud
On-Premises 2025: $15.47 Billion | 2035: $23.58 Billion
On-Premises
Hybrid 2025: $6.63 Billion | 2035: $14.74 Billion
Hybrid
Not Applicable 2025: $1.10 Billion | 2035: $2.95 Billion
Not Applicab
Cloud $32.04 Billion $106.13 Billion 12.73%
On-Premises $15.47 Billion $23.58 Billion 4.30%
Hybrid $6.63 Billion $14.74 Billion 8.33%
Not Applicable $1.10 Billion $2.95 Billion 10.34%

Which Deployment Model Leads and Which Is Growing Fastest?

Cloud deployment leads with USD 32.04 Billion in 2025 revenue and is also the fastest-growing model at a 12.73% CAGR, reflecting enterprise preference for reduced infrastructure overhead and faster upgrade cycles over on-premises alternatives. On-Premises deployment continues to decline in relative share as legacy customers migrate toward cloud and hybrid architectures over the forecast period.

2025 (USD Billion)
2035 (USD Billion)
Large Enterprise 2025: $34.25 Billion | 2035: $76.65 Billion
Large Enterp
Mid-Market 2025: $13.26 Billion | 2035: $41.27 Billion
Mid-Market
Small and Medium Enterprise 2025: $7.73 Billion | 2035: $29.48 Billion
Small and Me
Large Enterprise $34.25 Billion $76.65 Billion 8.40%
Mid-Market $13.26 Billion $41.27 Billion 11.98%
Small and Medium Enterprise $7.73 Billion $29.48 Billion 14.28%

Which Customer Size Segment Is Gaining the Most Ground?

Large Enterprise leads customer-size segmentation with USD 34.25 Billion in 2025 revenue, reflecting the scale and complexity of global operations requiring comprehensive platform deployment. Small and Medium Enterprise is the fastest-growing segment at a 14.28% CAGR, driven by rising adoption of subscription-priced cloud platforms that lower the historical cost barrier to enterprise-grade supply chain software.

2025 (USD Billion)
2035 (USD Billion)
Subscription
Perpetual Li
Usage and Tr
Project-Base
Recurring Se
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Subscription $10.0 USD Billion $40.0 USD Billion 23.0%
Perpetual License $17.1 USD Billion $51.1 USD Billion 13.0%
Usage and Transaction-Based $24.2 USD Billion $62.2 USD Billion 23.0%
Project-Based $31.3 USD Billion $73.3 USD Billion 9.0%
Recurring Service Fees $38.4 USD Billion $84.4 USD Billion 26.0%

Segment-wise data not detailed in this view

Unlock complete segment-wise numbers for By Revenue Model.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Manufacturin
Discrete Man
Process Manu
Retail and W
Transportati
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Manufacturing $10.0 USD Billion $40.0 USD Billion 20.0%
Discrete Manufacturing $17.1 USD Billion $51.1 USD Billion 26.0%
Process Manufacturing $24.2 USD Billion $62.2 USD Billion 24.0%
Retail and Wholesale $31.3 USD Billion $73.3 USD Billion 26.0%
Transportation and Logistics $38.4 USD Billion $84.4 USD Billion 9.0%

Segment-wise data not detailed in this view

Unlock complete segment-wise numbers for By End-User Industry.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Direct
System Integ
Reseller
Cloud Market
Other Channe
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct $10.0 USD Billion $40.0 USD Billion 24.0%
System Integrator $17.1 USD Billion $51.1 USD Billion 10.0%
Reseller $24.2 USD Billion $62.2 USD Billion 8.0%
Cloud Marketplace $31.3 USD Billion $73.3 USD Billion 14.0%
Other Channels $38.4 USD Billion $84.4 USD Billion 13.0%

Segment-wise data not detailed in this view

Unlock complete segment-wise numbers for By Sales Channel.

Unlock Full Data

Growth Opportunities

Beyond current demand drivers, three whitespace opportunities stand out as forward-looking mechanisms for revenue expansion through 2035.

Can Packaged Cloud Platforms Unlock Mid-Market Multi-Module Adoption?

Pre-configured, packaged cloud platforms bundling planning, procurement, and visibility modules at simplified pricing can unlock multi-module adoption among mid-market customers currently purchasing single-function tools. This mechanism primarily benefits vendors with proven cloud-native, rapid-deployment implementation methodologies.

Will Embedded Supplier Risk Intelligence Expand Procurement Platform Stickiness?

Embedded, continuously updated supplier risk intelligence integrated directly within procurement platforms offers a mechanism to increase platform stickiness beyond transactional purchasing functionality. Procurement and supplier management vendors with established cloud ERP integration capability stand to benefit most from this expanding risk-intelligence layer.

Can Vertical-Specific Configurations Expand Healthcare and Life Sciences Penetration?

Pre-configured, industry-specific platform variants addressing healthcare and life sciences track-and-trace and cold-chain compliance requirements offer a mechanism to expand penetration in a currently underserved vertical. Vendors with established regulatory compliance module capability are best positioned to capture this opportunity as life sciences supply chain complexity rises.

Porter’s Five Forces analysis of the Supply Chain Management Market

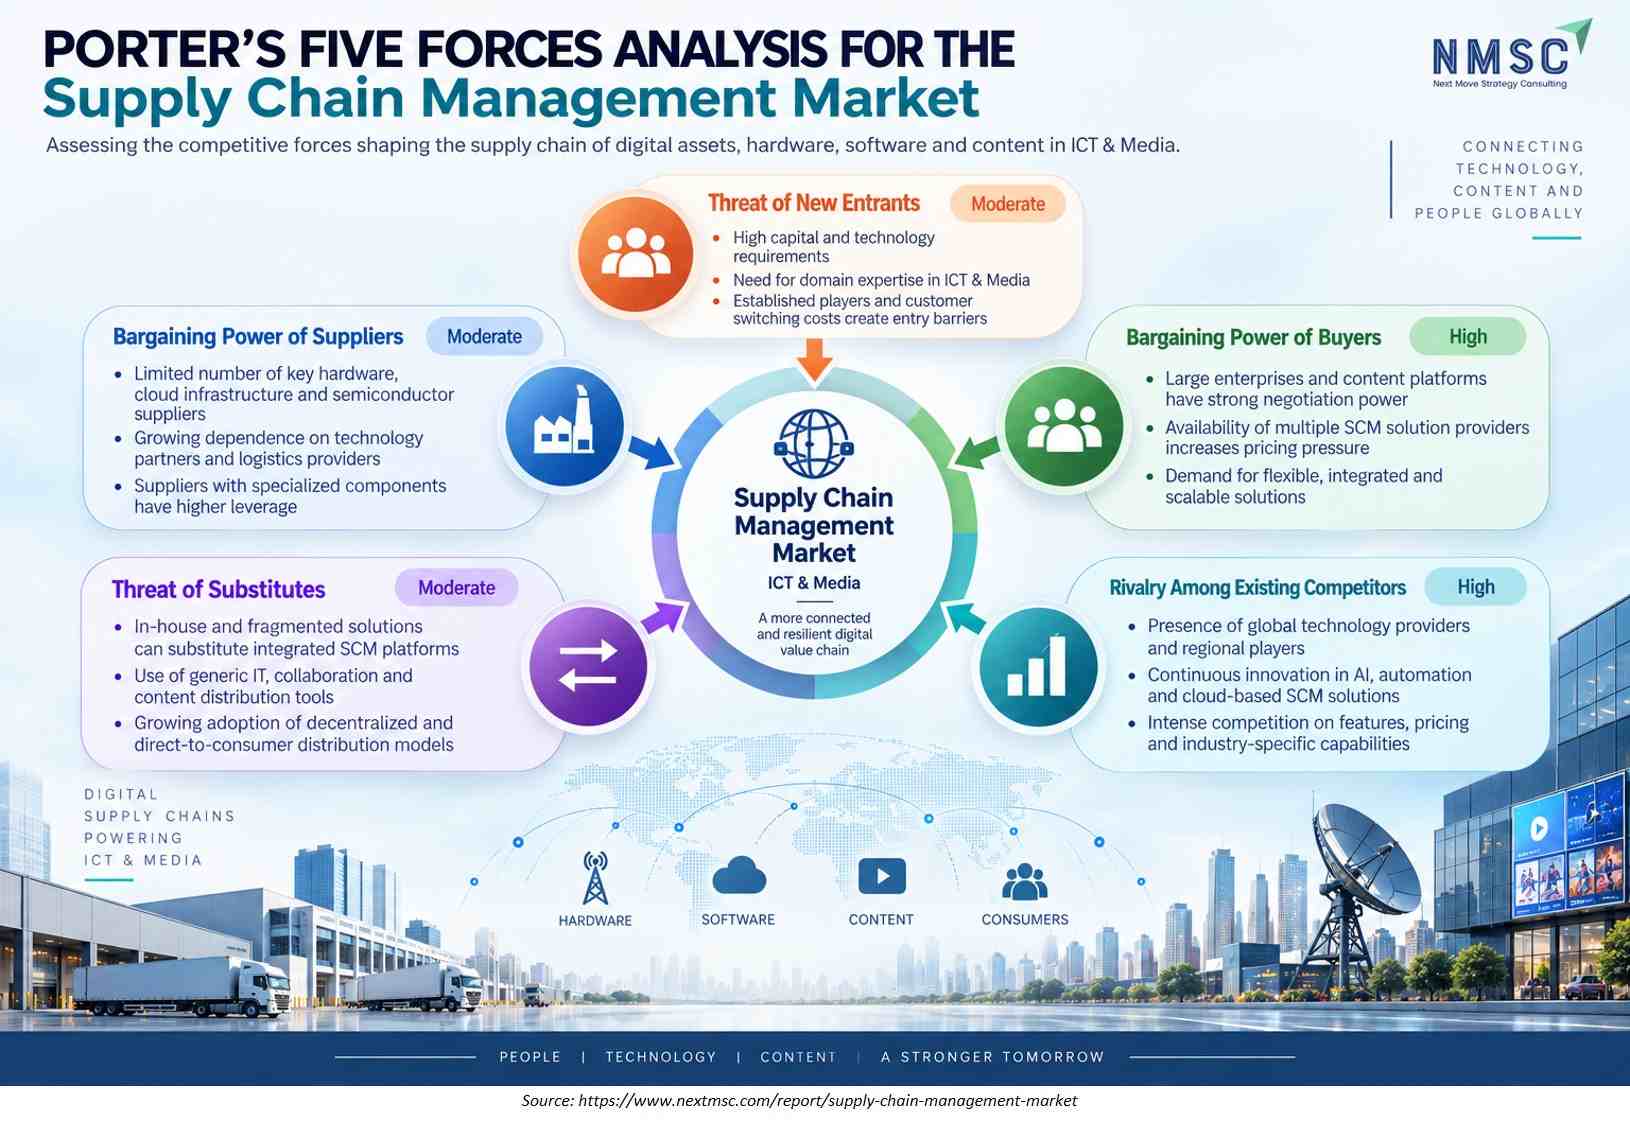
The infographic presents a Porter’s Five Forces analysis of the Supply Chain Management Market in ICT & Media, assessing the competitive dynamics shaping digital supply chains. It highlights moderate threats from new entrants, suppliers, and substitutes, while buyer power and competitive rivalry are high. The central SCM framework connects technology, hardware, software, content, consumers, and global networks, supported by logistics, data infrastructure, and digital distribution visuals.

Regional Outlook

North America $22.10 Billion $50.12 Billion 8.55%
Europe $13.26 Billion $29.48 Billion 8.33%
Asia-Pacific $14.36 Billion $47.17 Billion 12.65%
Middle East & Africa $2.76 Billion $10.32 Billion 14.06%
Latin America $2.76 Billion $10.31 Billion 14.06%

Competitive Landscape

Our findings suggest that the competitive landscape spans diversified enterprise software majors and specialized best-of-breed supply chain platform providers, each pursuing distinct differentiation strategies. Dimension | Assessment Market Structure | Moderately consolidated; diversified enterprise software majors hold significant broad-suite share while specialized providers compete on functional depth in planning, procurement, or visibility Innovation Focus | AI-driven planning, control tower visibility, supplier risk intelligence, cloud-native platform architecture M&A Activity | Elevated; diversified majors acquire specialized best-of-breed providers to close functional and vertical-industry gaps Source: www.nextmsc.com

How Do Companies Compete in the Supply Chain Management Market?

Companies compete primarily on functional breadth across planning, procurement, and execution modules, AI-driven forecasting accuracy, and depth of integration with enterprise resource planning systems. Our analysis shows that vendors combining broad platform coverage with strong AI-native planning capability sustain larger enterprise contract wins than single-function specialists competing on narrow use cases alone.

Which Competitive Archetypes Dominate the Supply Chain Management Industry?

Two archetypes dominate: diversified enterprise software majors offering supply chain modules within broader ERP suites, and specialized best-of-breed providers focused exclusively on planning, procurement, or visibility functions. We observed that the differentiation between these archetypes is narrowing as diversified majors acquire best-of-breed capability to close functional gaps.

What Innovation and Differentiation Strategies Are Companies Pursuing?

Company analysis indicates that leading firms are differentiating through AI-native concurrent planning engines, embedded control tower visibility, and expanded supplier risk intelligence capability. Investment in cloud-native platform architecture continues, alongside expanded vertical-industry configurations targeting healthcare, life sciences, and high-tech electronics customers with specialized compliance requirements.

How Active Is M&A in the Supply Chain Management Industry?

M&A activity remains elevated as diversified enterprise software majors acquire specialized best-of-breed providers to close functional and vertical-industry capability gaps quickly. Based on research conducted by NMSC, we found that acquisition targets increasingly include AI-native planning and supplier risk intelligence developers, reflecting strategic pivots toward the fastest-growing functional categories.

Key Market Players

Our assessment indicates that the following companies represent the validated set of key players shaping competitive dynamics across planning, procurement, execution, and visibility software categories within the supply chain management market.

SAP SE Oracle Corporation Microsoft Corporation International Business Machines Corporation Blue Yonder Group, Inc. Infor, Inc. The Descartes Systems Group Inc. Manhattan Associates, Inc. WiseTech Global Limited Kinaxis Inc. Coupa Software, Inc. Epicor Software Corporation Körber AG NB Ventures, Inc. o9 Solutions, Inc. OMP N.V. JAGGAER, LLC Zycus Inc. Logility , Inc. Generix SA

Latest Developments

We observed that recent company activity centers on AI product launches, strategic acquisitions, and record financial performance across the supply chain management market.

Date Event
September 2026 Manhattan Associates partnered with Boscov’s to modernize ecommerce fulfillment across 51 stores, selecting ActiveOrder to unify inventory visibility, order management, store fulfillment, and customer service. The deployment supports ship-from-store and buy-online-pick-up-in-store, strengthening real-time inventory orchestration and omnichannel execution capabilities within the supply chain management software market.
August 2026 o9 Solutions partnered with Merry Electronics to broaden supply and scenario planning using its AI-powered Digital Brain platform, with IBM as systems integration partner. The initiative addresses constrained supply, complex bills of materials, substitutions, and multi-site operations, expanding AI-enabled planning and strengthening o9’s presence in Taiwan’s electronics supply-chain market.
August 2026 Descartes introduced AI-powered Image Document Management capabilities using logistics-trained agents embedded in customs and transportation solutions. The technology extracts and validates commercial invoices, bills of lading, packing lists, and related documents, reducing manual rekeying and enabling faster shipment and customs workflows for logistics providers and freight forwarders.

Expert Insights

Kaitlynn Sommers

Kaitlynn Sommers

Senior Director Analyst | Gartner

"By prioritizing these technologies based on business requirements and use cases that clearly map toward strategic outcomes, supply chain leaders can better manage complexities and achieve their critical objectives."

Analyst Interpretation

The statement highlights the increasing shift toward business-driven adoption of supply-chain technologies, where organizations evaluate digital solutions according to specific use cases and measurable strategic outcomes. The growing focus on technologies such as agentic AI, intelligent simulation, connectivity and digital tools is supporting the transformation of supply-chain operations. This trend is expected to drive demand for AI-enabled SCM software, intelligent planning, analytics, simulation and connected supply-chain platforms as organizations seek to improve efficiency, adaptability and decision-making.

Investment Opportunities

Where Is Capital Flowing Within the Supply Chain Management Market?

Capital inflows are concentrated in AI-native planning platform development and supplier risk intelligence acquisitions by diversified enterprise software majors. We found that strategic and venture capital is also flowing into vertical-specific supply chain platforms targeting healthcare and life sciences customers, signaling growing institutional interest in compliance-driven niche categories.

How Significant Is Infrastructure Investment in This Market?

Infrastructure investment is substantial, with vendors expanding cloud hosting capacity and AI model training infrastructure to support growing demand for real-time planning and visibility capability. Our assessment indicates that continued investment in API-based integration infrastructure is becoming a prerequisite for competing in multi-vendor enterprise technology landscapes.

What ESG Considerations Are Relevant to This Market?

ESG considerations center on supply chain emissions visibility, ethical sourcing and labor compliance monitoring embedded within supplier management modules, and data center energy efficiency for cloud-hosted platforms. We observed that vendors increasingly disclose emissions-tracking and ethical sourcing module capability in response to enterprise customer sustainability reporting requirements.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders?

Industry and enterprise leaders gain a structured view of offering, deployment, and regional revenue distribution, supporting prioritization decisions across product investment and go-to-market strategy. Our analysis shows that this structured segmentation clarifies where competitive intensity is rising fastest ahead of resource-allocation decisions.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts gain reconciled market-size, CAGR, and regional-growth data supporting valuation and portfolio-allocation decisions. Company analysis indicates that segment-level growth differentials, particularly around cloud deployment and SME customer categories, are material inputs for evaluating vendor growth durability.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain visibility into deployment and offering trends shaping platform architecture and integration infrastructure demand. We found that this analysis supports prioritization of engineering investment toward the fastest-growing delivery mechanisms identified across the forecast period.

Key Market Segments Evaluated

By Offering

  • Software
  • Services

By Deployment

  • Cloud
  • On-Premises
  • Hybrid
  • Not Applicable

By Customer Size

  • Large Enterprise
  • Mid-Market
  • Small and Medium Enterprise

By Revenue Model

  • Subscription
  • Perpetual License
  • Usage and Transaction-Based
  • Project-Based
  • Recurring Service Fees
  • Other Contracted Revenue

By End-User Industry

  • Manufacturing
  • Discrete Manufacturing
  • Process Manufacturing
  • Retail and Wholesale
  • Transportation and Logistics
  • Healthcare and Life Sciences
  • High-Tech and Electronics
  • Energy and Resources
  • Consumer Services
  • Public Sector
  • Other Industries

By Sales Channel

  • Direct
  • System Integrator
  • Reseller
  • Cloud Marketplace
  • Other Channels

Conclusion & Recommendations

The long-term outlook remains firmly expansionary, with revenue projected to more than double from USD 64.45 Billion in 2026 to USD 147.40 Billion by 2035 at a 9.63% CAGR. Our analysis shows that this trajectory is underpinned by structural demand for cloud-native, AI-driven platforms rather than cyclical IT refresh spending alone.

What Strategic Positioning Should Companies Pursue?

Companies should prioritize AI-native planning capability and broad functional coverage over narrow, single-purpose tools. We found that vendors combining strong forecasting accuracy with integrated procurement, execution, and visibility modules sustain larger, more durable enterprise contracts than single-function competitors.

How Attractive Is the Market for Investment?

Investment attractiveness is high given double-digit growth in cloud deployment and SME customer categories alongside a large, stable base of large-enterprise planning and fleet management platform demand. Capital allocators should weight exposure toward vendors with proven AI-driven planning and visibility capability over legacy on-premises-only competitors.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Key risks include high implementation cost and complexity for large enterprise deployments, data integration challenges across legacy IT landscapes, and cybersecurity risk associated with cloud-connected supplier networks. We observed that implementation complexity poses the most immediate risk to revenue timing for vendors serving large, multi-entity enterprise customers.

What Are the Primary Growth Pathways Through 2035?

Primary growth pathways include packaged cloud platforms for mid-market multi-module adoption, embedded supplier risk intelligence expanding procurement platform stickiness, and vertical-specific configurations for healthcare and life sciences customers. Our findings suggest that companies combining all three pathways will outpace single-lever competitors through the forecast period.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Diana Trejo

DIANA TREJO

Assistant Manager

Sumitomo Corporation de Mexico, S.A. de C.V.

Recently, we purchased a report on the Mexico Data Center Market from Next Move Strategy Consulting. The service has been excellent, with support that is always timely and thoroughly professional. The information provided is interesting, highly useful, and delivered with clarity. I would highly recommend NextMSC for anyone seeking insightful and dependable analysis.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖