Australia Fabric Care Market, By Product Type {Fabric Detergents (General Purpose, Baby Laundry Detergent, and Delicate Laundry Detergent), Fabric Softeners/Conditioners, and Others}, By Form (Liquid, Powder, Unit-Dose, Sheet & Wipe, and Spray), By Nature (Conventional and Eco-friendly / Organic), By Price Tier (Value, Mid-range, and Premium), By Distribution Channel (Online and Offline), and By End-User (Residential, Commercial, and Others) – Analysis & Forecast, 2025–2035
Industry: Retail and Consumer | Latest Edition: August 17, 2026 | No of Pages: 153 | No. of Tables: 49 | No. of Figures: 43 | Format: PDF | Report Code: RC4555
Australia Fabric Care Market Size & Forecast
|
Parameters |
Details |
|
Market Size in 2025 |
USD 5.76 billion |
|
Market Size in 2026 |
USD 6.65 billion |
|
Revenue Forecast in 2035 |
USD 12.14 billion |
|
Growth Rate |
CAGR of 6.92% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Billion (USD) |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 companies |
Industry Outlook
The Australia Fabric Care Market was valued at USD 5.76 billion in 2025, reflecting a mature yet dynamically evolving market characterized by high per-capita consumer spending, strong sustainability-oriented purchasing values, and a distinctive competitive landscape shaped by dominant grocery retail duopoly influence and an increasingly prominent domestic eco-brand ecosystem. The market is projected to reach USD 6.65 billion by 2026 and is forecast to expand to USD 12.14 billion by 2035, at a CAGR of 6.92% from 2026 to 2035. Growth is driven by eco-certified product premiumization, water-efficient formulation adoption, and accelerating e-commerce distribution channel expansion throughout the forecast period.
What Are the Key Market Drivers, Restraints, and Opportunities Shaping the Australia Fabric Care Market Through 2035?
|
Growth Catalyst & Risk Assessment Matrix |
(+/–) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Australia's expanding eco-conscious consumer culture and sustainability certification demand driving accelerated adoption of certified organic, plant-based, and biodegradable fabric care formulations |
+2.0% |
Major urban centers: Sydney, Melbourne, Brisbane, Perth |
Long term (4–7 years) |
|
Australia's water scarcity challenges and drought awareness creating strong consumer and regulatory demand for cold-water-compatible, concentrated, and water-efficient fabric care solutions |
+1.6% |
Nationwide, with particular strength in drought-affected and water-restricted regions |
Medium to Long term (3–6 years) |
|
Rapid e-commerce and direct-to-consumer channel growth enabling domestic eco-brands to scale nationally beyond physical retail and reach premium urban consumer segments at lower distribution cost |
+1.4% |
Sydney, Melbourne, Brisbane, and surrounding metropolitan areas |
Medium term (2–5 years) |
|
Elevated cost of living pressures and post-inflation consumer caution compressing discretionary household spending and moderating premiumization momentum across mid-range and premium fabric care tiers |
–1.7% |
Nationwide |
Short to Medium term (1–4 years) |
|
Expanding commercial and institutional fabric care demand from Australia's recovering tourism industry and growing healthcare and hospitality services sectors creating incremental revenue channels |
+0.9% |
Major tourism corridors: Gold Coast, Cairns, Sydney, Melbourne |
Medium term (2–5 years) |
The Australia Fabric Care Market is shaped by a unique convergence of environmental consciousness, water resource constraints, retail structural dynamics, and digital channel acceleration that collectively define one of the Asia-Pacific region's most sophisticated fabric care competitive environments. Our analysis indicates that eco-certification alignment, water-efficiency innovation, and e-commerce-led domestic brand scaling represent the primary growth catalysts through 2035. However, elevated cost-of-living pressures are moderating the pace of premiumization, requiring manufacturers to demonstrate tangible consumer value beyond sustainability messaging to sustain revenue momentum across all price tiers throughout the forecast period.
Growth Drivers:
How Is Australia's Expanding Eco-Conscious Consumer Culture Driving Certified Organic and Plant-Based Fabric Care Adoption?
Australia's deeply embedded environmental values, reinforced by growing awareness of water system health, microplastic pollution, and chemical ingredient safety, are driving measurable demand growth for certified organic, plant-based, and biodegradable fabric care formulations across mainstream and premium consumer segments. Our assessment indicates that Australian consumers increasingly demand transparency in ingredient sourcing, packaging recyclability, and third-party environmental certification, creating a structural competitive advantage for domestic eco-brands, including Natures Organics Pty Ltd, Ecostore Australia Pty Ltd, and Koala Eco Pty Ltd. This values-driven demand is simultaneously compelling multinational operators to reformulate and reposition existing product lines toward sustainability compliance throughout the forecast period.
How Is Australia's Water Scarcity Context and Drought Awareness Shaping Fabric Care Formulation and Consumer Preferences?
Australia's recurring drought conditions, water restriction policies, and deeply ingrained national water conservation consciousness are creating a structurally differentiated demand signal for cold-water-compatible, concentrated, and rinse-efficient fabric care formulations that reduce total water consumption per wash cycle. Our analysis indicates that product attributes communicating water efficiency, cold-water performance, and reduced rinse requirements carry meaningful competitive value in Australian retail channels, supporting premium positioning and consumer willingness to pay above-average prices for demonstrably water-conscious formulations. Domestic specialists including Euca Technologies Pty Ltd and Tri Nature Pty Ltd have built brand positioning anchored around exactly these water-efficiency credentials.
How Is E-Commerce and Direct-to-Consumer Channel Growth Enabling Australia's Domestic Eco-Brands to Scale Nationally?
Australia's well-developed e-commerce infrastructure and growing consumer comfort with online household product procurement are enabling domestic eco-fabric care brands to achieve national distribution reach without the shelf-space negotiating leverage required in Woolworths-Coles-dominated physical retail channels. Our market assessment indicates that brands including The Dirt Company Pty Ltd, Murchison-Hume Pty Ltd, and Koala Eco Pty Ltd have successfully leveraged direct-to-consumer e-commerce and marketplace platforms to build nationally scaled businesses with premium positioning, subscription models, and concentrated format propositions that deliver both environmental credentials and compelling per-use-cost value arguments to Australia's quality-oriented urban consumer base.
Growth Inhibitor:
How Are Australia's Elevated Cost-of-Living Pressures Constraining Premiumization Momentum in the Fabric Care Market?
Australia's persistent cost-of-living pressures, including elevated mortgage rates, high grocery price inflation, and compressed household discretionary budgets, are creating measurable headwinds for fabric care market premiumization by prompting consumer value-seeking behavior and category trade-down across mid-range and premium product tiers. Our assessment indicates that private-label fabric care offerings from Woolworths Group Limited and Coles Group Limited are gaining incremental share as budget-conscious consumers migrate toward retailer-owned value alternatives. ALDI Stores' aggressively priced own-brand fabric care range is further amplifying this private-label competitive pressure, creating structural constraints on branded manufacturers' average selling price growth throughout the near-term forecast period.
Growth Opportunity:
How Is Australia's Recovering Tourism Sector and Growing Institutional Services Industry Creating New Commercial Fabric Care Demand Channels?
Australia's post-pandemic tourism sector recovery, expanding healthcare infrastructure, and growing professional hospitality services industry are collectively generating incremental commercial and institutional fabric care procurement demand that represents a meaningful revenue growth channel beyond residential consumer markets. Our analysis indicates that hotels, aged care facilities, hospital laundry services, and commercial cleaning operators are increasing procurement of specialized, high-concentration, and regulatory-compliant fabric care formulations in response to heightened hygiene standards and operational efficiency requirements. Operators, including Pental Products Pty Ltd and established commercial channel specialists are strategically positioned to capture this expanding institutional demand through dedicated commercial product portfolios and service-integrated supply relationships throughout the forecast period.
How Is the Australia Fabric Care Market Segmented in This Report, and What Are the Key Insights from the Segmentation Analysis?
By Form Insights
How Does Product Form Segmentation Reflect Consumer Convenience and Sustainability Preferences Across the Australia Fabric Care Market?
Based on form, the Australia Fabric Care Market is segmented into liquid, powder, unit-dose pods and sachets, sheet & wipe, and spray formulations.
The market reflects a diversified product structure where consumer preferences are increasingly shaped by convenience, washing efficiency, and sustainability considerations in everyday laundry routines. In our observation, liquid and powder formats continue to support routine fabric cleaning needs due to their familiarity and versatility across different wash types, while unit-dose formats such as pods and sachets are gaining preference for their ease of use and precise dosing benefits. At the same time, sheet & wipe and spray formulations are emerging steadily, driven by demand for compact, eco-friendly, and on-the-go fabric care solutions.
By End-User Insights
How Does End-User Segmentation Define Revenue Distribution and Growth Dynamics Across the Australia Fabric Care Market?
Based on end-user, the Australia Fabric Care Market is segmented into residential, commercial, and other end-user categories.
The market reflects a demand structure shaped by both household consumption patterns and institutional usage needs, where fabric care products are increasingly tailored to different usage intensities and performance requirements. In our observation, the residential segment remains strongly driven by routine laundry activities supported by high washing machine penetration and consistent per-household product usage. At the same time, the commercial segment is expanding steadily with rising demand from hospitality, healthcare, and tourism-related services, where specialized, high-performance fabric care solutions are increasingly preferred. The other segment caters to niche and emerging institutional applications, further diversifying overall market demand.
Consumer Behavior Analysis of the Australia Fabric Care Market:
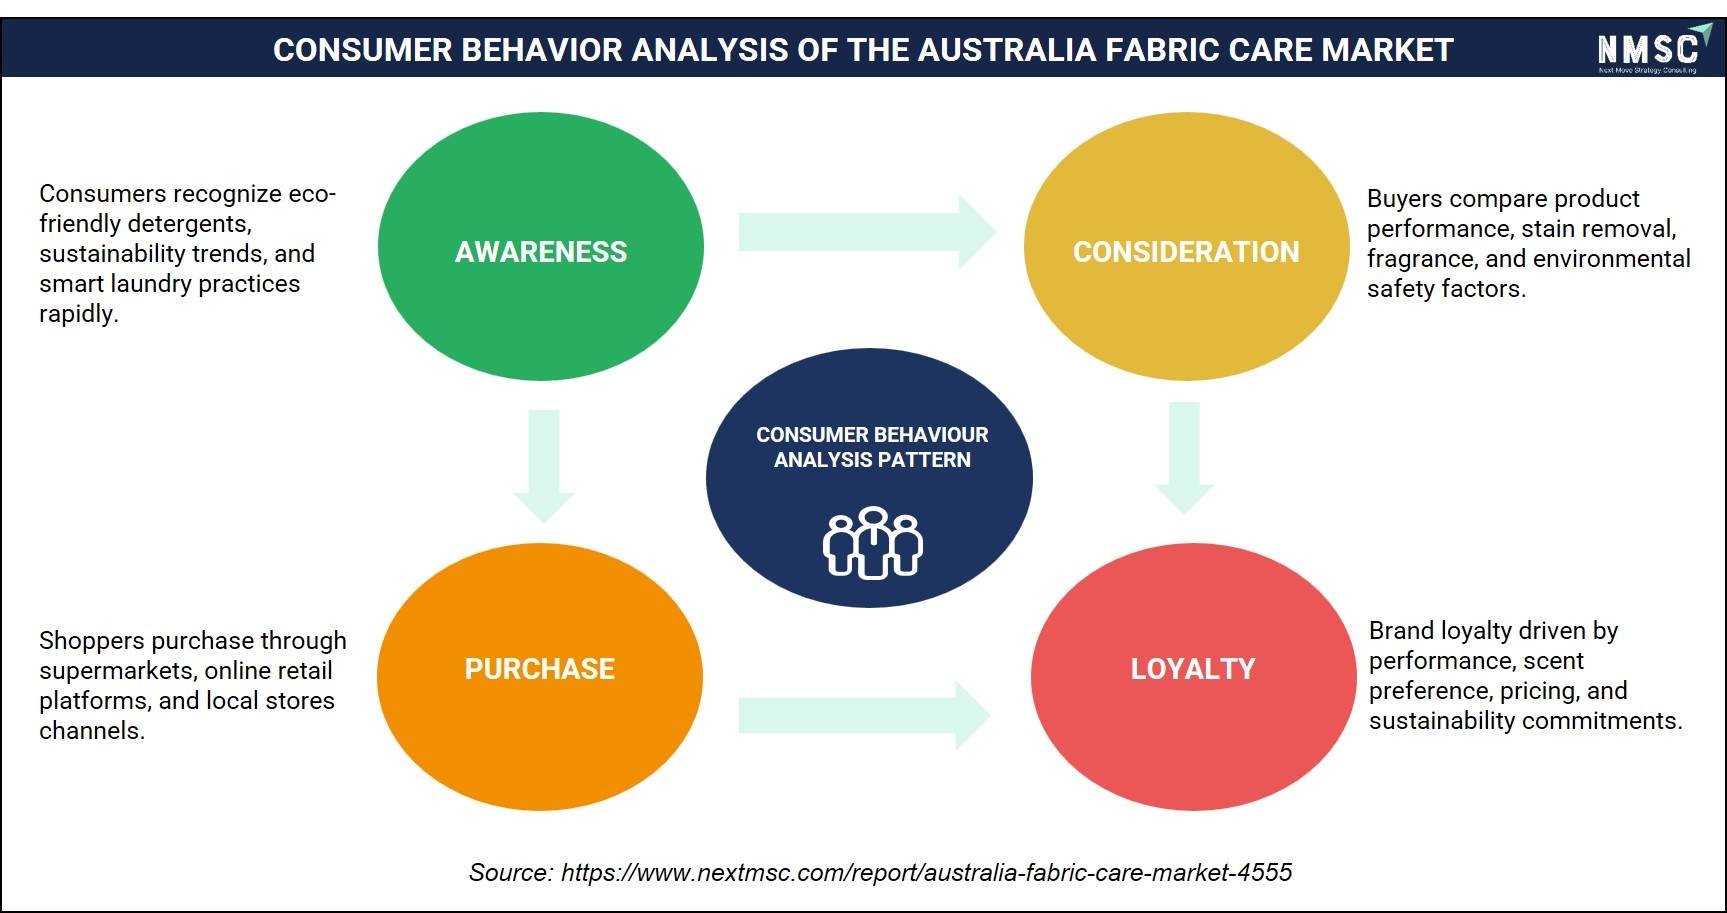
The above consumer behavior analysis maps the key decision-making stages, such as awareness, consideration, purchase, and loyalty, shaping the Australia fabric care market. From our analysis, we observed that the awareness stage reflects rapidly growing consumer recognition of eco-friendly detergents, sustainability trends, and smart laundry practices, while the consideration phase involves buyers comparing product performance, stain removal, fragrance, and environmental safety factors. During purchase, shoppers primarily transact through supermarkets, online retail platforms, and local store channels, whereas brand loyalty is ultimately driven by performance, scent preference, pricing, and sustainability commitments.
Key Segments
By Product Type
-
Fabric Detergents
-
General Purpose
-
Baby Laundry Detergent
-
Delicate Laundry Detergent
-
-
Fabric Softeners/Conditioners
-
Stain Removers/Bleach
-
Sanitizer
-
Other Products
By Form
-
Liquid
-
Powder
-
Unit-Dose
-
Pods
-
Sachets
-
-
Sheet & Wipe
-
Spray
By Nature
-
Conventional
-
Eco-friendly / Organic
By Price Tier
-
Value
-
Mid-range
-
Premium
By Distribution Channel
-
Online
-
Marketplaces
-
Brand E-com
-
Quick Commerce
-
-
Offline
-
Supermarkets
-
Hypermarkets
-
Department Stores
-
By End-User
-
Residential
-
Commercial
-
Others
Competitive Landscape
The Australia Fabric Care Market features a distinctively structured competitive landscape shaped by the simultaneous dominance of major grocery retail chains operating influential private-label programs, established multinational household care brands, and a rapidly scaling domestic eco-brand sector with strong sustainability credentials and direct-to-consumer distribution capabilities. Competitive dynamics are materially influenced by supermarket shelf negotiating power, where access to mainstream consumer reach is partially gated by retailer ranging decisions. This structure has accelerated the growth of e-commerce and direct-to-consumer channels as an alternative pathway for domestic eco-brands seeking national scale without retail intermediary dependence across Australia's competitive fabric care environment.
Key Players of the Australia Fabric Care Market:
-
Henkel Australia Pty Ltd
-
Colgate-Palmolive Pty Ltd
-
Woolworths Group Limited
-
Coles Group Limited
-
ALDI Stores (A Limited Partnership)
-
Natures Organics Pty Ltd
-
Pental Products Pty Ltd
-
Ecostore Australia Pty Ltd
-
Koala Eco Pty Ltd
-
Tri Nature Pty Ltd
-
The Dirt Company Pty Ltd
-
Murchison-Hume Pty Ltd
-
Bosistos Pty Ltd
-
Euca Technologies Pty Ltd
Key players shaping the Australia Fabric Care Market include Unilever Australia Group Pty Limited, Henkel Australia Pty Ltd, Colgate-Palmolive Pty Ltd, Woolworths Group Limited, Coles Group Limited, ALDI Stores (A Limited Partnership), Natures Organics Pty Ltd, Pental Products Pty Ltd, and others, competing through eco-certification investment, private-label positioning, direct-to-consumer e-commerce scaling, and water-efficient formulation innovation to capture share across Australia's rapidly evolving and sustainability-driven fabric care consumer market.
Price Point Analysis of the Australia Fabric Care Market:
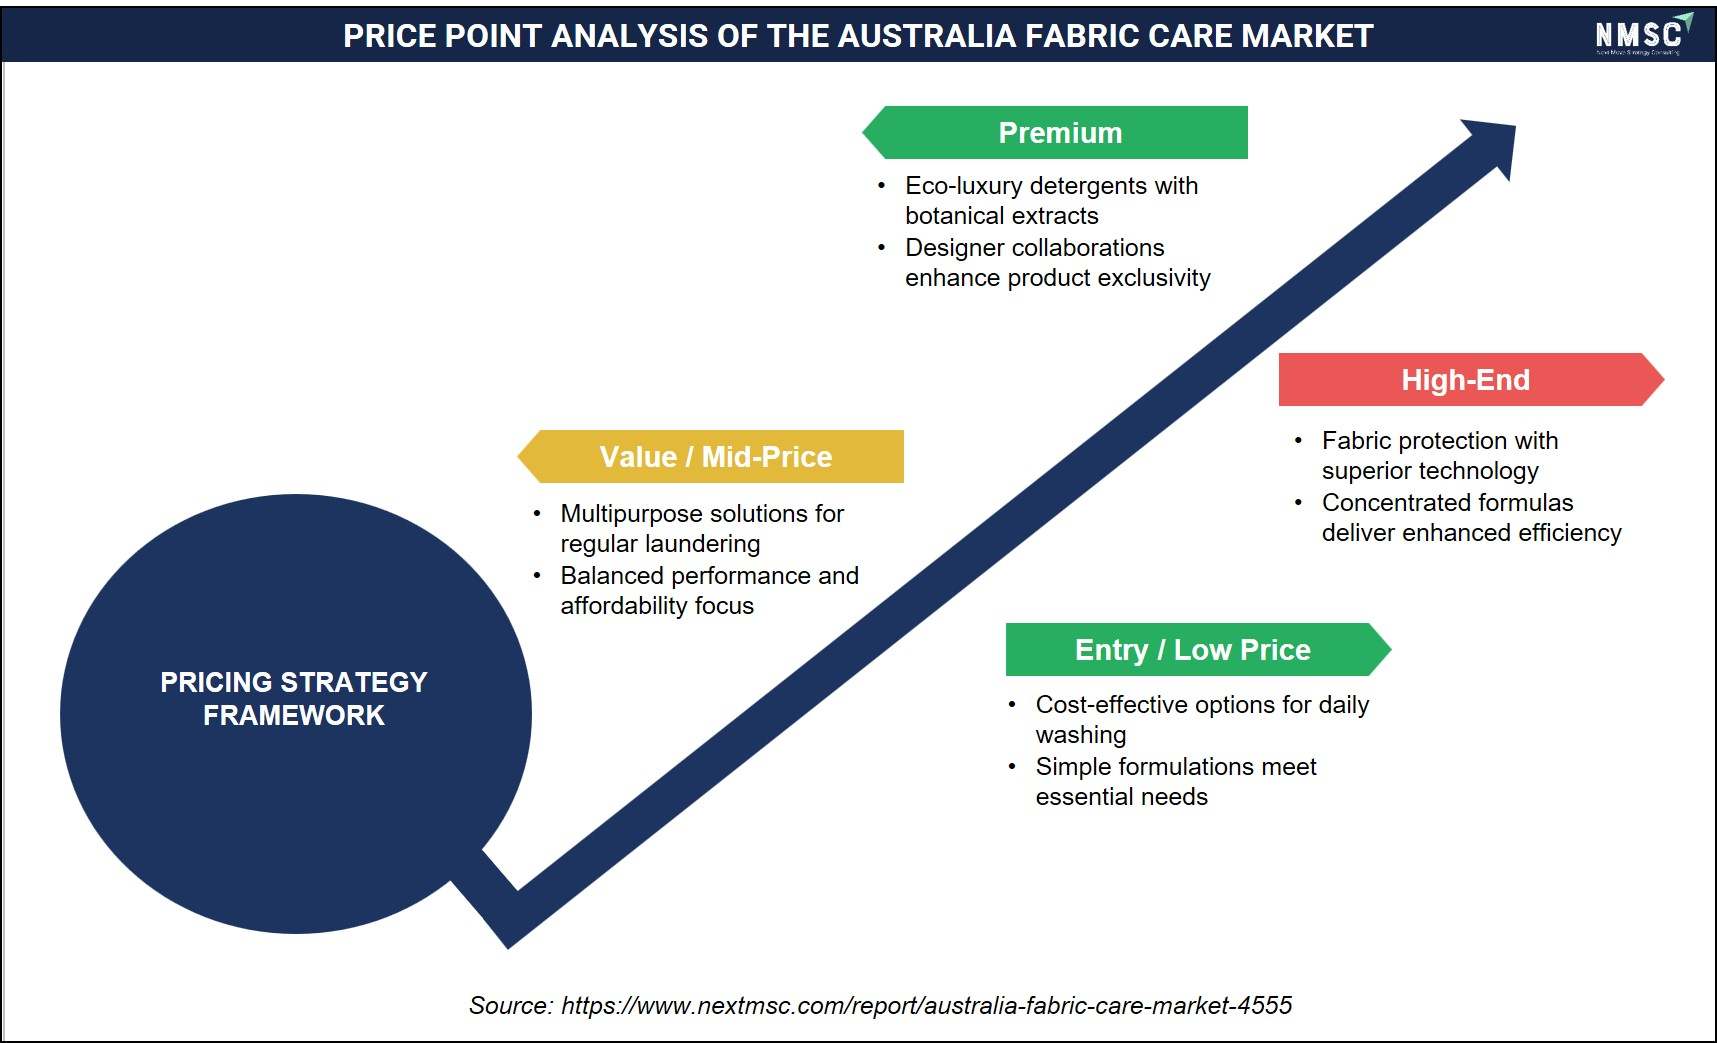
The above price point analysis maps the key pricing tiers, such as entry or low price, value or mid-price, premium, and high-end, shaping the Australia fabric care market. From our analysis, we observed that the value or mid-price segment captures the largest consumer base, as affordability and everyday usability remain top priorities for most households, while premium and high-end segments are steadily gaining traction among urban consumers seeking specialized fabric protection and eco-friendly formulations.
Key Benefits for Stakeholders
Next Move Strategy Consulting (NMSC) presents a comprehensive analysis of the Australia Fabric Care Market, covering historical performance from 2020 through 2025 and detailed revenue forecasts extending through 2035. The report delivers quantitative projections and qualitative insights across all primary segments, including product type, form, nature, price tier, distribution channel, and end-user categories at the national level. Strategic analysis covers key growth catalysts, Australia-specific regulatory and environmental influences, retail structural dynamics, and competitive positioning, equipping stakeholders with the research foundation required for informed investment, market entry, and product development decisions throughout the forecast period.
Investors, brand operators, and distribution partners active in the Australia Fabric Care Market gain strategic value from NMSC's rigorous segmentation analysis, competitive landscape profiling, and forward-looking channel performance benchmarking. Manufacturers benefit from actionable intelligence on water-efficiency formulation trends, eco-certification competitive requirements, and e-commerce channel growth trajectories that directly shape portfolio and go-to-market strategy. Retailers and institutional buyers access structured insights into private-label competitive dynamics, commercial segment demand evolution, and premium eco-product pricing tier developments, enabling evidence-based supplier selection and category management optimization across Australia's distinctive fabric care retail landscape.
|
Parameters |
Details |
|
Customization Scope |
Free customization (equivalent to up to 80 analyst-working hours) after purchase. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |
|
Approach |
In-depth primary and secondary research; proprietary databases; rigorous quality control and validation measures. |
|
Analytical Tools |
Porter's Five Forces, SWOT, value chain, and Harvey ball analysis to assess competitive intensity, stakeholder roles, and relative impact of key factors. |
Conclusion
The Australia Fabric Care Market presents a compelling growth opportunity anchored by one of the Asia-Pacific region's most sustainability-conscious consumer bases, strong per-capita household spending, and an accelerating domestic eco-brand sector challenging established multinational incumbents through direct-to-consumer e-commerce and certified sustainable product innovation. With revenue projected to expand from USD 5.76 billion in 2025 to USD 12.14 billion by 2035 at a CAGR of 6.92%, the market rewards participants combining water-efficiency formulation credentials, eco-certification investment, and multi-channel distribution excellence. Navigating private-label competitive pressure from dominant grocery retailers will remain a defining strategic challenge throughout the forecast period.
About the Author
 Mayurima Roy
— Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

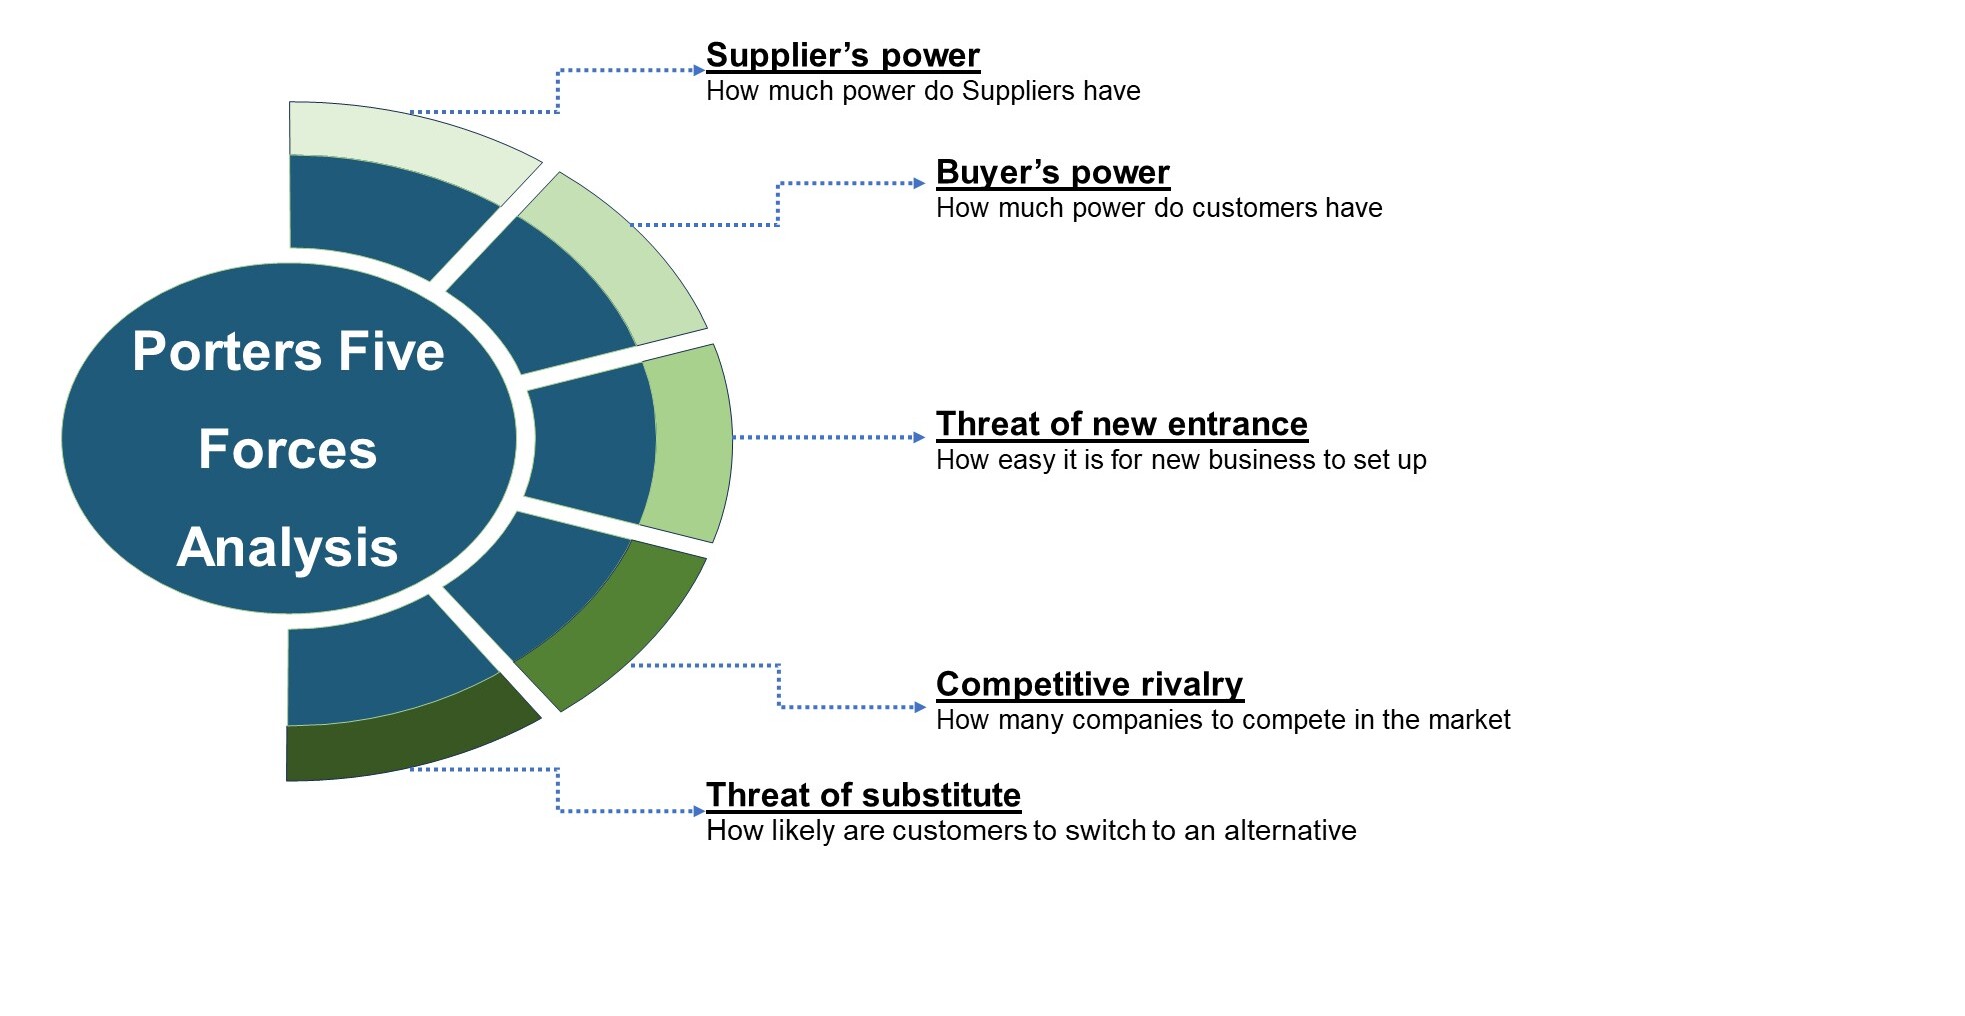
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.




 Speak to Our Analyst