Australia Industrial Robotics Market Size, Share, Trends and Growth Analysis, By Robot Type (Articulated Robots, SCARA Robots, Cartesian and Gantry Robots, Delta Robots, Collaborative Robots, Autonomous Mobile Robots (AMRs), Automated Guided Vehicles (AGVs), and Other Robots), By Offering (Hardware, Software, and Services), By Application (Handling, Welding and Soldering), By Mounting Type, By Mobility, By Payload Capacity, By End User – Opportunity Analysis and Industry Forecast, 2025–2035
Industry: Construction & Manufacturing | Latest Edition: September 30, 2026 | No of Pages: 268 | No. of Tables: 144 | No. of Figures: 130 | Format: PDF | Report Code: CM3712
What Is the Australia Industrial Robotics Market Size?
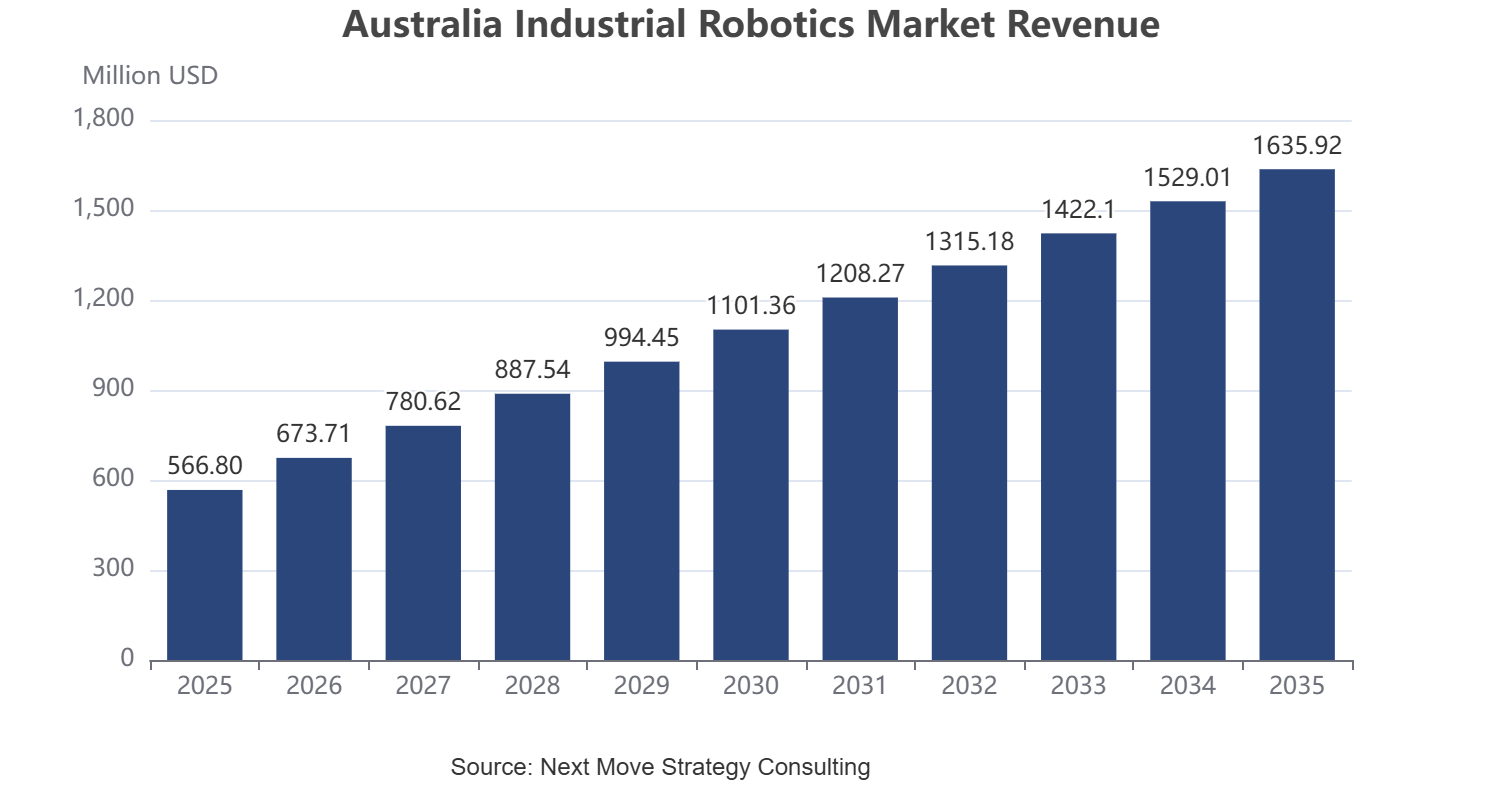
The Australia industrial robotics market size was valued at USD 566.80 million in 2025 and is estimated at USD 630.18 million in 2026, forecast to reach USD 1,635.92 million by 2035, expanding at an 11.18% CAGR between 2026 and 2035. Articulated robots dominate the market by robot type, reflecting sustained deployment across food and beverage and metals manufacturing lines.
In unit terms, deployed robot volume is estimated at thousand units in 2025 and 8 thousand units in 2026, rising to 24 thousand units by 2035 at a 12.70% CAGR between 2026 and 2035, a faster expansion rate than the value CAGR that reflects rising deployment of lower-cost collaborative and mobile robots across Australian manufacturing and logistics facilities.
We observed that market growth is supported by persistent manufacturing labor shortages, growing adoption of collaborative robots among small and mid-sized manufacturers, and continued government-backed investment in robotics and automation capability under Australia’s National Robotics Strategy through 2035.
|
Key Takeaways |
|
By Robot Type: Articulated Robots is the dominant segment, while Collaborative Robots is the fastest-growing segment. |
|
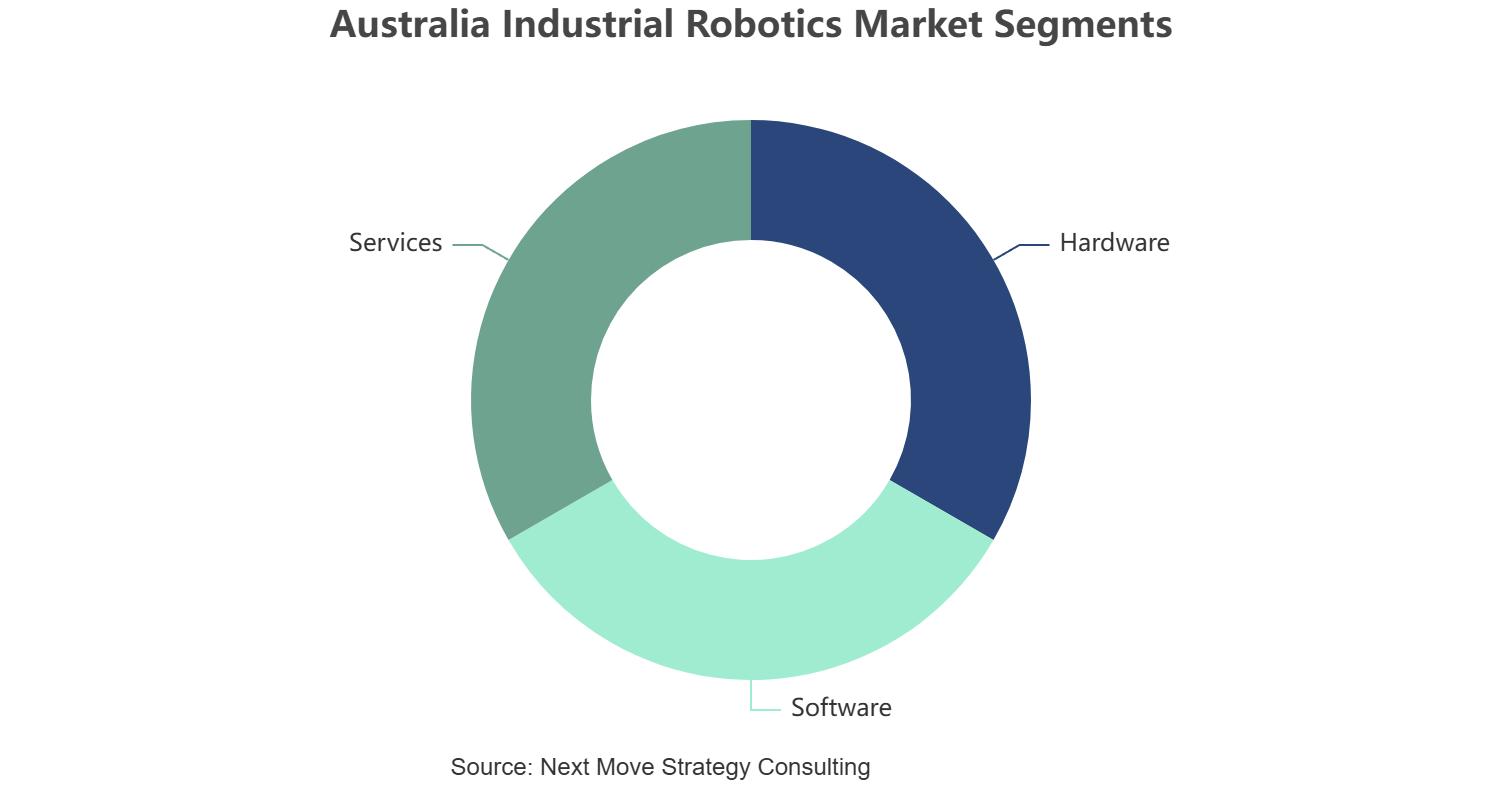
By Offering: Hardware is the dominant segment, while Software is the fastest-growing segment. |
|
By Application: Handling is the dominant segment, while Intralogistics and Transport is the fastest-growing segment. |
|
By Mounting Type: Floor Mounted is the dominant segment, while Wall-Mounted is the fastest-growing segment. |
|
By Mobility: Stationary Robots is the dominant segment, while Mobile Robots is the fastest-growing segment. |
|
By Payload Capacity: Medium Payload 20 kg to 100 kg is the dominant segment, while Low Payload Up to 20 kg is the fastest-growing segment. |
|
By End User: Food and Beverages Industry is the dominant segment, while Logistics and Warehousing is the fastest-growing segment. |
Market Opportunity: The Australia industrial robotics market is expected to create an absolute dollar opportunity of USD 1,005.74 million between 2026 and 2035, presenting significant investment potential across collaborative robotics, autonomous mobile robots, and warehouse and logistics automation segments.
According to NMSC’s analysis, companies are increasingly investing in cobot deployment and system integration capacity to address Australia’s manufacturing labor shortages, strengthening their competitive position in the Australia industrial robotics market through 2035.
Regulatory Framework Impacting the Australia Industrial Robotics Industry
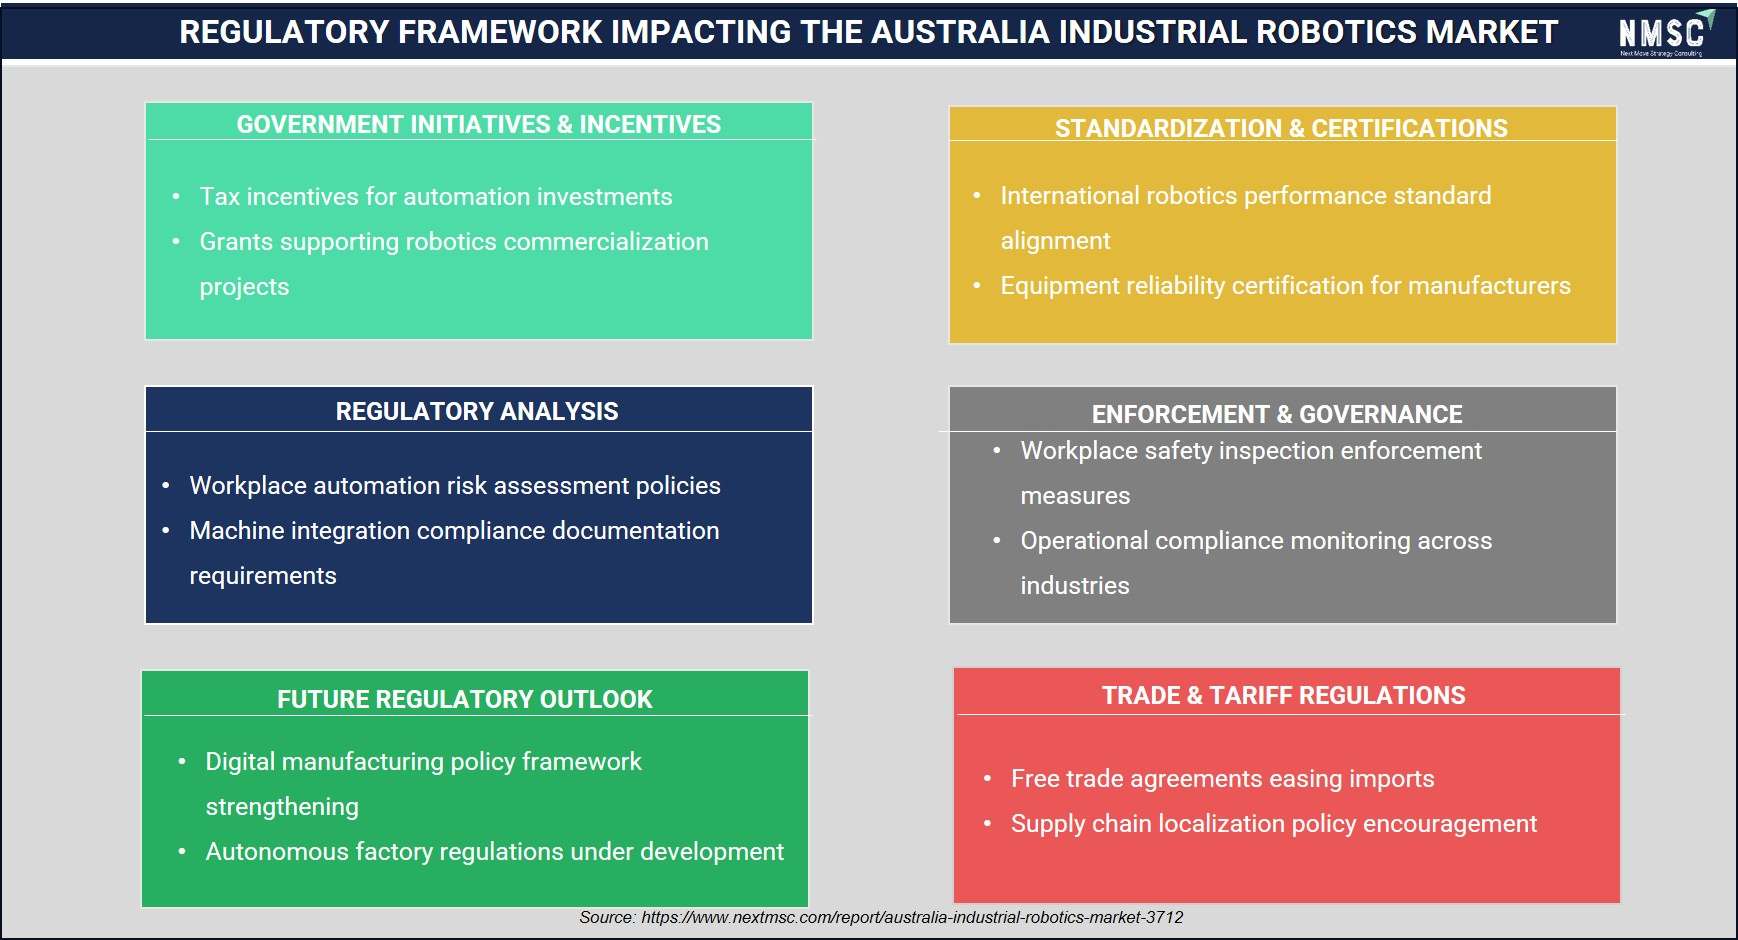
Based on NMSC’s research, we found that the regulatory framework influencing the Australia industrial robotics Industry promotes automation through tax incentives, commercialization grants, and internationally aligned certification standards. Additionally, workplace safety regulations, compliance documentation, and governance measures reinforce operational reliability, while evolving digital manufacturing policies, autonomous factory regulations, and supportive trade agreements encourage innovation, responsible robotics deployment, and long-term industrial competitiveness.
What Does the Australia Industrial Robotics Market Encompass?
The Australia industrial robotics market report encompasses articulated, SCARA, Cartesian and gantry, delta, collaborative, and mobile robotic systems deployed across handling, welding, assembly, dispensing, processing, and inspection operations. Our assessment indicates that the market includes hardware components such as robot arms, controllers, end effectors, and vision systems, alongside programming software and system integration services delivered by both multinational manufacturers and local integrators serving Australia’s food and beverage, metals, logistics, and pharmaceutical manufacturing base.
The Australian Government’s Department of Industry, Science and Resources shapes robotics policy through the National Robotics Strategy and the Industry Growth Program, which supports capability development and technology adoption. We observed that manufacturers are increasingly investing in collaborative robots and warehouse automation to offset persistent labor shortages and rising wage costs. NMSC’s analysis indicates that the National Reconstruction Fund and related advanced manufacturing initiatives continue to reshape technology adoption and competitive positioning across the market.
|
Parameters |
Details |
|
Market Size in 2025 |
USD 566.80 Million |
|
Market Size in 2026 |
USD 630.18 Million |
|
Revenue Forecast in 2035 |
USD 1,635.92 Million |
|
Growth Rate |
CAGR of 11.18% from 2026 to 2035 |
|
Market Volume in 2025 |
7 Thousand Units |
|
Market Volume in 2026 |
8 Thousand Units |
|
Volume Forecast in 2035 |
24 Thousand Units |
|
Volume Growth Rate |
CAGR of 12.70% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Revenue (USD Million) |
|
Companies Profiled |
15 |
|
Market Share |
Available for Top 10 Companies |
Key Emerging Trends
Based on research conducted by NMSC, we found that four structural trends are reshaping robot deployment, policy support, and competitive dynamics across the Australia industrial robotics market.
How Is the National Robotics Strategy Accelerating Automation Adoption?
The Australian Government’s National Robotics Strategy, published by the Department of Industry, Science and Resources, is reshaping investment priorities across national capability, adoption, and skills development. We observed that the strategy complements the Future Made in Australia plan and the A$15 billion National Reconstruction Fund, which supports capability development in robotics and advanced manufacturing. This shift is directing capital and grant funding, including Industry Growth Program awards, toward local robotics adoption projects.
Why Are Collaborative Robots Gaining Traction Among Small and Mid-Sized Manufacturers?
Collaborative robots are increasingly deployed by small and mid-sized Australian manufacturers that previously lacked capital or floor space for traditional caged automation. Our findings suggest that cobots are being adopted for machine tending, packaging, and palletizing tasks without extensive safety fencing. This trend is expanding automation beyond large-tier manufacturers into food and beverage and general metals fabrication operations across Australia.
How Is Warehouse and Logistics Automation Transforming Intralogistics Operations?
Growing e-commerce volumes and warehouse labor constraints are accelerating deployment of autonomous mobile robots and automated guided vehicles across Australian distribution centers. We observed that logistics and warehousing operators are integrating fleet management software to coordinate multi-robot deployments without extensive custom programming. This trend is strengthening intralogistics efficiency and reducing dependency on manual material handling across Australian fulfillment and distribution facilities.
What Role Does Field Robotics Expertise Play in Broader Industrial Automation?
Australia’s established field robotics expertise in mining, ports, and logistics is increasingly informing industrial automation deployment in general manufacturing settings. Our analysis indicates that local robotics companies are leveraging capability built in remote and autonomous operations to support manufacturing automation projects. This trend is reinforcing Australia’s position as a source of applied robotics expertise beyond its traditional resources sector strengths.
Growth Drivers and Restraints
Growth Catalyst and Risk Assessment Matrix
|
Factors |
Type |
(+/-) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Persistent manufacturing and warehousing labor shortages accelerating adoption of collaborative and autonomous mobile robots |
Driver |
+2.75% |
Australia (nationwide; strongest in Victoria and New South Wales) |
2026–2033 |
|
Government-backed National Robotics Strategy and Industry Growth Program funding supporting automation capability development |
Driver |
+2.30% |
Australia (nationwide) |
2026–2031 |
|
Expanding e-commerce and warehouse automation demand increasing deployment of AMRs and AGVs in logistics operations |
Driver |
+2.05% |
Australia (strongest in New South Wales and Queensland distribution hubs) |
2026–2032 |
|
Rising adoption of collaborative robots among small and mid-sized food and beverage manufacturers |
Driver |
+1.70% |
Australia (strongest in Victoria and South Australia) |
2026–2033 |
|
National Reconstruction Fund capital supporting advanced manufacturing and robotics capability scale-up |
Driver |
+1.25% |
Australia (nationwide) |
2026–2034 |
|
High equipment import costs and reliance on overseas robot manufacturers limiting price competitiveness for smaller manufacturers |
Restraint |
−1.45% |
Australia (nationwide; strongest among SMEs) |
2026–2029 |
|
Shortage of qualified robotics integration and maintenance technicians constraining deployment pace outside major cities |
Restraint |
−1.15% |
Australia (nationwide; strongest outside metropolitan areas) |
2026–2030 |
|
Declining domestic automotive manufacturing base limiting large-scale automotive robot procurement |
Restraint |
−0.80% |
Australia (nationwide) |
2026–2028 |
What Is the Primary Growth Driver of the Australia Industrial Robotics Market?
Persistent manufacturing and warehousing labor shortages form the primary growth driver of the Australia industrial robotics market. According to the Department of Industry, Science and Resources, adoption of advanced robotics and automation technologies could add billion per annum to Australia’s GDP while addressing workforce shortages across critical sectors. We observed that manufacturers are prioritizing collaborative and mobile robot deployment to sustain production output amid tight labor markets.
How Is Government Policy Driving Australia Industrial Robotics Market Growth?
The Australian Government’s National Robotics Strategy and associated funding programs are accelerating industrial automation adoption nationwide. Our assessment indicates that the Department of Industry, Science and Resources has awarded A$7.4 million in Industry Growth Program funding toward robotics capability projects, part of a broader A$392 million program supporting advanced manufacturing. This policy support is reinforcing demand for locally integrated robotics solutions across Australian production and logistics facilities.
What Is Restraining Australia Industrial Robotics Market Expansion?
High equipment imports costs and a shortage of qualified integration technicians continue to restrain market expansion, particularly among small and mid-sized manufacturers outside major metropolitan areas. We found that Australia’s declining domestic automotive manufacturing base limits large-scale automotive robot procurement compared with markets that retain substantial vehicle assembly operations. These constraints slow automation adoption despite strong underlying demand for productivity improvement.
Segmentation Analysis
By Robot Type Insights
How Is the Australia Industrial Robotics Market Segmented by Robot Type?
Based on robot type, the Australia industrial robotics market is segmented into articulated robots, SCARA robots, Cartesian and gantry robots, delta robots, collaborative robots, autonomous mobile robots (AMRs), automated guided vehicles (AGVs), and other robots.
Articulated robots dominate the market, reflecting their versatility across handling, welding, and assembly applications in food and beverage and metals manufacturing, where multi-axis flexibility supports varied production tasks. Collaborative robots represent the fastest-growing segment as small and mid-sized manufacturers accelerate cobot deployment to offset persistent labor shortages without extensive safety infrastructure. SCARA and delta robots continue supporting packaging and assembly tasks, while autonomous mobile robots and automated guided vehicles expand steadily within intralogistics operations across Australian distribution and manufacturing facilities.
By End User Insights
How Is the Australia Industrial Robotics Market Segmented by End User?
Based on end user, the market is segmented into automotive, electrical and electronics, metals and machinery, food and beverages, pharmaceuticals and medical devices, plastics rubber and chemicals, logistics and warehousing, and other industries.
The food and beverages industry dominates the market, reflecting its position as one of Australia’s largest manufacturing subsectors and its reliance on handling, packaging, and palletizing automation. Logistics and warehousing is the fastest-growing end user, supported by expanding e-commerce volumes and rising deployment of autonomous mobile robots across distribution centers. Metals and machinery, pharmaceuticals, and plastics and chemicals continue to broaden robotics adoption as automation extends across Australia’s diversified manufacturing base.
Growth Opportunities
Our analysis shows that three forward-looking opportunities stand out for stakeholders operating in the Australia industrial robotics market over the 2026–2035 forecast period.
How Can Collaborative Robot Financing Models Unlock New Growth Opportunities?
Flexible financing and robotics-as-a-service models present a significant opportunity for providers targeting small and mid-sized manufacturers constrained by capital budgets. Companies offering leasing or subscription-based collaborative robot deployment can accelerate cobot adoption across food and beverage and general metals fabrication segments previously priced out of automation investment.
Where Does Warehouse Automation Create New Demand for Fleet Management Software?
Expanding deployment of autonomous mobile robots and automated guided vehicles across Australian distribution centers creates opportunity for fleet management and orchestration software providers. Companies investing in software capable of coordinating multi-vendor robot fleets can strengthen customer retention while supporting the country’s growing logistics and warehousing automation requirements.
How Can System Integration Services Benefit from Government-Backed Automation Programs?
Growing government support through the Industry Growth Program and National Reconstruction Fund is creating demand for local system integration and installation services. Companies that expand technician training pipelines and regional service coverage can capture higher-value integration contracts as manufacturers seek turnkey automation deployment support across Australia.
Competitive Landscape
We observed that the Australia industrial robotics market features a highly competitive landscape, with global industrial robotics manufacturers competing alongside specialized collaborative robot providers and regional system integrators across the industry.
|
Key Takeaways |
Details |
|
Market Structure |
Highly competitive, with global manufacturers holding significant share alongside specialized collaborative robot providers and independent system integrators serving food and beverage, metals, and logistics operations. |
|
Innovation Focus |
Collaborative robotics, warehouse automation, fleet management software, and vision-guided handling dominate current product development strategies across leading manufacturers. |
|
M&A Activity |
Strategic distribution partnerships, local integration capacity investment, and technology partnerships continue to shape competitive positioning as companies strengthen presence across Australia’s manufacturing and logistics corridors. |
How Do Companies Compete in the Australia Industrial Robotics Market?
Companies compete primarily through automation reliability, local integration support, and total cost of ownership. Leading manufacturers such as ABB Australia Pty Limited, FANUC Australia Pty Ltd, and Yaskawa Australia Pty Ltd leverage extensive service networks and established manufacturing relationships to maintain market leadership, while providers including KUKA Australia Pty Ltd and Omron Electronics Pty Ltd differentiate through application-specific engineering and rapid deployment capabilities across food and beverage and metals manufacturing.
Which Competitive Archetypes Dominate the Australia Industrial Robotics Market?
Two primary competitive archetypes characterize the market. The first comprises diversified multinational robotics manufacturers offering comprehensive portfolios across articulated, SCARA, and Cartesian systems, including ABB Australia Pty Limited, FANUC Australia Pty Ltd, KUKA Australia Pty Ltd, and Mitsubishi Electric Australia Pty Ltd. The second includes collaborative and specialty robotics providers such as Universal Robots Australia Pty Ltd and Doosan Robotics Australia Pty Ltd, which focus on flexible deployment and application-specific automation for smaller manufacturers.
How Are Companies Differentiating Through Innovation in the Australia Industrial Robotics Industry?
Innovation strategies increasingly focus on collaborative robotics, vision-guided handling, and cloud-connected fleet management software for warehouse automation. Companies are investing in application-specific end effectors and simplified programming interfaces to reduce integration complexity for first-time automation adopters. Our analysis indicates that manufacturers combining hardware reliability with software-enabled fleet visibility are strengthening competitive positioning across Australia’s expanding industrial base.
What M&A and Expansion Activity Is Shaping the Australia Industrial Robotics Market?
Strategic distribution partnerships, local integration capacity expansion, and technical training investments continue to shape competition across the market. Leading companies are strengthening service footprints near major manufacturing and logistics hubs, enabling faster deployment support and closer alignment with expanding food and beverage, metals, and warehousing automation requirements across Australia.
Key Market Players
Our assessment indicates that the following 15 companies are actively shaping product innovation, service expansion, and competitive dynamics within the Australia industrial robotics industry.
-
FANUC Australia Pty Ltd
-
Yaskawa Australia Pty Ltd
-
KUKA Australia Pty Ltd
-
Omron Electronics Pty Ltd
-
Kawasaki Heavy Industries Australia Pty Ltd
-
Stäubli Australia Pty Ltd
-
DENSO Australia Pty Ltd
-
Doosan Robotics Australia Pty Ltd
-
Epson Australia Pty Ltd
-
Mitsubishi Electric Australia Pty Ltd
-
Panasonic Australia Pty Ltd
-
Yamaha Motor Australia Pty Ltd
-
Mecademic Australia Pty Ltd
PORTER’S Five Forces Analysis of the Australia Industrial Robotics Industry
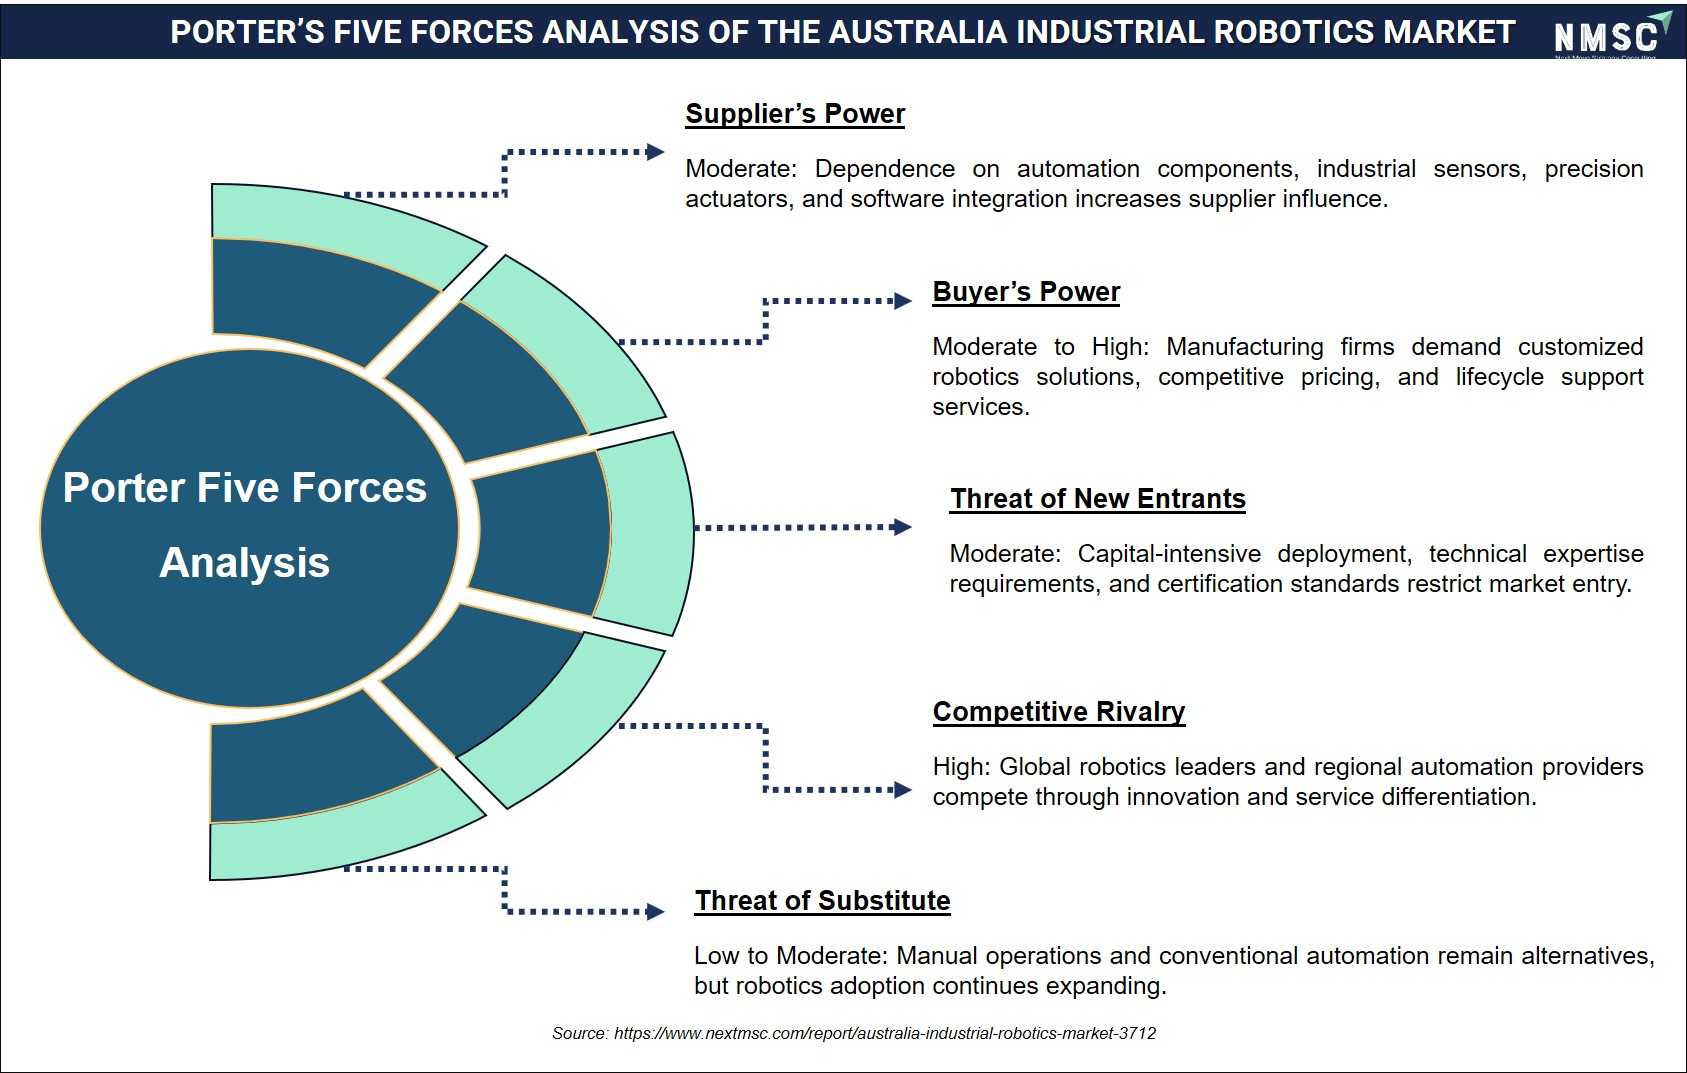
Our assessment indicates that the Australia industrial robotics Industry reflects moderate supplier influence driven by specialized automation components, while buyers seek customized robotic solutions and lifecycle support. Moreover, certification requirements and capital-intensive deployment create barriers for new entrants, whereas global competition fuels continuous innovation. At the same time, conventional automation remains a partial substitute, supporting a balanced competitive environment as robotics adoption expands across industrial applications.
Latest Developments
We found that recent developments within the Australia industrial robotics market concentrate on government policy support, robotics capability funding, and expanded automation adoption across manufacturing sectors.
|
Date |
Event |
|
Jun 2026 |
OMRON Automation and Robotics Oceania signed a Memorandum of Understanding with the University of Canberra, Australia, to expand collaboration in robotics, artificial intelligence, digital twins and advanced manufacturing. The agreement also strengthens deployment of OMRON technologies within the University's Collaborative Robotics Lab. |
|
Mar 2025 |
ABB Robotics Australia appointed Australian automation specialist Vision AI as its newest Authorized Value Provider. The partnership expands ABB's local robotics integration network, enabling broader delivery of robotic automation and machine vision solutions for Australian manufacturers through an officially recognized domestic partner. |
Investment Opportunities
What Capital Inflows Are Targeting the Australia Industrial Robotics Market?
Capital inflows into the Australia industrial robotics market are increasingly directed toward collaborative robotics, warehouse automation, and local system integration capacity. The Australian Government’s National Reconstruction Fund continues to channel capital toward robotics and advanced manufacturing capability. We observed that investors favor companies demonstrating strong service coverage, established manufacturing relationships, and scalable integration capabilities as indicators of long-term growth potential.
How Is Infrastructure Investment Supporting the Australia Industrial Robotics Market?
Infrastructure investment is expanding manufacturing capacity, technician training facilities, and regional service networks across Australia’s industrial regions. Our findings suggest that companies are investing in local warehousing, spare-parts logistics, and integration workshops to reduce deployment lead times. These investments strengthen manufacturers’ ability to support rapidly expanding food and beverage, logistics, and general manufacturing automation requirements nationwide.
What ESG Considerations Are Shaping Investment Decisions in the Australia Industrial Robotics Market?
Environmental, social, and governance considerations are becoming integral to investment decisions, with workplace safety compliance, energy-efficient automation, and workforce reskilling emerging as key priorities. We found that the National Robotics Strategy explicitly emphasizes responsible and inclusive robotics development, encouraging investors to favor companies demonstrating measurable progress in safety compliance and structured technician training programs supporting long-term operational resilience.
Key Benefits for Stakeholders
How Does This Report Benefit Enterprise and Industry Leaders?
Enterprise and industry leaders gain access to validated market segmentation, competitive benchmarking, and technology adoption analysis that support strategic planning and automation investment decisions across the Australia industrial robotics market. Our analysis shows that detailed assessments of robot type, application, and end-user trends help companies identify high-growth opportunities and strengthen long-term manufacturing competitiveness.
How Does This Report Benefit Investors and Financial Analysts?
Investors and financial analysts benefit from consistent market size estimates, growth forecasts, and competitive assessments supporting investment evaluation across the Australia industrial robotics market. We observed that the report’s detailed analysis of collaborative robotics, warehouse automation, and government-backed funding programs enables stakeholders to identify companies with the strongest long-term growth potential through 2035.
How Does This Report Benefit Technology Vendors and Product Teams?
Technology vendors and product development teams gain valuable insights into emerging innovation trends, including collaborative robotics, warehouse automation, and fleet management software transforming Australia’s industrial automation landscape. Our findings suggest that this analysis helps research and development teams prioritize product pipelines and align offerings with evolving manufacturer requirements.
Key Market Segments
By Robot Type
-
Articulated Robots
-
SCARA Robots
-
Cartesian and Gantry Robots
-
Delta Robots
-
Collaborative Robots
-
Autonomous Mobile Robots (AMRs)
-
Automated Guided Vehicles (AGVs)
-
Other Robots
By Offering
-
Hardware
-
Robot Arms
-
Controllers
-
End Effectors and Grippers
-
Sensors and Vision Systems
-
-
Software
-
Control and Programming Software
-
Simulation and Offline Programming Software
-
Fleet Management Software
-
-
Services
-
System Integration and Installation
-
Maintenance and Support
-
Training and Consulting
-
By Application
-
Handling
-
Pick and Place
-
Machine Tending
-
Palletizing and Depalletizing
-
-
Welding and Soldering
-
Assembly and Disassembly
-
Dispensing
-
Painting
-
Adhesive and Sealant Application
-
-
Processing
-
Cutting and Machining
-
Grinding and Polishing
-
-
Cleanroom Operations
-
Inspection and Quality Control
-
Packaging and Labeling
-
Intralogistics and Transport
By Mounting Type
-
Floor Mounted
-
Wall-Mounted
-
Ceiling Mounted
-
Rail Mounted
By Mobility
-
Stationary Robots
-
Mobile Robots
By Payload Capacity
-
Low Payload Up to 20 kg
-
Medium Payload 20 kg to 100 kg
-
High Payload 100 kg to 500 kg
-
Heavy Duty Payload Over 500 kg
By End User
-
Automotive Industry
-
Electrical and Electronics Industry
-
Metals and Machinery Industry
-
Food and Beverages Industry
-
Pharmaceuticals and Medical Devices Industry
-
Plastics Rubber and Chemicals Industry
-
Logistics and Warehousing
-
Other Industries
Conclusion and Recommendations
What Is the Long-Term Outlook for the Australia Industrial Robotics Market?
The long-term outlook for the Australia industrial robotics market remains positive, supported by persistent labor shortages, sustained government policy backing, and continued adoption of collaborative and warehouse automation. We observed that growing deployment of autonomous mobile robots and fleet management software will continue driving market expansion from USD 630.18 million in 2026 to USD 1,635.92 million by 2035 across handling, assembly, and intralogistics applications.
What Strategic Positioning Should Robotics Companies Pursue?
Manufacturers should prioritize investments in collaborative robotics, local system integration capacity, and technician training programs while strengthening service coverage near major manufacturing and logistics hubs. Our assessment indicates that companies expanding flexible financing models and application-specific automation solutions will be well positioned to capture growing demand from small and mid-sized manufacturers across Australia.
How Attractive Is the Australia Industrial Robotics Market for New Investment?
The Australia industrial robotics market presents an attractive investment opportunity, supported by a projected 11.18% CAGR between 2026 and 2035, sustained government funding programs, and rising automation adoption across multiple end-user industries. We found that investment potential is particularly strong for companies focused on collaborative robotics, warehouse automation, and fleet management software capable of capitalizing on Australia’s expanding industrial base.
What Market Shifts and Key Risks Should Stakeholders Monitor?
Stakeholders should closely monitor high equipment import costs, persistent shortages of qualified integration technicians, and the continued decline of Australia’s domestic automotive manufacturing base. Our analysis shows that companies unable to expand local service capacity or manage import cost exposure may face increasing competitive pressure within the market.
What Are the Key Growth Pathways for the Australia Industrial Robotics Market?
Key growth pathways include expanding collaborative robotics adoption among small and mid-sized manufacturers, accelerating warehouse and logistics automation, and strengthening system integration capacity supported by government funding programs. NMSC’s analysis indicates that companies combining local service depth with flexible financing models will be best positioned to capture the market’s projected growth through 2035.
About the Author
 Mihul Sharma
— Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.

SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.




 Speak to Our Analyst