Data Center Infrastructure Market Global Industry Analysis and Forecast (2026-2035)

Data Center Infrastructure Market size was USD 269.86 Billion in 2025, projected to reach USD 795.17 Billion by 2035, growing at a CAGR of 10.3% from 2026 to 2035. Key drivers include rising AI workload deployment and GPU accelerator demand, expanding hyperscale capacity investments, and increasing demand for integrated power, cooling, and compute infrastructure, with Europe leading the market.

Download Free Sample PDF
Base Year (2025)
$269.86 Billion
Forecast (2035)
$795.17 Billion
CAGR (2026-2035)
10.3%
Top Country
Europe

What Is the Data Center Infrastructure Market Size?

The global data center infrastructure market size was valued at USD 269.86 billion in 2025 and is estimated at USD 328.11 billion in 2026, forecast to reach USD 795.17 billion by 2035, expanding at a 10.3% CAGR between 2026 and 2035. Europe leads with approximately a 38% share, while Hardware dominates all other offerings with approximately a 64% share.

We observed that growth is broad-based across every segmentation axis, with hyperscale capacity expansion and Tier IV facility construction driving the dominant structural shifts through 2035.

Data Center Infrastructure Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $269.86 Billion
2025
2026 $328.11 Billion
2026
2027 $361.91 Billion
2027
2028 $399.18 Billion
2028
2029 $440.30 Billion
2029
2030 $485.65 Billion
2030
2031 $535.67 Billion
2031
2032 $590.84 Billion
2032
2033 $651.70 Billion
2033
2034 $718.83 Billion
2034
2035 $795.17 Billion
2035

Key Takeaways

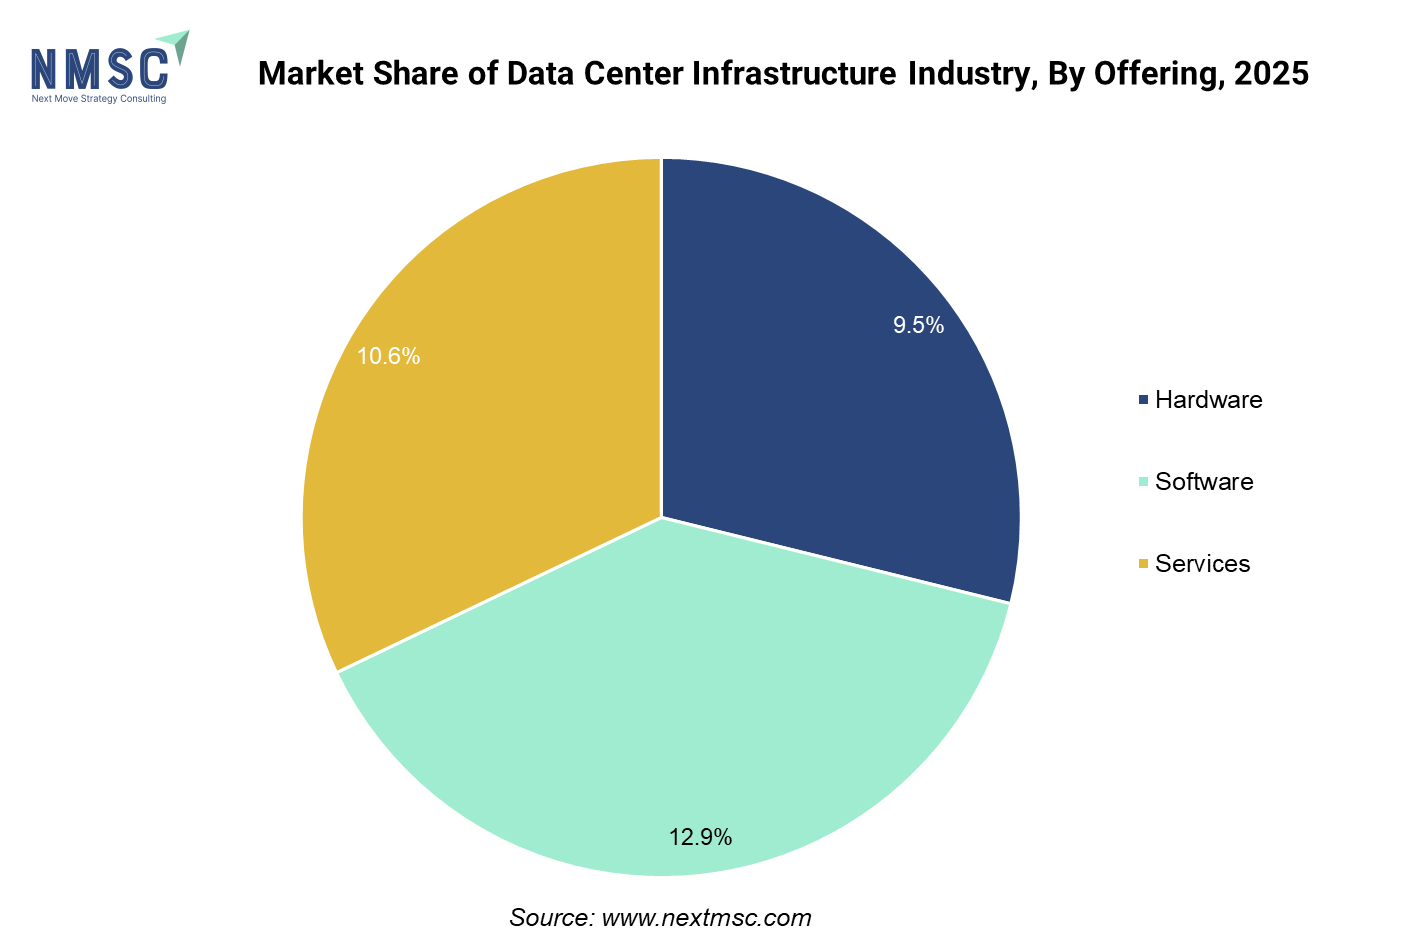
By Offering: Hardware held the largest share of approximately 64% (USD 171.99 billion) in 2025; Software is the fastest-growing segment at 12.9% CAGR from 2026–2035.

By Data Center Type: Enterprise Data Centers held the largest share of approximately 38% (USD 102.19 billion) in 2025; Cloud Data Centers is the fastest-growing segment at 12.96% CAGR from 2026–2035.

By Facility Size: 1–10 MW held the largest share of approximately 22% (USD 59.71 billion) in 2025; Above 51 MW is the fastest-growing segment at 14.6% CAGR from 2026–2035.

By Facility Location: Core held the largest share of approximately 82% (USD 221.72 billion) in 2025; Edge is the fastest-growing segment at 14.2% CAGR from 2026–2035.

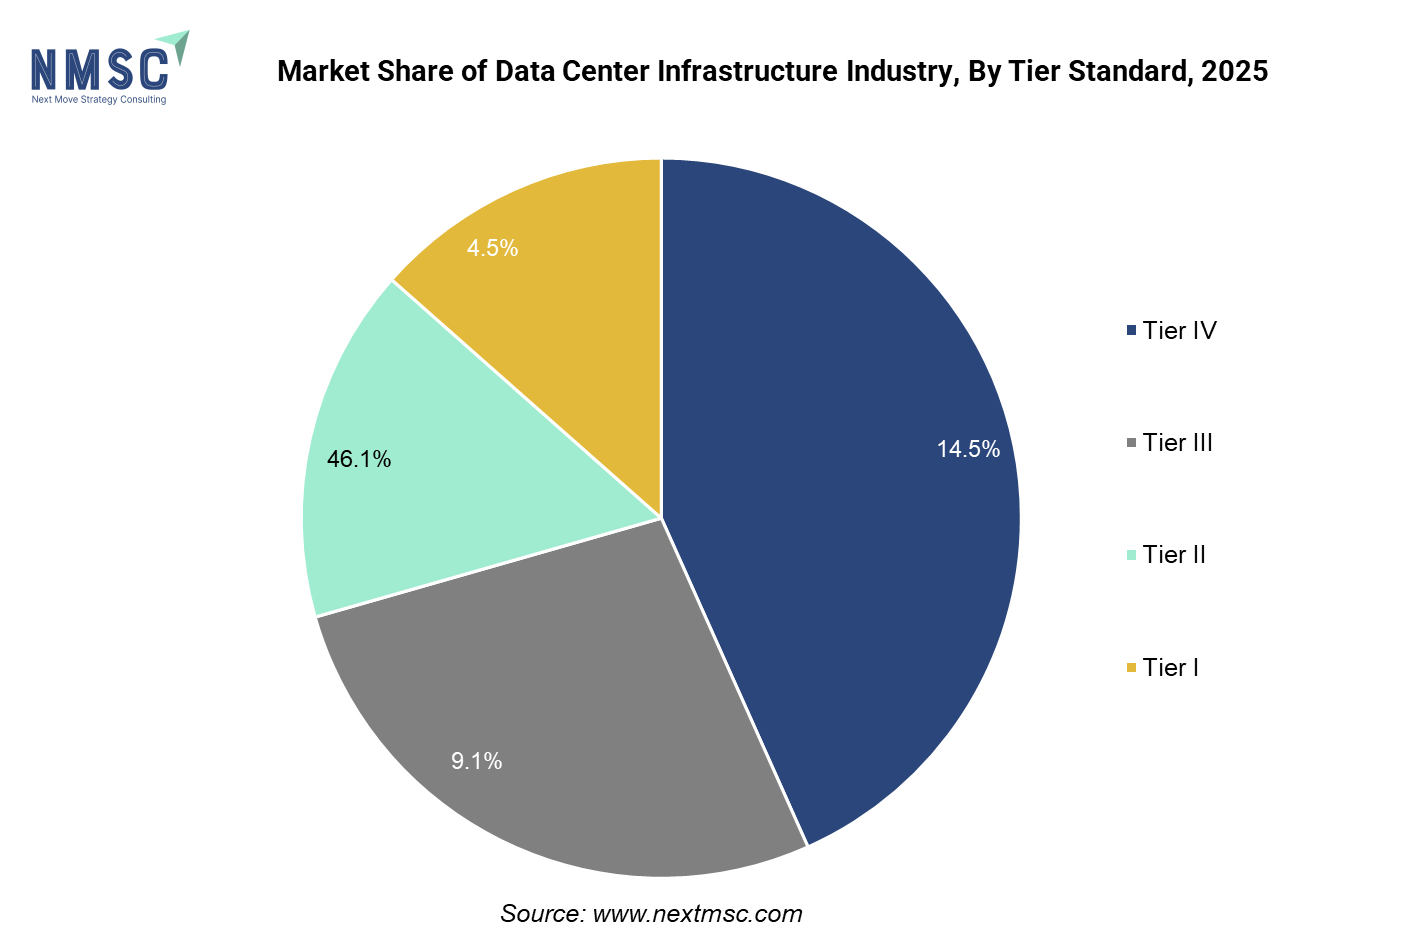
By Tier Standard: Tier III held the largest share of approximately 41% (USD 111.28 billion) in 2025; Tier IV is the fastest-growing segment at 14.5% CAGR from 2026–2035.

By End User: Cloud Service Providers held the largest share of approximately 11% (USD 29.66 billion) in 2025; Cloud Service Providers is also the fastest-growing segment at 13.8% CAGR from 2026–2035.

Dominant Region: Europe dominated with approximately 38% revenue share (USD 102.08 billion) in 2025.

Fastest-Growing Region: Middle East & Africa is expected to register the highest CAGR of 13.5% during 2026–2035.

Dominant Country: The U.S. led with approximately USD 66.93 billion in 2025.

Fastest-Growing Country: Mexico is the fastest-growing country at approximately 13.1% CAGR from 2026–2035.

Ecosystem Analysis of the Data Center Infrastructure Industry

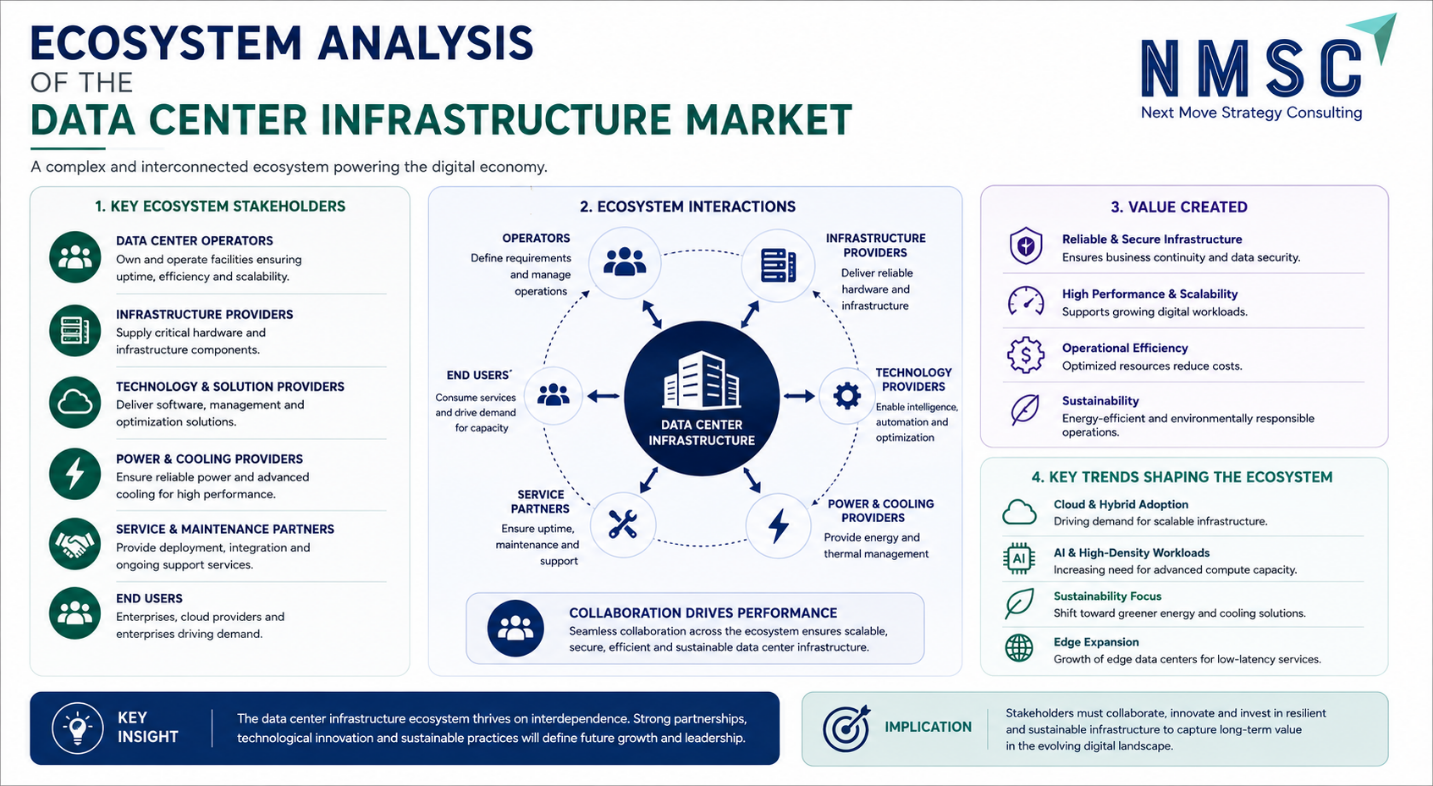
The above infographic offers a detailed ecosystem analysis of the data center infrastructure market, mapping out key stakeholders from operators and infrastructure providers to end users. It illustrates how seamless collaboration across these interconnected roles drives performance, scalability, and operational efficiency. The analysis further highlights the value created through reliable, sustainable infrastructure and identifies major trends shaping the industry, such as AI-driven workloads and edge expansion. Ultimately, the key insight emphasizes that technological innovation and strong partnerships are essential for future growth and resilience in the digital landscape .

What Does the Data Center Infrastructure Market Encompass?

The data center infrastructure market encompasses the hardware, software, and services required to build, power, cool, and operate facilities that house compute, storage, and networking equipment across enterprise, colocation, and cloud data center environments. Our assessment indicates that the scope spans compute, network, power, cooling, and physical infrastructure hardware alongside DCIM, monitoring, and infrastructure AIOps software, supplied to operators ranging from hyperscale cloud service providers to enterprise IT departments across every major end-user vertical.
Regulatory frameworks such as the European Union's Energy Efficiency Directive increasingly shape facility power usage effectiveness reporting requirements, while grid interconnection queue policies in the United States influence data center siting decisions. We observed that technology adoption is shifting toward direct-to-chip and immersion data center cooling systems capable of supporting high-density AI accelerator racks, a structural change that NMSC's analysis indicates is redefining facility design standards across the data center infrastructure market.

Market Drivers & Dynamics

Interactive Dataset
Rising AI workload deployment and GPU accelerator demand driver +2.9% Global 2026–2035
Expanding hyperscale cloud service provider capacity investment driver +2.3% North America, Asia-Pacific, Europe 2026–2033
Growing colocation and interconnection demand from enterprises driver +1.7% Global 2026–2035
Rising edge data center deployment for latency-sensitive applications driver +1.3% North America, Europe, Asia-Pacific 2026–2034
Expanding data center construction across Middle East & Africa driver +1.0% Middle East & Africa 2026–2035
Growing adoption of DCIM and infrastructure AIOps software driver +0.8% Global 2026–2032
Grid interconnection delays and power availability constraints restraint −1.6% North America, Europe 2026–2035
High capital costs for liquid cooling and Tier IV facility construction restraint −1.1% Global 2026–2033
Water usage and environmental permitting restrictions restraint −0.7% North America, Europe 2026–2032
Supply chain constraints for advanced power and cooling equipment restraint −0.5% Global 2028–2035
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Data Center Infrastructure Market?

Rising AI workload deployment and GPU accelerator demand are the primary drivers of the market. The U.S. Department of Energy continues to track sustained growth in data center electricity consumption tied to AI infrastructure buildout, reflecting the scale of capital investment flowing into compute-dense facilities. We observed that this AI-driven demand, reinforced by continued hyperscale capital expenditure disclosures, continues to anchor consistent procurement of compute, power, and cooling infrastructure across cloud service providers and colocation operators globally.

How Is Hyperscale Capacity Expansion Driving Market Growth?

Expanding hyperscale cloud service provider capacity investment is accelerating demand for integrated power, cooling, and compute infrastructure across new and retrofitted facilities. Vertiv Holdings' continued expansion of its power and thermal management product portfolio reflects the pace at which infrastructure vendors are scaling capacity to serve hyperscale data center construction pipelines. Our assessment indicates that this demand-side pressure is compressing equipment lead times across the global data center supply chain.

Growth Inhibitors

What Is Restraining Data Center Infrastructure Market Expansion?

Grid interconnection delays and power availability constraints restrain broader facility development, particularly in established markets where transmission capacity has not kept pace with data center power demand growth. The U.S. Federal Energy Regulatory Commission continues to address lengthening interconnection queues that delay new facility power access in high-demand regions. We found that high capital costs for liquid cooling and Tier IV facility construction further slow deployment timelines for operators pursuing the highest reliability and density tiers.

What Are the Growth Opportunities?

How Can Vendors Capture Liquid Cooling Retrofit Demand?

Liquid cooling retrofit projects represent a whitespace opportunity for vendors developing modular cooling systems compatible with existing air-cooled facility footprints. Vendors that commercialize retrofit-friendly direct-to-chip and rear-door heat exchanger systems stand to capture recurring procurement as operators upgrade legacy Tier III facilities to support higher-density AI accelerator racks without full facility reconstruction.
Where Does Edge Facility Standardization Create New Infrastructure Demand?

Standardized, prefabricated edge facility designs represent an underpenetrated opportunity for vendors developing modular infrastructure packages optimized for rapid deployment at telecommunications and retail edge locations. Companies that qualify pre-engineered power, cooling, and physical infrastructure kits for edge deployment can secure long-term supply agreements with telecommunications operators scaling distributed edge footprints.
How Can Infrastructure AIOps Platforms Expand Recurring Software Revenue?

Infrastructure AIOps and predictive analytics platforms create a sustained opportunity for vendors seeking recurring subscription revenue beyond one-time hardware sales. Early movers that bundle predictive maintenance and energy optimization algorithms with monitoring hardware can differentiate with hyperscale and colocation customers pursuing data-driven facility operations across globally distributed infrastructure portfolios.
Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Hardware
Compute Infr
Servers
Accelerators
Storage Syst
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Hardware $10.0 USD Billion $40.0 USD Billion 15.0%
Compute Infrastructure $17.1 USD Billion $51.1 USD Billion 9.0%
Servers $24.2 USD Billion $62.2 USD Billion 19.0%
Accelerators $31.3 USD Billion $73.3 USD Billion 21.0%
Storage Systems $38.4 USD Billion $84.4 USD Billion 26.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Offering.

Unlock Full Data

Which Offering Segment Dominates the Data Center Infrastructure Market?

Hardware led the market with USD 171.99 billion in 2025, supported by sustained capital investment in compute, network, power, cooling, and physical infrastructure equipment across new facility construction. Our findings suggest that Software is the fastest-growing segment, registering a 12.9% CAGR from 2026 to 2035, as operators increasingly prioritize DCIM, monitoring, and infrastructure AIOps platforms to manage growing facility complexity and energy optimization requirements.

2025 (USD Billion)
2035 (USD Billion)
Enterprise D
Colocation D
Cloud Data C
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Enterprise Data Centers $10.0 USD Billion $40.0 USD Billion 24.0%
Colocation Data Centers $17.1 USD Billion $51.1 USD Billion 18.0%
Cloud Data Centers $24.2 USD Billion $62.2 USD Billion 8.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Data Center Type.

Unlock Full Data

Which Data Center Type Segment Leads Market Demand?

Enterprise Data Centers remained the leading data center type within the market, valued at USD 102.19 billion in 2025 on continued on-premises infrastructure investment across regulated and latency-sensitive industries. Based on research conducted by NMSC, we found that Cloud Data Centers is the fastest-growing segment, registering a 12.96% CAGR from 2026 to 2035, as enterprises accelerate workload migration toward cloud computing platforms operated by hyperscale providers.

2025 (USD Billion)
2035 (USD Billion)
Below 1 MW
1–10 MW
11–25 MW
26–50 MW
Above 51 MW
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Below 1 MW $10.0 USD Billion $40.0 USD Billion 21.0%
1–10 MW $17.1 USD Billion $51.1 USD Billion 11.0%
11–25 MW $24.2 USD Billion $62.2 USD Billion 21.0%
26–50 MW $31.3 USD Billion $73.3 USD Billion 27.0%
Above 51 MW $38.4 USD Billion $84.4 USD Billion 12.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Facility Size.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Core
Edge
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Core $10.0 USD Billion $40.0 USD Billion 27.0%
Edge $17.1 USD Billion $51.1 USD Billion 25.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Facility Location.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Tier I
Tier II
Tier III
Tier IV
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Tier I $10.0 USD Billion $40.0 USD Billion 8.0%
Tier II $17.1 USD Billion $51.1 USD Billion 10.0%
Tier III $24.2 USD Billion $62.2 USD Billion 8.0%
Tier IV $31.3 USD Billion $73.3 USD Billion 14.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Tier Standard.

Unlock Full Data

Which Tier Standard Segment Is Most Significant in the Data Center Infrastructure Industry ?

Tier III facilities remained the dominant tier standard across the market, reaching USD 111.28 billion in 2025 as this configuration balances redundancy and cost efficiency for the majority of colocation and enterprise deployments. Our analysis shows that Tier IV is the fastest-growing tier standard at a 14.5% CAGR from 2026 to 2035, reflecting hyperscale and mission-critical operators increasingly specifying fault-tolerant, concurrently maintainable infrastructure for AI and financial services workloads.

2025 (USD Billion)
2035 (USD Billion)
BFSI
Cloud Servic
Colocation P
Education
Energy & Uti
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
BFSI $10.0 USD Billion $40.0 USD Billion 26.0%
Cloud Service Providers $17.1 USD Billion $51.1 USD Billion 16.0%
Colocation Providers $24.2 USD Billion $62.2 USD Billion 18.0%
Education $31.3 USD Billion $73.3 USD Billion 8.0%
Energy & Utilities $38.4 USD Billion $84.4 USD Billion 23.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
North Americ
Canada
Mexico.
Europe: UK
Germany
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
North America: U.S. $10.0 USD Billion $40.0 USD Billion 10.0%
Canada $17.1 USD Billion $51.1 USD Billion 8.0%
Mexico. $24.2 USD Billion $62.2 USD Billion 18.0%
Europe: UK $31.3 USD Billion $73.3 USD Billion 8.0%
Germany $38.4 USD Billion $84.4 USD Billion 15.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Region.

Unlock Full Data

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the data center infrastructure market over the 2026–2035 forecast period.

How Can Vendors Capture Liquid Cooling Retrofit Demand?

Liquid cooling retrofit projects represent a whitespace opportunity for vendors developing modular cooling systems compatible with existing air-cooled facility footprints. Vendors that commercialize retrofit-friendly direct-to-chip and rear-door heat exchanger systems stand to capture recurring procurement as operators upgrade legacy Tier III facilities to support higher-density AI accelerator racks without full facility reconstruction.

Where Does Edge Facility Standardization Create New Infrastructure Demand?

Standardized, prefabricated edge facility designs represent an underpenetrated opportunity for vendors developing modular infrastructure packages optimized for rapid deployment at telecommunications and retail edge locations. Companies that qualify pre-engineered power, cooling, and physical infrastructure kits for edge deployment can secure long-term supply agreements with telecommunications operators scaling distributed edge footprints.

How Can Infrastructure AIOps Platforms Expand Recurring Software Revenue?

Infrastructure AIOps and predictive analytics platforms create a sustained opportunity for vendors seeking recurring subscription revenue beyond one-time hardware sales. Early movers that bundle predictive maintenance and energy optimization algorithms with monitoring hardware can differentiate with hyperscale and colocation customers pursuing data-driven facility operations across globally distributed infrastructure portfolios.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

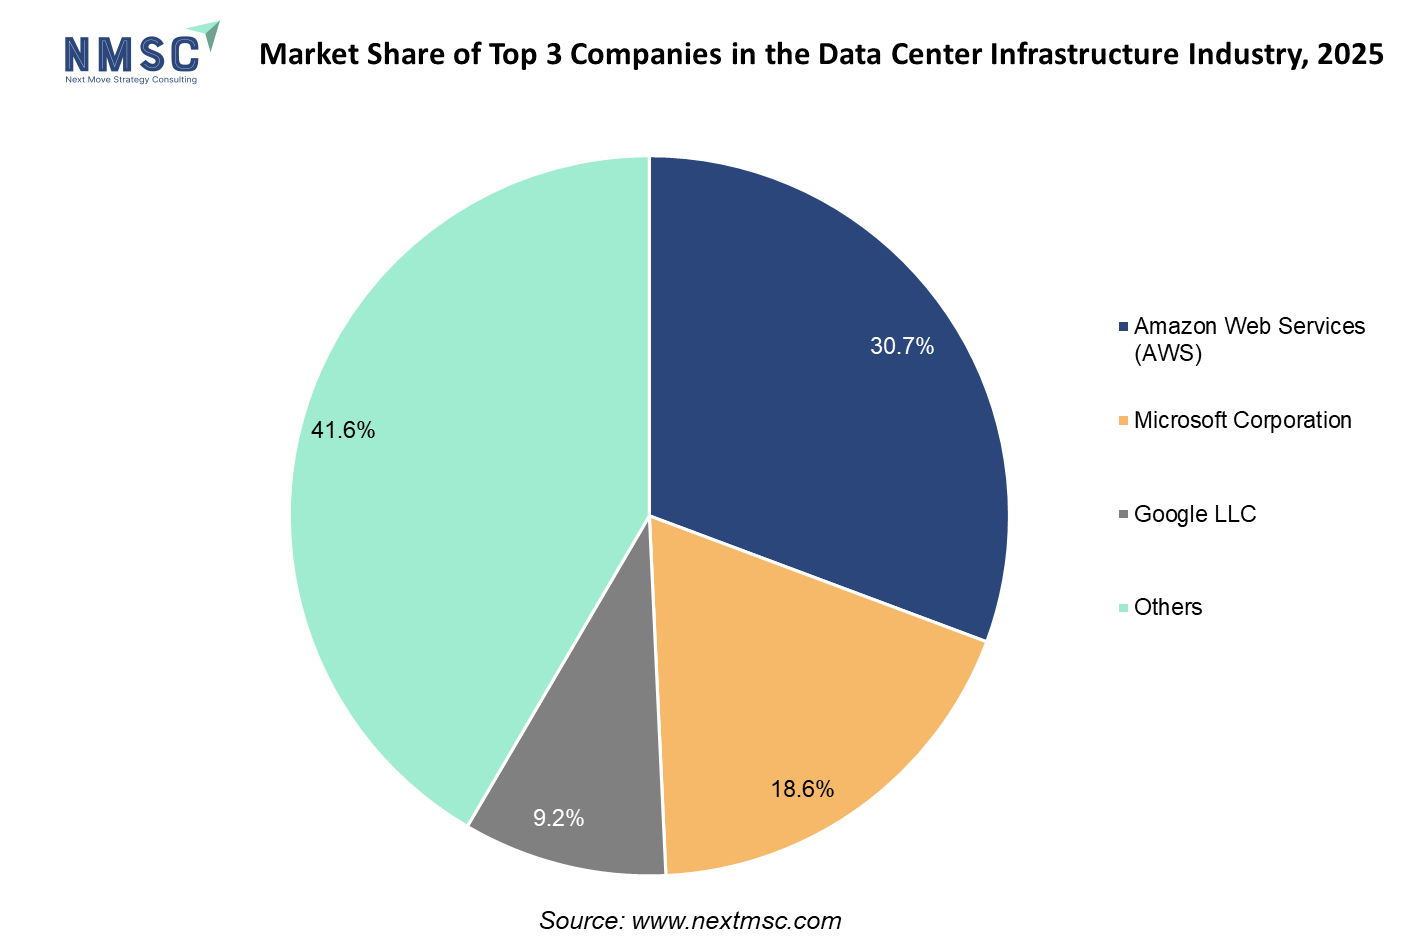
We observed that the data center infrastructure market features a moderately consolidated competitive landscape, with diversified power and cooling majors competing alongside compute and networking specialists on integration breadth, engineering support, and global fulfillment scale.

Dimension Description
Market Structure Moderately consolidated; the top companies profiled in this report collectively account for a majority of global data center infrastructure market revenue, given the capital-intensive nature of power, cooling, and compute equipment manufacturing.
Innovation Focus Liquid cooling systems, AI-optimized power distribution, and infrastructure AIOps software dominate current innovation pipelines across leading vendors.
M&A Activity Selective capability acquisitions and capacity expansion, with power and cooling majors continuing to broaden integrated infrastructure portfolios to serve hyperscale and colocation customer demand.

How Do Companies Compete in the Data Center Infrastructure Market?

Companies compete primarily on integration breadth, engineering support, and global fulfillment scale across the industry. Diversified power and cooling majors such as Schneider Electric and Vertiv Holdings Co. leverage integrated power, cooling, and management software portfolios to serve hyperscale and colocation customers, while compute specialists such as NVIDIA Corporation and Super Micro Computer, Inc. compete through accelerator and server platform performance driving downstream infrastructure specification.

Which Competitive Archetypes Dominate the Data Center Infrastructure Market?

Two archetypes dominate the market: diversified infrastructure majors offering integrated power, cooling, and physical infrastructure portfolios, and compute and networking specialists whose platform choices drive downstream infrastructure requirements. Schneider Electric and Vertiv Holdings Co. exemplify the diversified archetype through end-to-end facility infrastructure capability, while NVIDIA Corporation and Cisco Systems, Inc. exemplify the specialist archetype through compute and networking platforms that dictate power density and cooling architecture decisions.

How Are Companies Differentiating Through Innovation in Data Center Infrastructure?

Innovation and differentiation strategy increasingly center on liquid cooling systems and AI-optimized power distribution architecture. NVIDIA's continued expansion of high-density GPU platforms and Vertiv's parallel expansion of thermal management and power infrastructure both illustrate how compute and infrastructure vendors coordinate innovation roadmaps. Our analysis shows that vendors unable to demonstrate credible high-density cooling and power capability risk exclusion from hyperscale facility specification shortlists.

What M&A and Expansion Activity Is Shaping the Data Center Infrastructure Market?

Capacity expansion and portfolio broadening activity continue to reshape competitive positioning within the industry. Vertiv Holdings' continued expansion of its power and thermal management manufacturing capacity strengthens its hyperscale supply position, while Schneider Electric's ongoing energy management software portfolio expansion illustrates how diversified vendors pursue integrated hardware-software positioning to capture greater customer wallet share without relying solely on point-product sales.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping infrastructure innovation, capacity expansion, and integration strategy within the global data center infrastructure market.

Schneider Electric Vertiv Holdings Co. Dell Technologies Hewlett Packard Enterprise Company Huawei Technologies Co., Ltd. Cisco Systems, Inc. NVIDIA Corporation ABB Ltd Super Micro Computer, Inc. Lenovo Group Limited Legrand S.A. Eaton Corporation plc Arista Networks, Inc Everpure , Inc. Delta Electronics, Inc. International Business Machines Corporation Corning Incorporated nVent Electric plc Delta Controls Inc Munters Group AB

Latest Developments

We found that recent activity within the data center infrastructure market is concentrated on liquid cooling capacity expansion, AI infrastructure partnerships, and power management portfolio growth, reflecting the industry's response to accelerating AI-driven facility demand.

Date Event
July 2026 Schneider Electric and AMD introduced a validated reference design for AMD’s Helios rack-scale platform. The design supports 246 kW AI racks and modular AI clusters reaching up to 10.4 MW IT load, combining AMD compute with Schneider Electric power, cooling, and digital infrastructure technologies.
July 2026 Vertiv deployed integrated power, liquid cooling, rack infrastructure, and installation services supporting the Naval Postgraduate School’s NVIDIA DGX GB300 system.
July 2026 Supermicro expanded its Data Center Building Block Solutions portfolio with ten rear-door heat exchanger models supporting cooling capacities from 10 kW to 120 kW. The systems are designed for high-density AI and HPC environments and provide liquid-cooling options for both new and existing data centers .
June 2026 Vultr selected HPE and NVIDIA for large-scale AI data center deployments using NVIDIA GB300 NVL72 systems, Spectrum-X networking, liquid cooling, and HPE deployment services. The expansion includes hyperscale GPU clusters and 400GbE/800GbE networking to support enterprise AI, model training, inference, and private-cloud workloads.
June 2026 Dell introduced the PowerEdge XE8812 within its Dell AI Factory with NVIDIA, featuring NVIDIA Vera Rubin NVL4 architecture and supporting up to 144 GPUs per rack in the PowerRack 9100. The platform targets demanding HPC and AI workloads requiring significantly greater compute density.

Expert Insights

Jason Kaiser

Jason Kaiser

Group President | Caterpillar Power & Energy

"“ As AI-driven workloads continue to accelerate, the demand for robust and scalable power infrastructure and cooling is becoming increasingly critical . ”"

Analyst Interpretation

The statement highlights the growing importance of power and cooling infrastructure as AI workloads increase data center compute density and energy requirements. The rapid deployment of AI-focused facilities is strengthening demand for scalable power generation, advanced cooling systems, integrated energy solutions, and efficient infrastructure architectures. This shift is also encouraging data center operators to adopt on-site power and optimized cooling solutions to address grid constraints, improve energy efficiency, and accelerate deployment timelines .

Supply Chain Analysis of the Data Center Infrastructure Industry

Supply Chain Analysis of the Data Center Infrastructure Industry
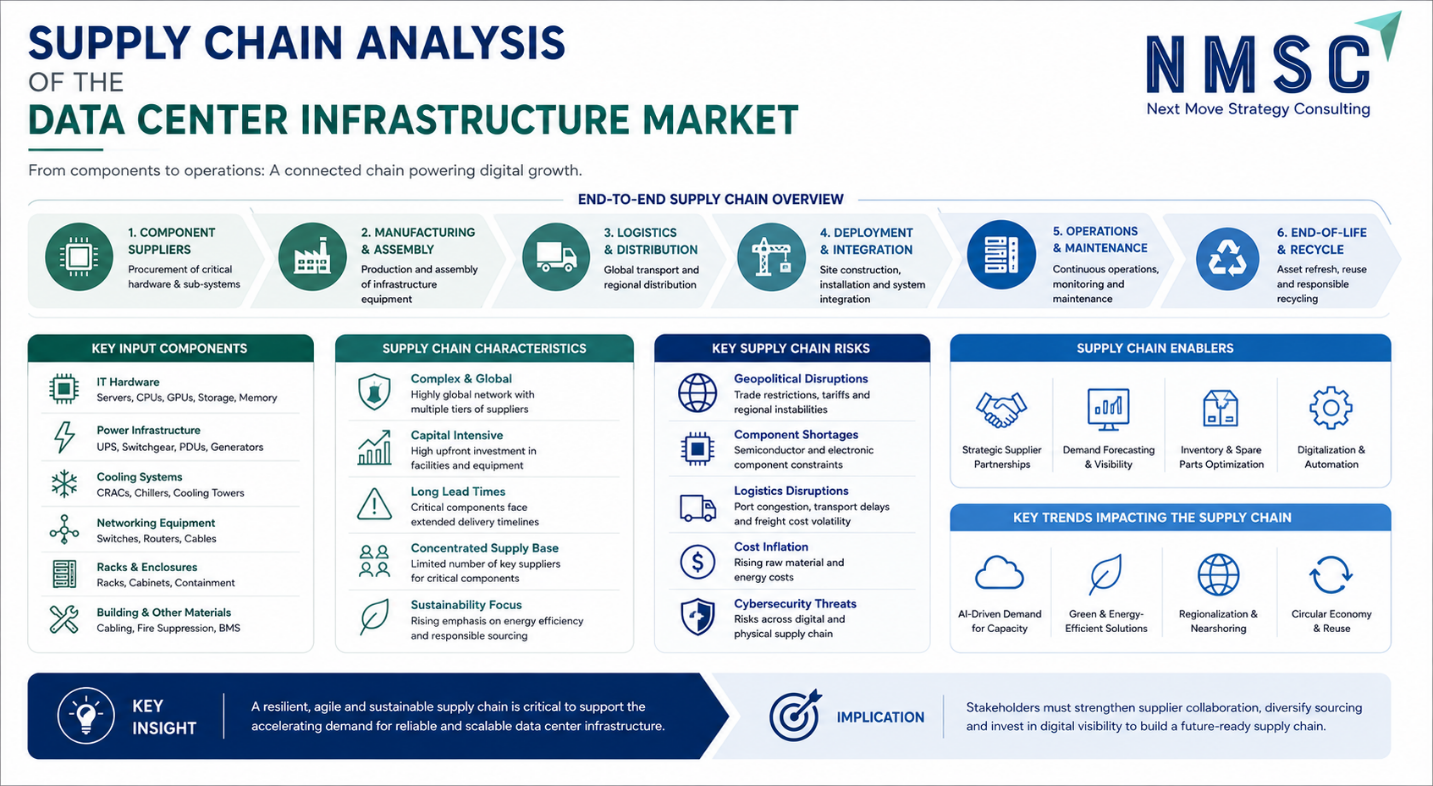
The above infographic provides a detailed supply chain analysis of the data center infrastructure market, mapping the end-to-end flow from component sourcing and manufacturing to deployment and end-of-life recycling. It outlines key components and characteristics, while highlighting significant risks such as geopolitical disruptions and component shortages. To mitigate these challenges, the analysis emphasizes the importance of strategic partnerships and digital visibility as essential enablers. Ultimately, it concludes that building a resilient, sustainable supply chain is critical to supporting the accelerating demand for reliable data center infrastructure .

Investment Opportunities

What Capital Inflows Are Fueling Data Center Infrastructure Market Development?

Capital investment is flowing into hyperscale facility construction and AI infrastructure buildout, exemplified by continued cloud service provider capital expenditure disclosures supporting new data center capacity. Our findings suggest that this capital inflow is validating data center infrastructure as a durable, investment-grade technology category rather than a cyclical construction segment, attracting continued vendor investment in power, cooling, and compute capacity.

How Is Infrastructure Investment Shaping Data Center Infrastructure Market Expansion?

Grid interconnection and renewable power infrastructure investment is shaping how operators site and scale new hyperscale and colocation facilities globally. We observed that this infrastructure investment reflects sustained commitment to securing reliable, scalable power access as data center electricity demand continues to outpace transmission capacity additions in several established markets.

What ESG Considerations Influence Data Center Infrastructure Market Investment?

Environmental, social, and governance considerations increasingly influence data center infrastructure investment as operators prioritize renewable power procurement and water-efficient cooling technologies. Our analysis shows that green data center design, including liquid cooling systems that reduce water consumption compared with traditional evaporative cooling, aligns with sustainability reporting requirements, strengthening the investment case for vendors with demonstrated efficiency credentials.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders?

This report equips information technology and telecommunications industry leaders with segmented revenue forecasts, facility adoption trends, and competitive benchmarking needed to prioritize infrastructure investment across offering and data center type segments. Our findings suggest that leaders can use the segmentation analysis and regional outlook to align capacity planning with the fastest-growing offering, tier standard, and end-user segments identified in this report.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts gain a data-driven view of market sizing, CAGR trajectories, and company-level competitive positioning to evaluate capital allocation across the data center infrastructure value chain. We found that the investment opportunities and competitive landscape sections provide the forecast granularity needed to assess vendor capacity expansion and technology partnership opportunities.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams benefit from detailed segmentation across offering, facility size, and tier standard axes that clarify where product development investment will generate the strongest returns. Our assessment indicates that the growth opportunities and emerging trends sections help product teams prioritize liquid cooling and infrastructure AIOps roadmaps ahead of competitors.

Key Market Segments Evaluated

By Offering

  • Hardware
  • Software
  • Services

By Data Center Type

  • Enterprise Data Centers
  • Colocation Data Centers
  • Cloud Data Centers

By Facility Size

  • Below 1 MW
  • 1–10 MW
  • 11–25 MW
  • 26–50 MW
  • Above 51 MW

By Facility Location

  • Core
  • Edge

By Tier Standard

  • Tier I
  • Tier II
  • Tier III
  • Tier IV

By End User

  • BFSI
  • Cloud Service Providers
  • Colocation Providers
  • Education
  • Energy & Utilities
  • Government & Defense
  • Healthcare
  • Manufacturing
  • Media & Entertainment
  • Retail & E-commerce
  • Telecommunications
  • Transportation & Logistics
  • Others

By Region

  • North America: U.S.
  • Canada
  • Mexico.
  • Europe: UK
  • Germany
  • France
  • Italy
  • Spain
  • Sweden
  • Denmark
  • Finland
  • Netherlands
  • Rest of Europe.
  • Asia-Pacific: China
  • India
  • Japan
  • South Korea
  • Taiwan
  • Indonesia
  • Vietnam
  • Australia
  • Philippines
  • Malaysia
  • Rest of APAC.
  • Middle East & Africa: Saudi Arabia
  • UAE
  • Egypt
  • Israel
  • Turkey
  • Nigeria
  • South Africa
  • Rest of MEA.
  • Latin America: Brazil
  • Argentina
  • Chile
  • Colombia
  • Rest of LATAM.

Conclusion & Recommendations

The long-term outlook remains strongly positive, with the market projected to expand from USD 328.11 billion in 2026 to USD 795.17 billion by 2035 at a 10.3% CAGR. We observed that sustained AI workload deployment and hyperscale capacity expansion provide durable, structural tailwinds that extend well beyond the current forecast window, supporting continued vendor investment across hardware, software, and services segments.

What Strategic Positioning Should Suppliers Pursue?

Suppliers should prioritize integrated power, cooling, and software offerings that reduce customer procurement complexity across hyperscale, colocation, and enterprise deployments. Our assessment indicates that vendors combining proven infrastructure hardware with credible AIOps and energy management software will be best positioned to win recurring facility contracts, particularly as operators consolidate vendor relationships to simplify long-term infrastructure management.

How Attractive Is the Data Center Infrastructure Market for New Investment?

The data center infrastructure industry presents an attractive investment case, supported by a USD 467.06 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Middle East & Africa and Cloud Data Center categories. We found that investment attractiveness is highest for vendors combining power and cooling depth with software integration capability, positioning them to serve both established enterprise customers and emerging hyperscale and edge programs simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor grid interconnection delays, high capital costs for Tier IV construction, and supply chain constraints for advanced power and cooling equipment as key risks to the data center infrastructure market. Our analysis shows that vendors unable to demonstrate reliable delivery timelines and power availability solutions risk losing facility specification wins, particularly as hyperscale operators increasingly prioritize speed to power in site selection decisions.

What Are the Key Growth Pathways for the Data Center Infrastructure Market?

Key growth pathways include expanding liquid cooling capacity, scaling Tier IV and hyperscale facility construction, and deepening penetration into infrastructure AIOps and edge computing deployment. NMSC's analysis indicates that vendors pursuing these pathways while maintaining cost competitiveness in core Tier III facility categories will be best positioned to capture the data center infrastructure market's projected growth through 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market Revenue Analysis
  • Historical revenue and installed capacity analysis (MW and facility count) across offerings, data center types, and regions.
  • Reveals growth trends and cycles to prioritize high-growth offerings and regions.
Company-Level Revenue Benchmarking
  • Revenue benchmarking of leading infrastructure vendors and operators by offering and region from annual reports and filings.
  • Clarifies competitive positioning and identifies partnership and M&A targets.
Country-Level Trade Assessment
  • Country-wise import and export analysis of core infrastructure equipment such as UPS, generators, cooling units, and switchgear.
  • Supports sourcing, localization, and supply chain risk decisions.
Power Capacity and Cooling Technology Adoption Analysis
  • Adoption mapping of power and cooling architectures (air, liquid, immersion; redundancy configurations) by data center type, facility size, and tier standard.
  • Guides product roadmap and technology investment toward high-density and AI-ready infrastructure.
Hyperscale and Colocation Capacity Pipeline Assessment
  • Announced and under-construction capacity pipeline by region, facility location, and end user, drawn from operator disclosures and government and utility filings.
  • Identifies near-term demand hotspots and targets for equipment suppliers and investors.
Grid Power, Energy Efficiency and Regulatory Impact Assessment
  • Country-level analysis of electricity availability, PUE and efficiency standards, and sustainability regulations affecting facility siting and tier choices.
  • Prioritizes expansion markets and shapes compliant, energy-efficient offerings.

FAQs

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Kishu Kanda

KISHU KANDA

Strategy Analyst

Accenture

We purchased the AI Consumer Market Report from this company. Not only did they customize the report to meet our specific requirements, but they also showed great flexibility in accommodating our budget. The report we received fully met our expectations. Additionally, they provided prompt and thorough responses to both our pre-purchase and follow-up questions. We look forward to working with this company again in the future.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖