Netherlands Drone Market By Component (Hardware, Software, and Services), By Platform Type (Multi-Rotor, Fixed-Wing, Hybrid VTOL, and Others), By Autonomy Level (Remotely Piloted, Assisted, Advanced, and Fully Autonomous), By Maximum Take-off Weight {Nano (<250 g), Micro (250 g–2 kg), Small (>2 kg–25 kg), and Others}, By End-User (Consumer Drone, Commercial & Industrial Drone, Government & Public Safety Drone, and Military Drone) – Analysis & Forecast, 2025–2035
Industry: Aerospace & Defense | Latest Edition: August 12, 2026 | No of Pages: 265 | No. of Tables: 140 | No. of Figures: 128 | Format: PDF | Report Code: AD4008
Netherlands Drone Market Size & Forecast
|
Parameters |
Details |
|
Market Size in 2025 |
USD 807.5 million |
|
Market Size in 2026 |
USD 960.6 million |
|
Revenue Forecast in 2035 |
USD 2,728.5 million |
|
Market Size Growth Rate |
CAGR of 12.30% from 2026 to 2035 |
|
Market Volume in 2025 |
25 thousand units |
|
Market Volume in 2026 |
32 thousand units |
|
Volume Forecast in 2035 |
121 thousand units |
|
Market Volume Growth Rate |
CAGR of 16.14% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Million (USD) |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 companies |
Industry Outlook
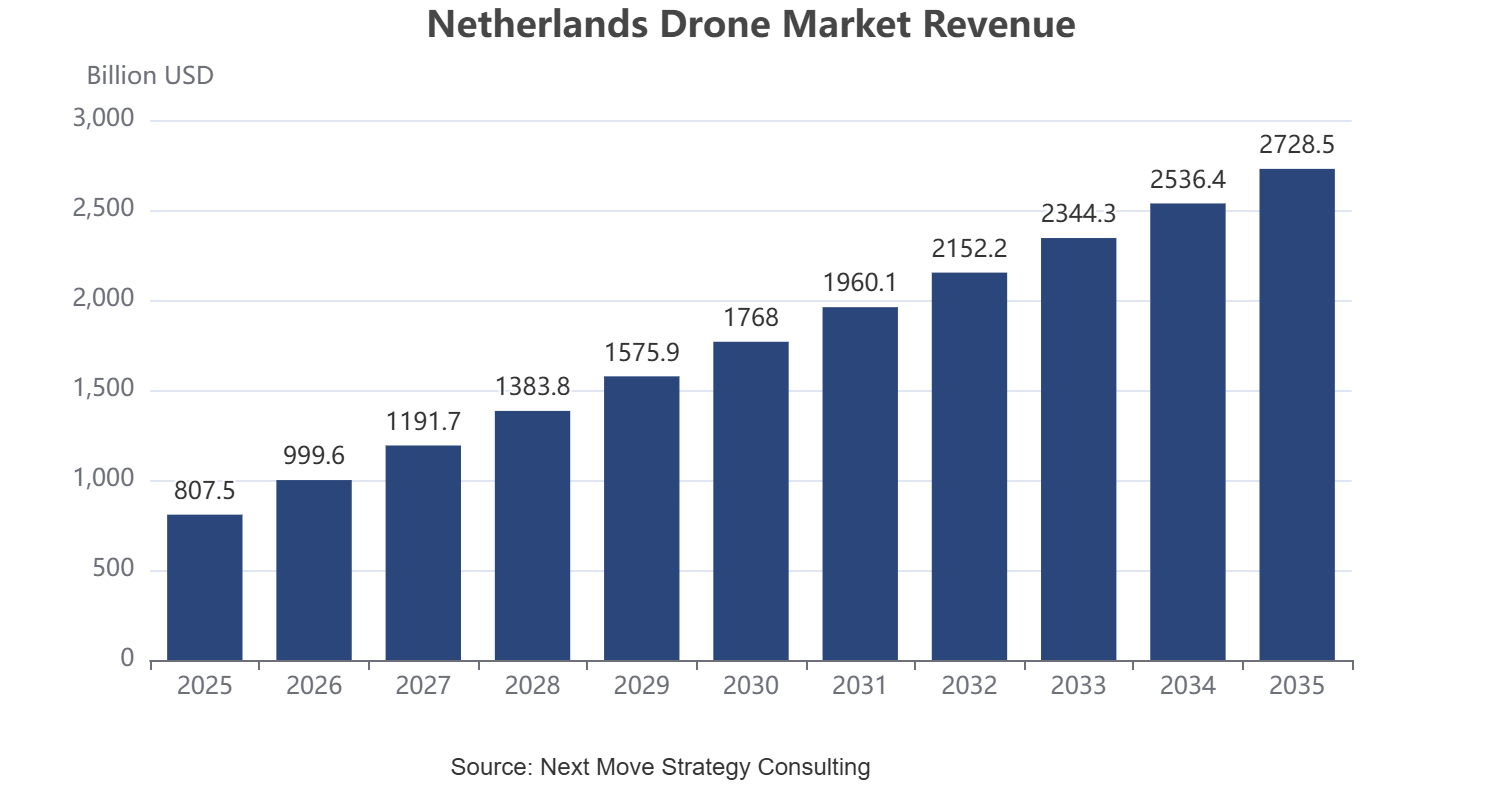
The Netherlands Drone Market was valued at USD 807.5 million in 2025, supported by strong government-backed testing infrastructure, rising defense modernization spending, and expanding commercial adoption across logistics and infrastructure inspection. The market is estimated to reach USD 960.6 million in 2026 and is projected to advance to USD 2,728.5 million by 2035, registering a CAGR of 12.30% from 2026 to 2035. In volume terms, the market is estimated at 25 thousand units in 2025, rising to 32 thousand units in 2026 and an estimated 121 thousand units by 2035, reflecting a CAGR of 16.14% from 2026 to 2035.
What Are the Key Growth Catalysts, Restraints, and Emerging Opportunities Shaping the Netherlands Drone Market Through 2035?
Growth Catalyst & Risk Assessment Matrix
|
Drivers / Trends / Restraints |
(+/-) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Rising European defense spending and heightened security concerns accelerating military and ISR drone procurement |
+3.1% |
Nationwide, tied to NATO commitments |
Long term (4–7 years) |
|
Government-backed drone test corridors and RPAS innovation zones accelerating commercial technology validation |
+2.2% |
Twente, Marknesse, and national test zones |
Medium to long term (3–6 years) |
|
Growing adoption of drones for port, energy, and transport infrastructure inspection across the Randstad |
+1.8% |
Rotterdam, Amsterdam, and Randstad region |
Medium term (2–5 years) |
|
Expanding EASA U-space regulatory framework enabling structured beyond-visual-line-of-sight commercial operations |
+1.4% |
Nationwide, EU-aligned |
Medium term (2–5 years) |
|
Airspace congestion and privacy regulation complexity constraining large-scale commercial BVLOS deployment |
-1.3% |
Densely populated Randstad urban areas |
Short to medium term (1–4 years) |
The Netherlands Drone Market is shaped by a distinctive combination of defense-driven demand, a mature regulatory testing ecosystem, and dense commercial application across logistics and infrastructure. From our analysis, we observed that the country's compact geography and advanced digital infrastructure make it a preferred European proving ground for beyond-visual-line-of-sight operations. Rising defense budgets tied to broader European security realignment are reinforcing military-grade demand, while urban airspace complexity continues to moderate the pace of commercial scaling.
Growth Drivers:
How Is Rising European Defense Spending Driving Military Drone Demand in the Netherlands?
Through NMSC’s assessment, we found that heightened European security concerns and NATO-aligned defense modernization commitments are directly accelerating Dutch procurement of ISR, loitering munition, and electronic warfare drone systems. Defense ministries across the region are prioritizing unmanned platforms for reconnaissance and counter-drone capability given evolving battlefield lessons from recent conflicts. This procurement momentum is reinforcing sustained high-value demand for military-grade platforms throughout the forecast period.
How Are Government-Backed Test Corridors Accelerating Commercial Drone Innovation in the Netherlands?
We observed that dedicated RPAS test zones and national innovation programs are enabling manufacturers and operators to validate beyond-visual-line-of-sight technology under real-world conditions ahead of broader EU regulatory rollout. From our industry analysis, we noted that this testing infrastructure is attracting both domestic startups and international drone developers seeking a stable regulatory environment, positioning the Netherlands as a disproportionately influential European hub relative to its market size.
How Is Infrastructure Inspection Demand Expanding Commercial Drone Adoption in the Netherlands?
Our industry analysis indicates that port operators, energy utilities, and transport authorities across the Randstad are increasingly deploying drones for infrastructure inspection tasks previously requiring manual survey crews or scaffolding. This shift is driven by measurable cost and safety benefits, particularly for offshore wind and port crane inspection. Growing enterprise-grade platform adoption in this segment is reinforcing steady commercial revenue growth alongside the market's defense-driven demand base.
Growth Inhibitor:
How Does Airspace Congestion Constrain Commercial Drone Scaling in the Netherlands?
In our assessment, the Netherlands' dense population distribution and correspondingly congested urban airspace, particularly across the Randstad, continue to constrain large-scale commercial beyond-visual-line-of-sight deployment despite a supportive regulatory framework. Privacy regulation and air traffic coordination requirements near Schiphol and other major airports add further operational complexity. These constraints slow commercial logistics and delivery use-case scaling relative to less densely populated European markets.
Growth Opportunity:
How Does EASA U-Space Rollout Create Opportunity for Netherlands Drone Operators?
The phased rollout of the EASA U-space regulatory framework presents significant opportunity for Dutch drone operators and software providers building fleet management and airspace deconfliction solutions ahead of full EU-wide implementation. Companies developing compliant traffic management and data processing platforms are well positioned to capture first-mover advantage as commercial BVLOS corridors open. This opportunity is reinforced by the country's existing test infrastructure and close working relationships with national aviation regulators.
How Is the Netherlands Drone Market Segmented in This Report, and What Are the Key Insights From the Segmentation Analysis?
By Autonomy Level Insights
How Does Autonomy Level Segmentation Reflect Technology Advancement in Netherlands?
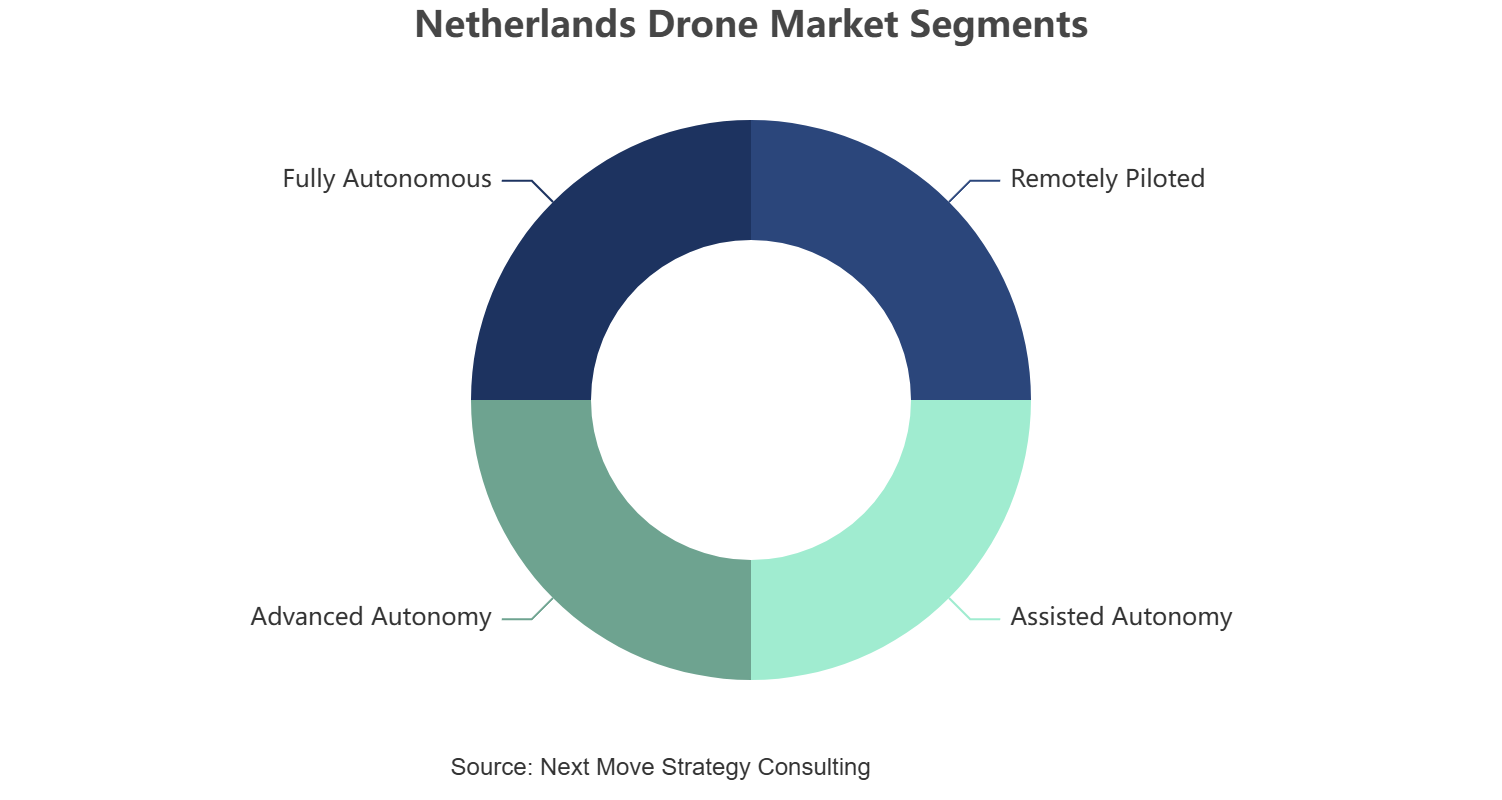
Based on autonomy level, the Netherlands Drone Market is segmented into remotely piloted, assisted autonomy, advanced autonomy, and fully autonomous platforms.
The market reflects a gradual transition toward higher levels of automation as commercial, government, and defense users adopt drone technologies to improve operational efficiency and mission reliability. According to our analysis, we found that remotely piloted platforms continue to support established applications such as aerial imaging, surveying, infrastructure inspection, and public safety operations. Assisted autonomy solutions are gaining adoption through automated navigation, obstacle avoidance, and precision flight functions, while advanced and fully autonomous platforms are emerging for logistics, maritime monitoring, and defense missions requiring reduced operator dependency and enhanced operational continuity.
By Maximum Take-off Weight (MTOW) Insights
How Does Maximum Take-off Weight (MTOW) Segmentation Reflect Platform Distribution?
Based on maximum take-off weight (MTOW), the Netherlands Drone Market is segmented into nano (<250 g), micro (250 g–2 kg), small (>2 kg–25 kg), medium (>25 kg–150 kg), large (>150 kg–600 kg), and very large/tactical (>600 kg) platforms.
The market comprises a diverse range of drone weight categories designed to address different operational requirements across consumer, commercial, government, and defense applications. According to our analysis, we found that nano and micro platforms support lightweight imaging, inspection, and recreational activities, while small and medium-class drones are increasingly used for agriculture, surveying, infrastructure monitoring, and logistics operations requiring higher payload capacity. Large and very large/tactical platforms serve specialized applications such as maritime surveillance, defense missions, and long-endurance operations where greater payload capability, range, and mission performance are critical.
Pestel Analysis of the Netherlands Drone Market:
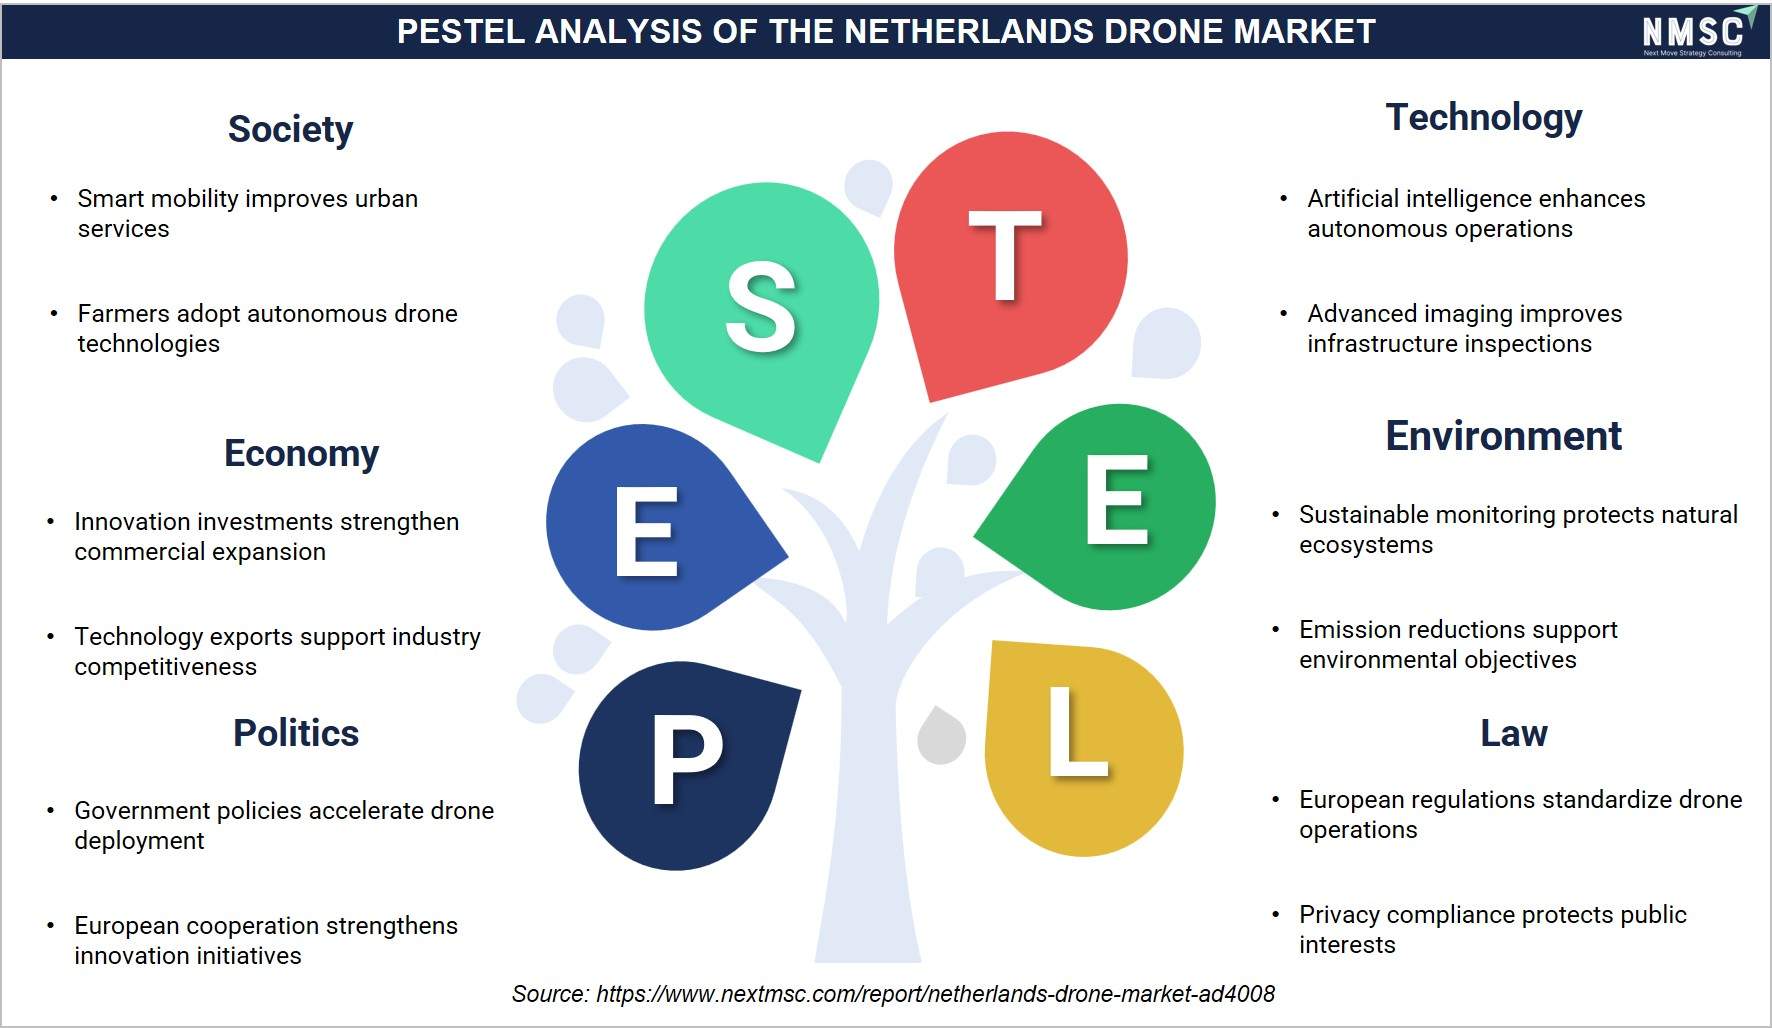
The above PESTEL analysis maps the key macro-environmental factors, such as political, economic, social, technological, environmental, and legal, shaping the Netherlands drone market. From our analysis, we observed that political stability and EU-wide regulations support drone integration, while economic factors influence investment and operational costs. Social acceptance and technological advancements drive innovation, whereas environmental regulations promote sustainable operations and emissions reduction. Legal frameworks, including aviation laws and GDPR compliance, ensure safety and data protection, reflecting a comprehensive PESTEL landscape across the Netherlands drone industry.
Key Segments
By Component
-
Hardware
-
Airframe
-
Avionics & Core Systems
-
Payloads & Sensors (Cameras, LiDAR, Multispectral, etc.)
-
Communication Systems (C2 Links)
-
-
Software
-
Flight Control & Autonomy
-
Data Processing & Analytics
-
Fleet Management
-
-
Services
-
Drone-as-a-Service (DaaS)
-
Training & Certification
-
Maintenance, Repair & Overhaul (MRO)
-
Data Processing Services
-
By Platform Type
-
Multi-Rotor
-
Fixed-Wing
-
Hybrid VTOL (Vertical Take-Off and Landing)
-
Single-Rotor (Helicopter)
-
Tethered UAV
-
Loitering Munition
-
MALE/HALE/UCAV
By Autonomy Level
-
Remotely Piloted
-
Assisted Autonomy
-
Advanced Autonomy
-
Fully Autonomous
By Maximum Takeoff Weight (MTOW)
-
Nano: < 250 g
-
Micro: 250 g – 2 kg
-
Small: > 2 kg – 25 kg
-
Medium: > 25 kg – 150 kg
-
Large: > 150 kg – 600 kg
-
Very Large/Tactical: > 600 kg
By Price/Performance Grade
-
Consumer Grade (< $1,000)
-
Prosumer Grade ($1,000–$10,000)
-
Enterprise Grade ($10,000–$100,000)
-
Military Grade (> $100,000)
By End-User
-
Consumer Drone
-
Commercial & Industrial Drone
-
Aerial Imaging & Cinematography
-
Surveying & Mapping (Geomatics)
-
Agricultural Applications (Spraying, Crop Monitoring)
-
Infrastructure Inspection (Energy, Utilities, Transport)
-
Logistics & Delivery (Package Transport)
-
Environmental & Scientific Monitoring
-
-
Government & Public Safety Drone
-
Emergency Response & Disaster Management
-
Law Enforcement & Security
-
Firefighting & Public Safety
-
Smart City Management
-
-
Military Drone
-
Intelligence, Surveillance & Reconnaissance (ISR)
-
Combat Operations
-
Electronic Warfare (EW)
-
Target Acquisition & Designation
-
Logistics & Resupply
-
Decoy & Countermeasure Systems
-
Competitive Landscape Overview
The competitive landscape of the Netherlands Drone Market is defined by a mix of globally established platform manufacturers, specialized European hardware developers, and Dutch engineering firms serving inspection, defense, and public safety applications. Market competition is driven by differentiation across autonomy software sophistication, payload and sensor integration, and defense-grade reliability certification. Our assessment indicates that competitive intensity is escalating as European manufacturers scale production to reduce reliance on non-European supply chains amid heightened defense and critical-infrastructure security scrutiny.
Key Players
-
DJI GmbH
-
Flyability SA
-
Autel Robotics Europe GmbH
-
Wingtra AG
-
Percepto Robotics Ltd.
-
AgEagle Aerial Systems Inc.
-
Freefly Systems Inc.
-
AeroVironment, Inc.
-
Parrot Drones S.A.S. and Parrot S.A.
-
Quantum-Systems GmbH
-
Acecore Technologies B.V.
-
BSS Holland B.V.
-
Patria Netherlands B.V.
-
Delft Dynamics B.V.
-
Drone Volt Benelux N.V.
Key players shaping the Netherlands Drone Industry include Delft Dynamics B.V., Acecore Technologies B.V., Quantum-Systems GmbH, Wingtra AG, and others, all of which compete through payload innovation, defense-grade platform reliability, and close integration with the country's national test and certification infrastructure.
Supply Chain Structure of the Netherlands Drone Market:
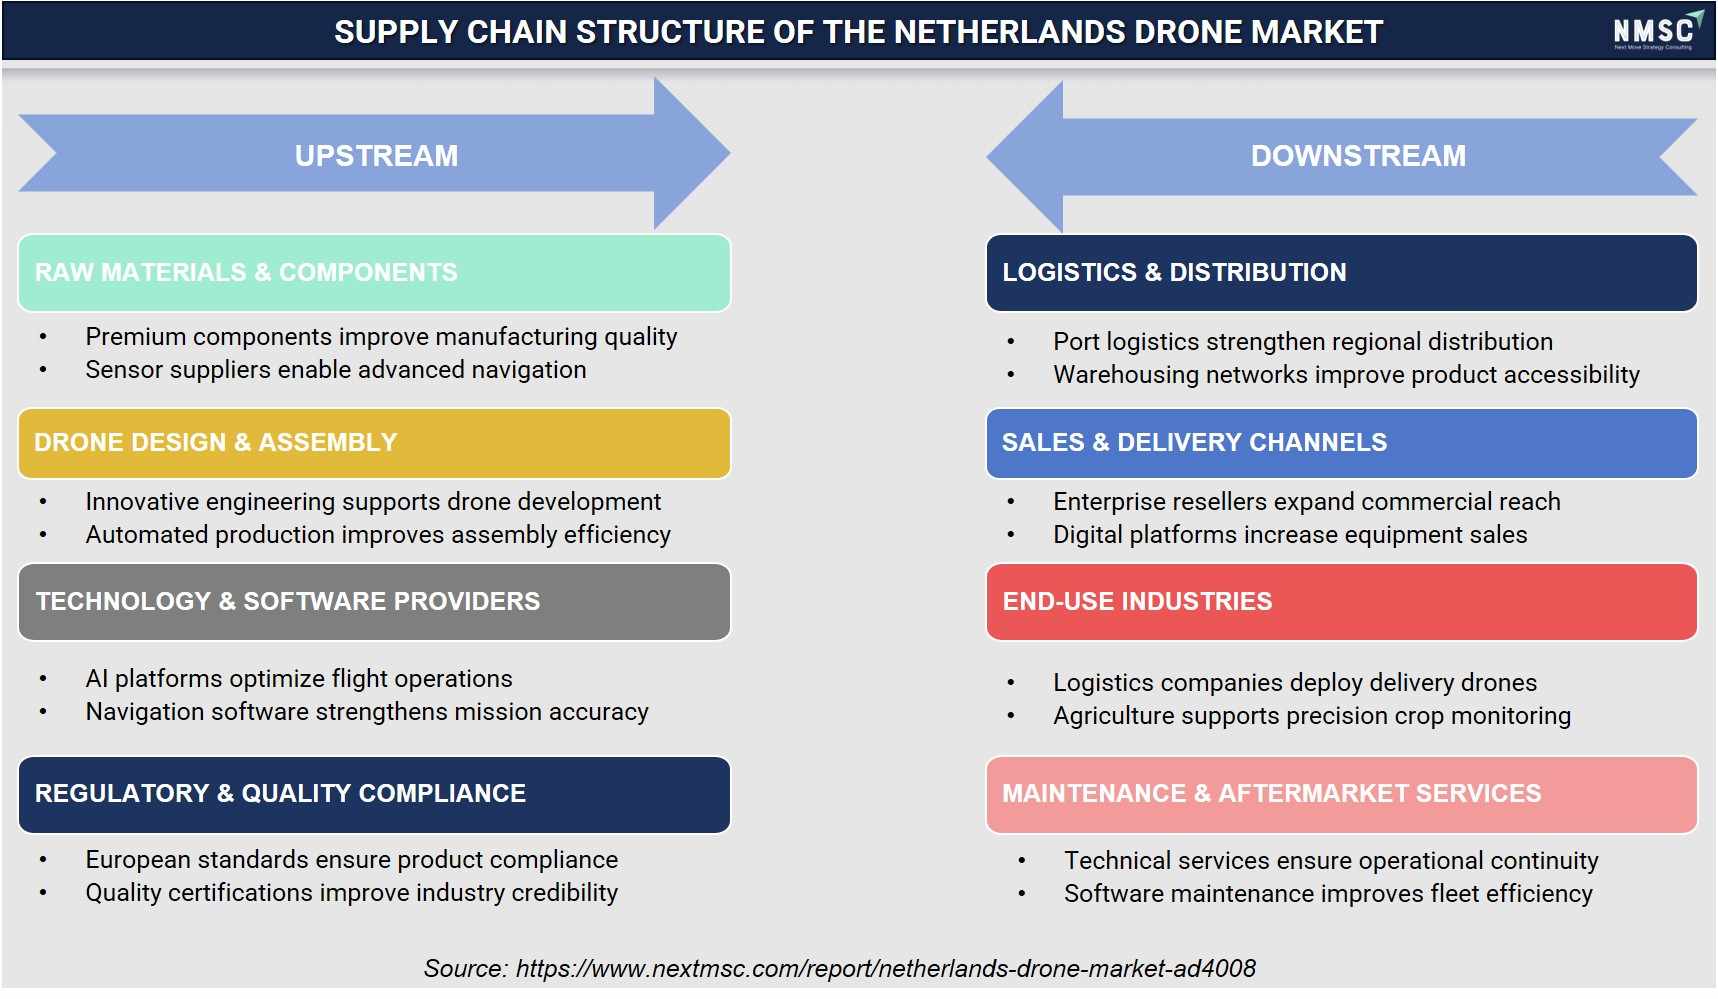
The above supply chain analysis maps the key operational stages, such as upstream and downstream, shaping the Netherlands drone market. From our analysis, we observed that upstream activities include premium components, sensor suppliers, innovative engineering, automated production, AI platforms, navigation software, and European standards, while downstream activities encompass port logistics, enterprise resellers, digital platforms, logistics and agriculture end-users, and technical services, reflecting a well-integrated supply chain across the market.
Key Benefits for Stakeholders
NMSC presents a comprehensive analysis of the Netherlands Drone Market, covering historical trends through 2025 and detailed forecasts through 2035. Our study examines the market at the national level, providing quantitative revenue and volume projections across all major component, platform, and end-user segments.
Stakeholders benefit from sustained demand anchored in defense modernization and test-corridor innovation leadership. Manufacturers and investors gain strategic clarity through detailed segmentation and competitive profiling, supporting market entry, platform positioning, and go-to-market decisions across the Netherlands' distinct commercial and defense drone segments.
|
Parameters |
Details |
|
Customization Scope |
Free customization (equivalent to up to 80 analyst-working hours) after purchase. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |
|
Approach |
In-depth primary and secondary research; proprietary databases; rigorous quality control and validation measures. |
|
Analytical Tools |
Porter's Five Forces, SWOT, value chain, and Harvey ball analysis to assess competitive intensity, stakeholder roles, and relative impact of key factors. |
Conclusion
The Netherlands Drone Market presents a high-growth trajectory anchored in defense modernization, government-backed test infrastructure, and expanding commercial inspection applications. With revenue projected to grow from USD 960.6 million in 2026 to USD 2,728.5 million by 2035 at a CAGR of 12.30%, and volume expanding at 16.14% CAGR over the same period, the market offers substantial opportunity for manufacturers, software providers, and investors positioned to serve both civilian and defense-driven demand across the country's compact but technologically advanced airspace ecosystem.
About the Author
 Mayurima Roy
— Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

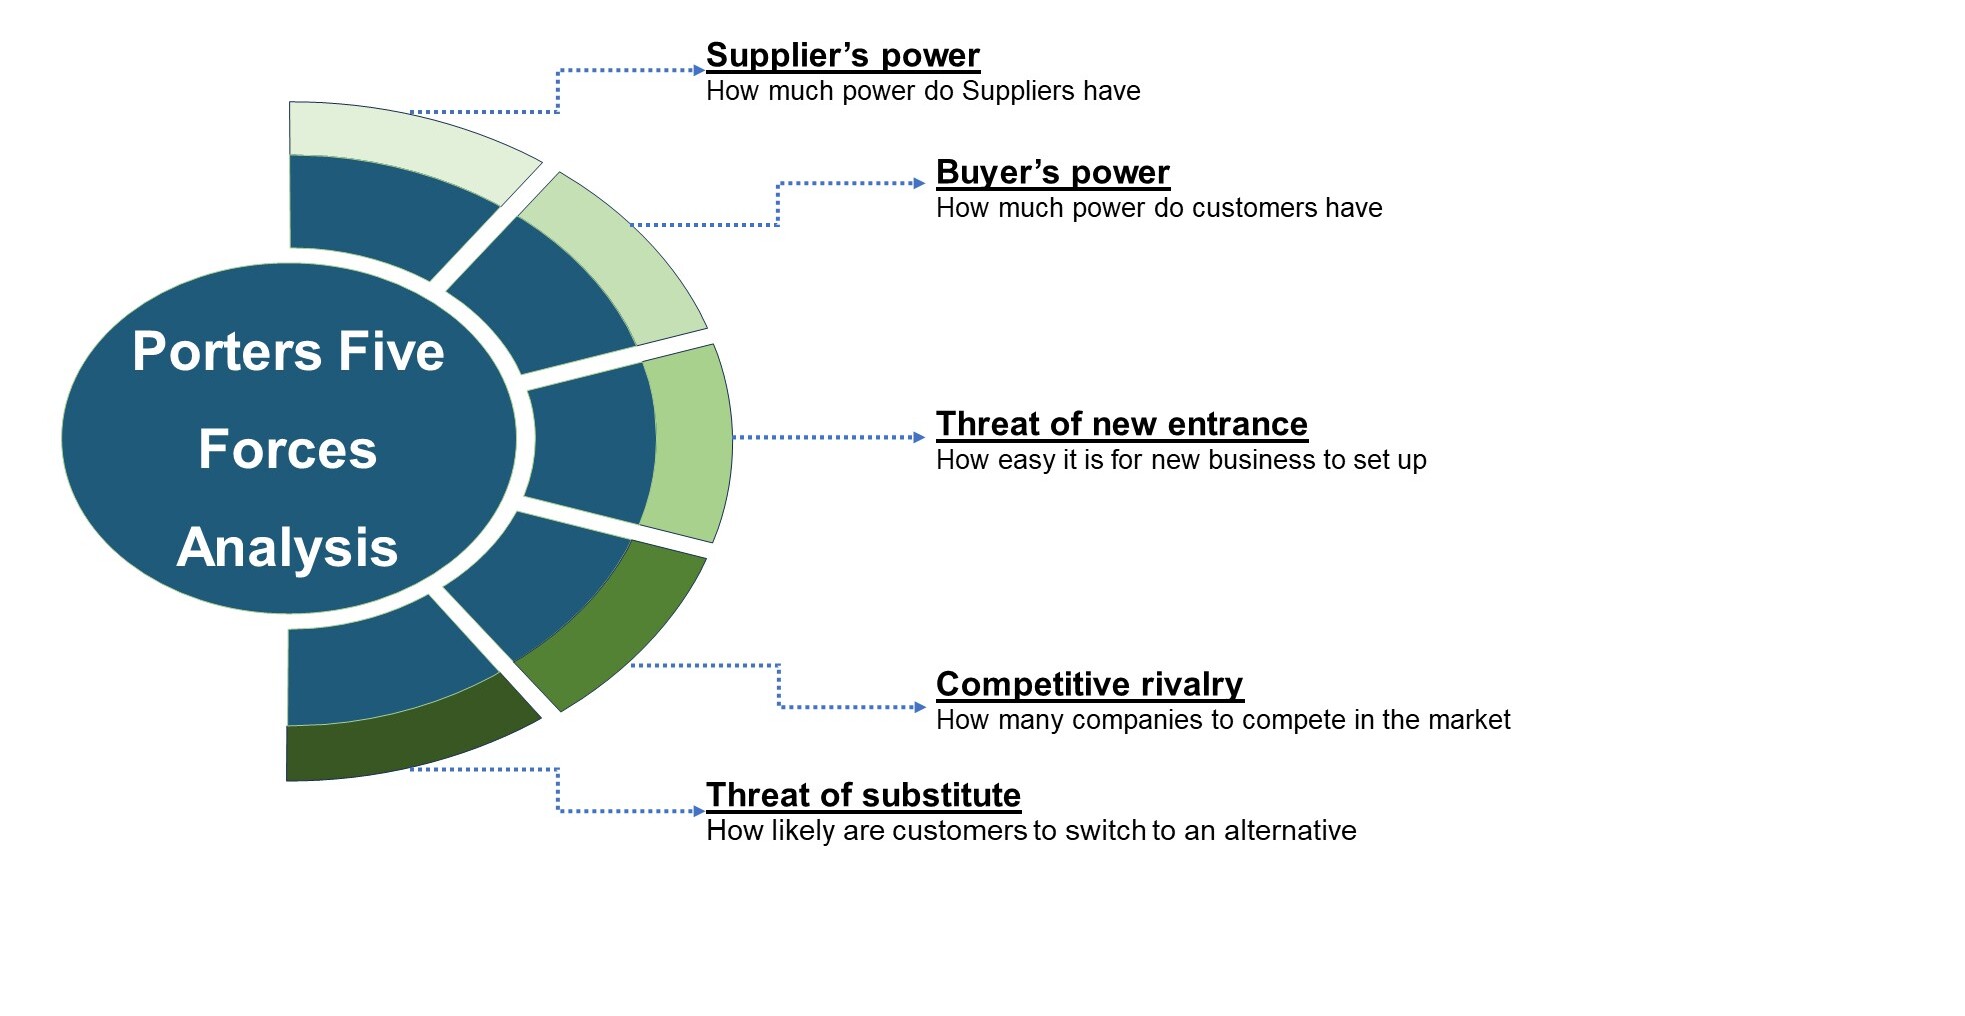
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.



 Speak to Our Analyst