North America Fabric Care Market, By Product Type {Fabric Detergents (General Purpose, Baby Laundry Detergent, and Delicate Laundry Detergent), Fabric Softeners/Conditioners, and Others}, By Form (Liquid, Powder, Unit-Dose, Sheet & Wipe, and Spray), By Nature (Conventional and Eco-friendly / Organic), By Price Tier (Value, Mid-range, and Premium), By Distribution Channel (Online and Offline), and By End-User (Residential, Commercial, and Others) – Analysis & Forecast, 2025–2035
Industry: Retail and Consumer | Latest Edition: August 14, 2026 | No of Pages: 205 | No. of Tables: 85 | No. of Figures: 78 | Format: PDF | Report Code: RC4554
North America Fabric Care Market Size & Forecast
|
Parameters |
Details |
|
Market Size in 2025 |
USD 18.67 billion |
|
Market Size in 2026 |
USD 20.89 billion |
|
Revenue Forecast in 2035 |
USD 27.76 billion |
|
Growth Rate |
CAGR of 3.21% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Billion (USD) |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 companies |
Industry Outlook
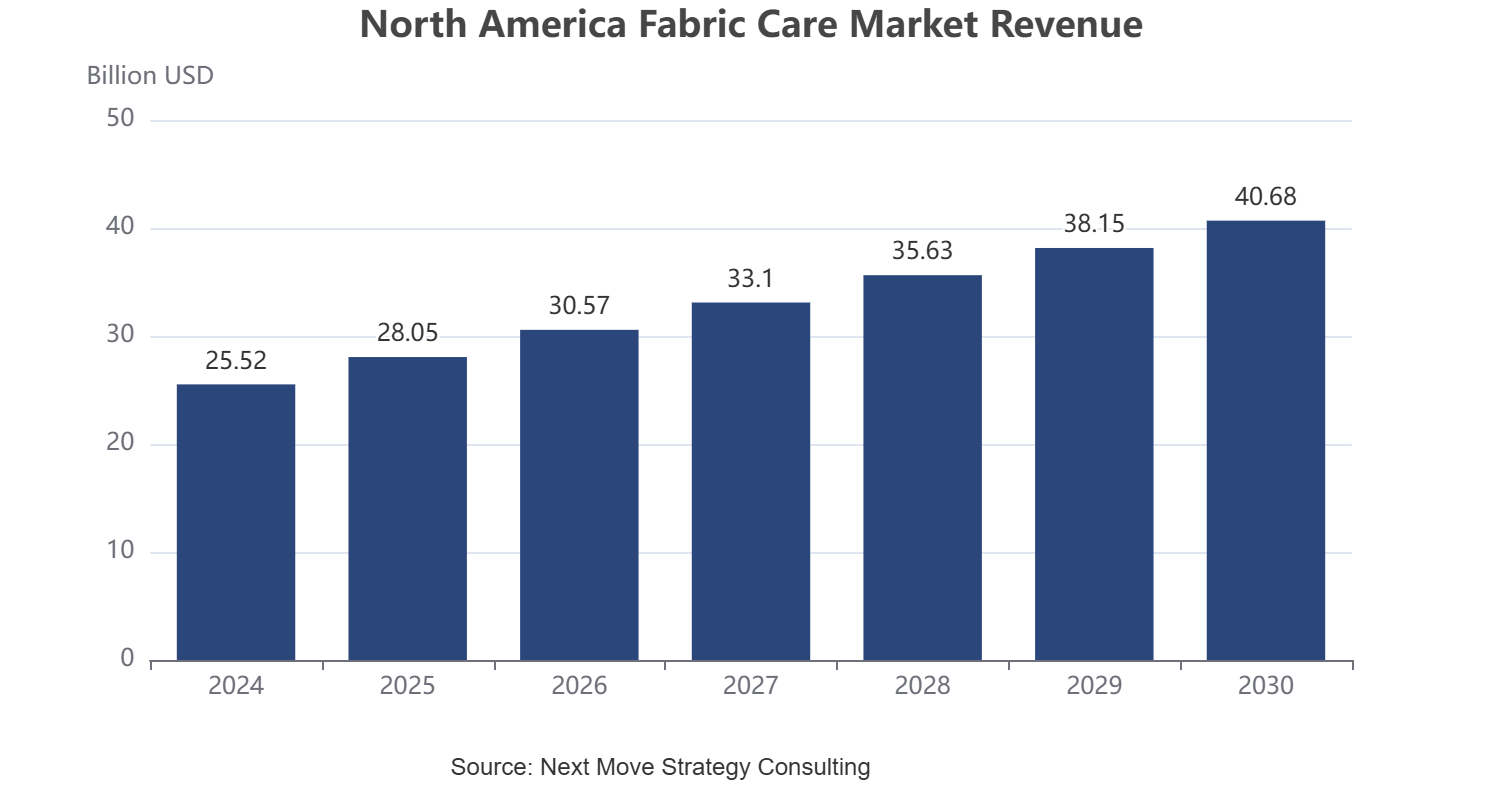
The North America Fabric Care Market was valued at USD 18.67 billion in 2025, representing the largest single-region fabric care market in this report series and reflecting a mature competitive environment characterized by near-universal product penetration, entrenched multinational brand dominance, and an accelerating structural transition toward sustainable, concentrated, and eco-certified product formats. The market is projected to reach USD 20.89 billion by 2026 and is forecast to expand to USD 27.76 billion by 2035, at a CAGR of 3.21% from 2026 to 2035. Growth is driven primarily by format innovation, eco-brand scaling, and the expanding Hispanic consumer demographic rather than volume uplift.
What Are the Key Market Drivers, Restraints, and Opportunities Shaping the North America Fabric Care Market Through 2035?
Growth Catalyst & Risk Assessment Matrix
|
Drivers / Trends / Restraints |
(+/–) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Rapid market expansion of eco-certified, plastic-free, and concentrated laundry formats including strips, sheets, and unit-dose pods driven by North America's growing sustainable consumer cohort and retailer sustainability commitments |
+1.4% |
US coastal metros, Canada's major urban centers |
Medium to Long term (3–6 years) |
|
Amazon and major e-commerce channel dominance enabling direct-to-consumer eco-brands to challenge legacy CPG incumbents at national scale with lower customer acquisition costs and subscription-compatible concentrated formats |
+1.1% |
US and Canada e-commerce penetrated urban markets |
Medium term (2–5 years) |
|
Post-pandemic hygiene consciousness sustaining above-baseline demand for sanitizing, antibacterial, and allergen-reducing fabric care formulations across both residential and commercial end-user segments throughout North America |
+0.8% |
Nationwide across US, Canada, and Mexico |
Long term (4–7 years) |
|
North America's high category penetration, market maturity, and established consumer behavior limiting absolute incremental volume growth and structurally compressing overall revenue CAGR below all emerging market benchmarks in this report series |
−1.3% |
Nationwide |
Persistent throughout forecast period |
|
Growing Hispanic consumer population across US Southwest and Southeast, and expanding Mexican domestic market, creating demand for culturally adapted fabric care formulations and Spanish-language brand communication strategies |
+0.7% |
US Southwest, Southeast, and Mexico |
Medium to Long term (3–6 years) |
The North America Fabric Care Market growth story is fundamentally a qualitative one — format transformation, sustainability disruption, and demographic evolution driving revenue expansion in an environment where volumetric growth is structurally constrained by near-full household penetration. Our analysis indicates that the explosive growth of laundry strips, concentrated pods, and plastic-free format innovations are the primary incremental revenue drivers through 2035, enabled by e-commerce channels that allow challenger eco-brands to compete at national scale without legacy retail shelf infrastructure. Demographic shifts from Hispanic population growth and Mexican market development represent meaningful secondary volume catalysts alongside the dominant format premiumization narrative.
Growth Drivers:
How Is North America's Plastic-Free and Concentrated Laundry Format Revolution Driving Incremental Revenue and Market Transformation?
North America is experiencing a structural fabric care format transition driven by consumer demand for plastic-free packaging, concentrated dosing efficiency, and sustainable ingredient transparency, with laundry strip and sheet formats pioneered by innovators including Tru Earth Environmental Products Inc. and Dropps, Inc. achieving rapid mainstream consumer adoption across US and Canadian markets. Our assessment indicates that these format innovations command meaningful price premiums per wash cycle over conventional liquid and powder alternatives, driving revenue growth independent of volume increases. Major legacy players including The Procter & Gamble Company and Henkel Corporation are responding with concentrated pod and eco-reformulation investments to defend market share against agile eco-brand challengers throughout the forecast period.
How Is Amazon and E-Commerce Channel Dominance Enabling Eco-Brand Disruption of North America's Legacy Fabric Care Market?
Amazon's commanding position in North American household consumable e-commerce, combined with Instacart, brand-owned direct-to-consumer channels, and subscription commerce models, has fundamentally reduced the distribution barrier that historically protected legacy CPG incumbents' retail shelf dominance from eco-brand challengers. Our market assessment indicates that Tru Earth Environmental Products Inc., Dropps, Inc., and Nellie's All-Natural Inc. have collectively captured meaningful urban market share through subscription-optimized concentrated formats, zero-plastic packaging, and authentic sustainability communication that outperforms legacy brand positioning among digitally engaged millennial and Gen Z consumer cohorts. This channel-enabled disruption is the single most consequential competitive dynamic reshaping North America's fabric care landscape through 2035.
How Is Post-Pandemic Hygiene Consciousness Sustaining Above-Baseline Demand for Sanitizing Fabric Care Products Across North America?
North America's post-pandemic consumer base has durably elevated its baseline fabric care hygiene expectations, sustaining above-historical-average demand for laundry sanitizers, antibacterial detergent additives, and allergen-reducing fabric conditioner formulations across both residential and commercial end-user segments. Our analysis indicates that Reckitt's Dettol and Lysol-branded laundry sanitizer additions and Church & Dwight Co., Inc.'s OxiClean sanitizer range have directly benefited from this structural post-pandemic demand shift. Commercial laundry operators including healthcare facilities, hospitality businesses, and institutional cleaning service providers are maintaining elevated sanitization standard requirements established during the pandemic, sustaining incremental commercial segment revenue above pre-2020 trend levels throughout the near-term forecast period.
Growth Inhibitor:
How Is North America's Market Maturity and Near-Universal Household Penetration Structurally Constraining Revenue CAGR?
North America's fabric care market maturity, characterized by near-universal household product penetration, deeply established brand loyalty patterns, and limited incremental consumer base expansion opportunities, structurally constrains the market's achievable revenue CAGR to the lowest level in this global report series at 3.21%. Our assessment indicates that volume growth in North America is effectively flat in aggregate, with revenue expansion dependent entirely on average selling price improvement through format premiumization, eco-certification positioning, and unit-dose adoption. Manufacturers cannot rely on new-to-category household recruitment as a meaningful growth lever, fundamentally shifting competitive strategy toward share-of-wallet maximization and per-unit revenue optimization across existing consumer households throughout the forecast period.
Growth Opportunity:
How Is the Growing Hispanic Consumer Segment and Expanding Mexican Domestic Market Creating New Demand Channels for North America?
North America's rapidly growing Hispanic consumer population, particularly concentrated in US Southwest and Southeast metropolitan markets, and the progressive development of Mexico's domestic organized fabric care retail market, represent meaningful incremental demand channels that are under-leveraged by most incumbent multinational fabric care operators. Our analysis indicates that Industrias AlEn, S.A. de C.V. holds a structurally advantaged position as the largest Mexico-based household care manufacturer with deep distribution reach and culturally resonant brand equity across Hispanic consumer segments in both Mexico and the United States. Portfolio localization, Spanish-language brand communication, and culturally adapted fragrance and format preferences represent the primary strategic levers for capturing this growing demographic-driven demand opportunity throughout the forecast period.
How Is the North America Fabric Care Market Segmented in This Report, and What Are the Key Insights from the Segmentation Analysis?
By End-User Insights
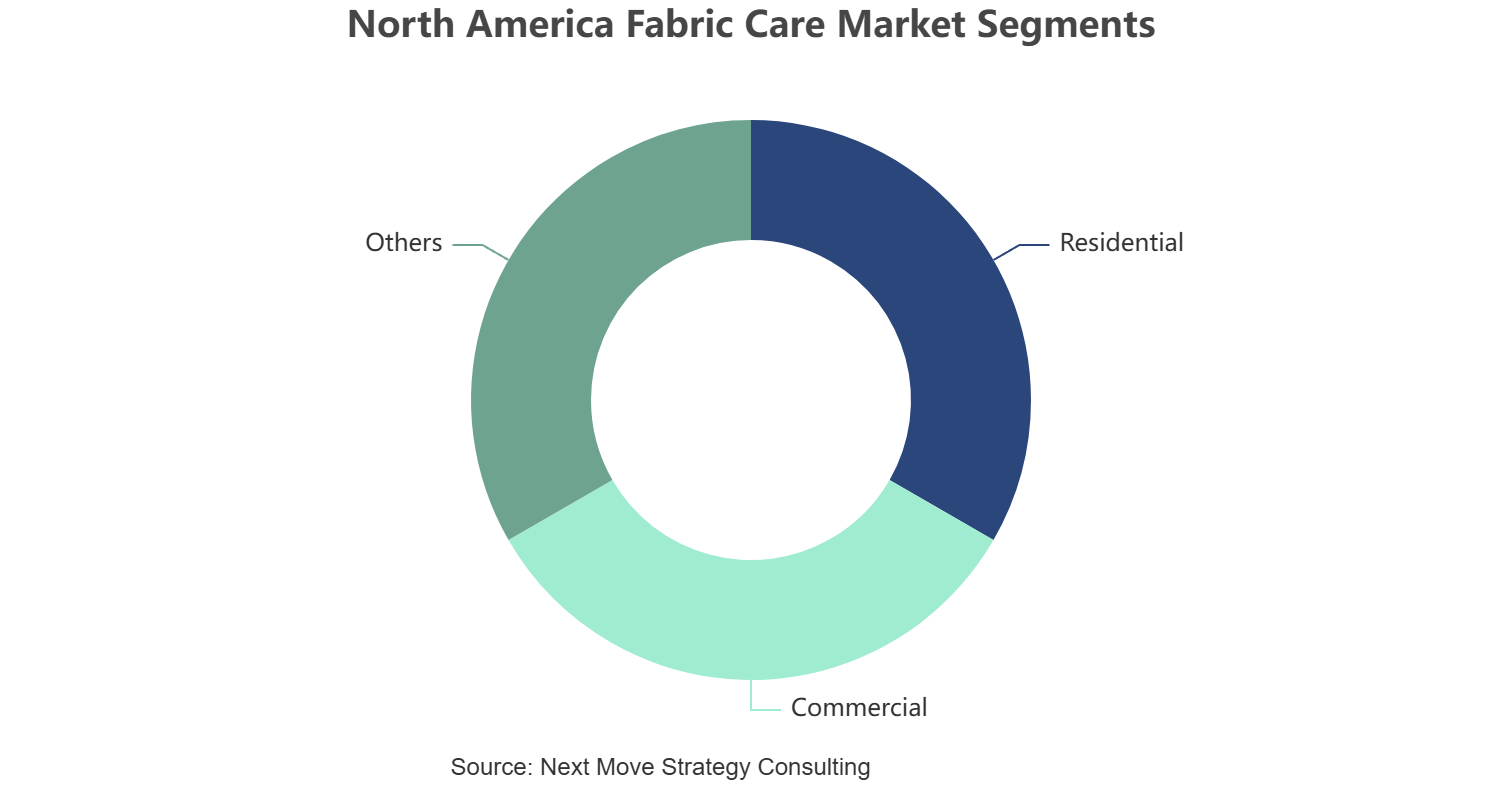
How Does End-User Segmentation Reflect Fabric Care Consumption Patterns Across the North America Fabric Care Market?
Based on product type, the North America Fabric Care Market is segmented into fabric detergents, fabric softeners/conditioners, stain removers/bleach, sanitizer, and other products.
Fabric detergents represent the dominant revenue category in North America fabric care product type segmentation, commanding above-70% revenue share across the US, Canada, and Mexico. Our market assessment indicates that unit-dose pod detergents pioneered by The Procter & Gamble Company's Tide Pods franchise have permanently elevated the category's average revenue per wash cycle, with the format continuing to gain share from liquid and powder alternatives. The sanitizer segment is registering the fastest growth rate post-pandemic, while fabric softeners and conditioners face moderate pressure from consumers shifting to detergent-softener combination formulations and dryer sheet alternatives that simplify laundry routines across North America's time-constrained household segment.
By Distribution Channel Insights
How Does Distribution Channel Segmentation Reflect Evolving Consumer Purchase Behavior Across the North America Fabric Care Market?
Based on distribution channel, the North America Fabric Care Market is segmented into online and offline.
The market reflects a highly developed retail ecosystem where physical and digital channels collectively influence consumer purchasing decisions and brand accessibility. According to our analysis, we found that offline channels, including supermarkets, hypermarkets, and department stores, continue to provide extensive product availability and support routine household purchases through established retail networks. Meanwhile, online channels are expanding steadily, with marketplaces offering broader product selection, brand e-commerce strengthening direct consumer engagement, and quick commerce enhancing convenience through rapid delivery, encouraging manufacturers to adopt comprehensive omnichannel distribution strategies.
Consumer Behavior Analysis of the North America Fabric Care Market:
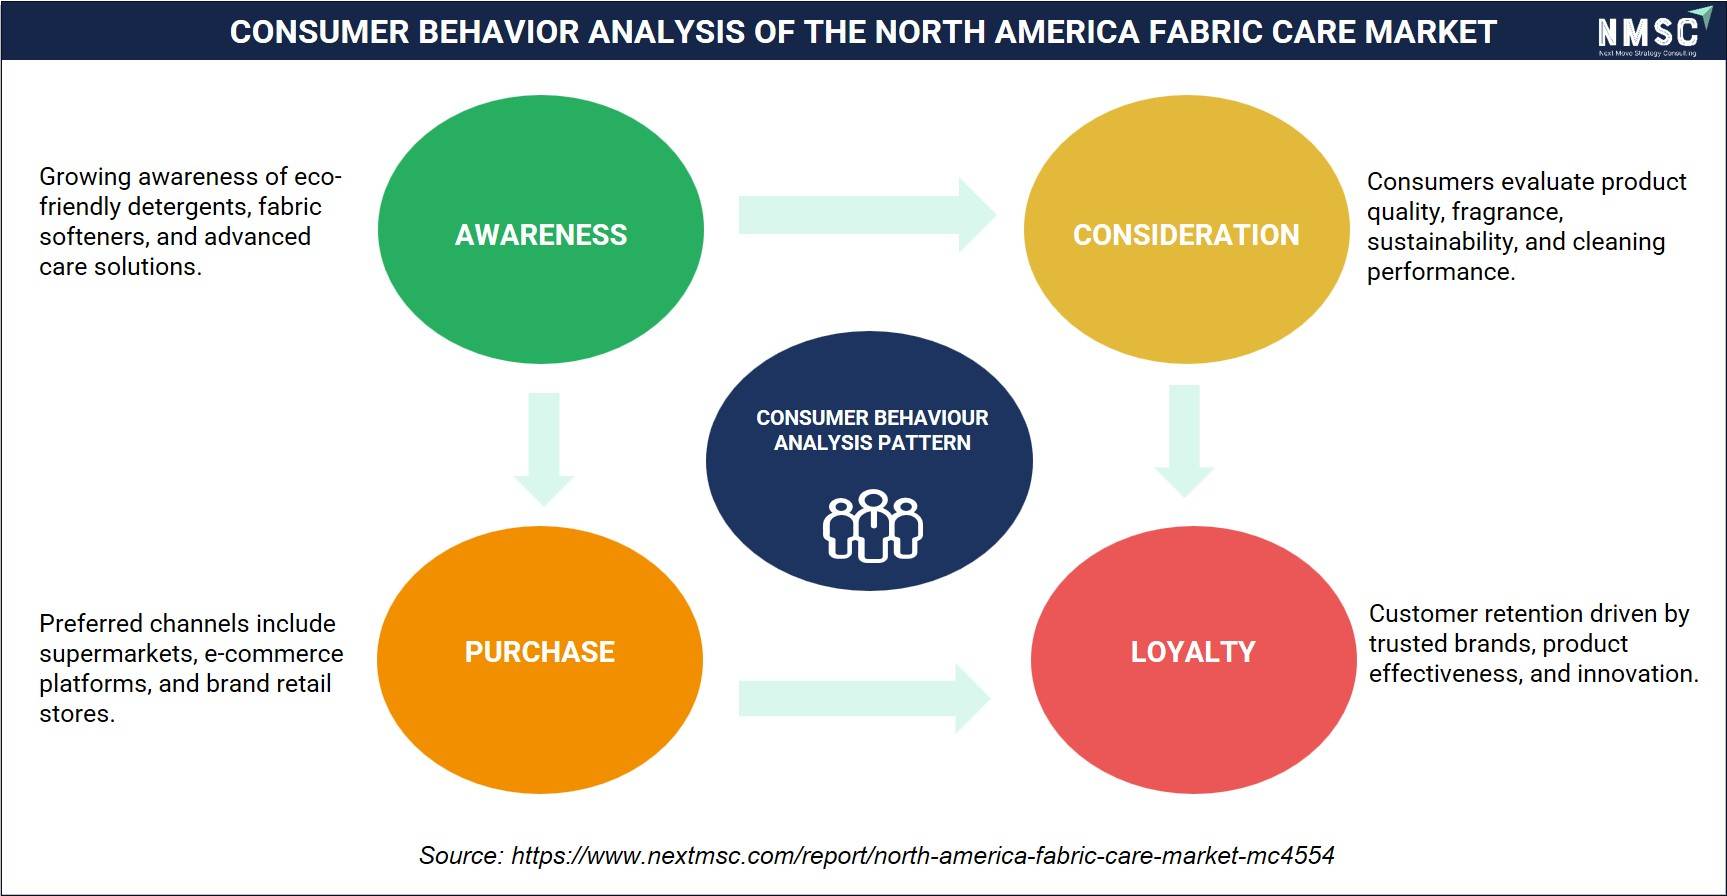
The above consumer behavior analysis maps the key decision-making stages, such as awareness, consideration, purchase, and loyalty, shaping the North America fabric care market. From our analysis, we observed that the awareness stage reflects growing recognition of eco-friendly detergents, fabric softeners, and advanced care solutions, while the consideration phase involves consumer evaluation of product quality, fragrance, sustainability, and cleaning performance. During purchase, preferred channels include supermarkets, e-commerce platforms, and brand retail stores, whereas customer retention is ultimately driven by trusted brands, product effectiveness, and innovation.
Which Country is Dominating the North America Fabric Care Market?
Based on our market evaluation, we found that the U.S. dominates the North America market owing to its high household spending, strong consumer preference for premium laundry products, and widespread adoption of advanced washing appliances. Demand is further supported by increasing awareness of fabric hygiene, convenience-focused lifestyles, and growing interest in specialized detergents, fabric conditioners, and eco-friendly formulations. Additionally, the presence of leading manufacturers, continuous product innovation, and extensive retail and e-commerce distribution networks enables the U.S. to maintain its leadership across the regional market.
Which Country is Set to Witness the Fastest Growth?
We analysed that Canada is set to witness the fastest growth in the North America fabric care market as consumers increasingly prioritize premium, sustainable, and high-performance laundry solutions. Rising environmental awareness and growing demand for eco-friendly detergents and concentrated formulations are reshaping purchasing preferences. This trend is further supported by expanding e-commerce penetration, increasing adoption of advanced laundry appliances, and continuous product innovation by leading manufacturers, enabling wider access to specialized fabric care products and accelerating market growth across the country.
Key Segments
By Product Type
-
Fabric Detergents
-
General Purpose
-
Baby Laundry Detergent
-
Delicate Laundry Detergent
-
-
Fabric Softeners/Conditioners
-
Stain Removers/Bleach
-
Sanitizer
-
Other Products
By Form
-
Liquid
-
Powder
-
Unit-Dose
-
Pods
-
Sachets
-
-
Sheet & Wipe
-
Spray
By Nature
-
Conventional
-
Eco-friendly / Organic
By Price Tier
-
Value
-
Mid-range
-
Premium
By Distribution Channel
-
Online
-
Marketplaces
-
Brand E-com
-
Quick Commerce
-
-
Offline
-
Supermarkets
-
Hypermarkets
-
Department Stores
-
By End-User
-
Residential
-
Commercial
-
Others
By Region
-
U.S.
-
Canada
-
Mexico
Competitive Landscape
The North America Fabric Care Market hosts the world's most concentrated and intensely contested FMCG competitive landscape, where a small number of legacy multinational corporations have historically dominated category revenue through mass retail distribution scale, brand equity depth, and formulation innovation investment. This incumbent oligopoly is being structurally challenged by a new generation of direct-to-consumer eco-brands leveraging e-commerce channel economics, plastic-free format innovation, and authentic sustainability positioning to capture disproportionate share of the fastest-growing consumer segments. The resulting competitive tension between legacy retail power and digital-native challenger agility defines North America fabric care competitive dynamic for the entire forecast period.
Strategic Developments:
-
April 2025 – Henkel Corporation launched new concentrated liquid formulas for its all, Persil, and Snuggle laundry brands across North America. Featuring smaller bottles with 50% recycled plastic and reduced water and CO2 emissions, the initiative strengthens Henkel's sustainability strategy while enhancing product efficiency and reinforcing its leadership in the regional fabric care market.
-
February 2026 – The Procter & Gamble Company (Tide) launched Tide evo, the world's first fiber-detergent laundry tile, featuring a 100% concentrated, waterless six-layer design that delivers powerful cleaning in cold water. Packaged in recyclable paper, the innovation advances sustainability, improves accessibility, and reinforces P&G's leadership in North America's evolving fabric care market.
Key Players of the North America Fabric Care Market:
-
Henkel Corporation
-
Reckitt
-
The Clorox Company
-
S. C. Johnson & Son, Inc.
-
Church & Dwight Co., Inc.
-
Colgate-Palmolive Company
-
Kao Corporation
-
Diversey, Inc.
-
Amway Corporation
-
Industrias AlEn, S.A. de C.V.
-
Tru Earth Environmental Products Inc.
-
Dropps, Inc.
-
Nellie's All-Natural Inc.
Key players shaping the North America Fabric Care Market include The Procter & Gamble Company, Unilever, Henkel Corporation, Reckitt, The Clorox Company, S. C. Johnson & Son, Inc., Church & Dwight Co., Inc., Colgate-Palmolive Company, Kao Corporation, Diversey, Inc., Amway Corporation, Industrias AlEn, S.A. de C.V., Tru Earth Environmental Products Inc., Dropps, Inc., and Nellie's All-Natural Inc., spanning the full spectrum from legacy mass-retail incumbents to digital-native eco-brand challengers competing across format innovation, sustainability positioning, and e-commerce channel investment to capture North America's evolving fabric care revenue opportunity.
Price Point Analysis of the North America Fabric Care Market:
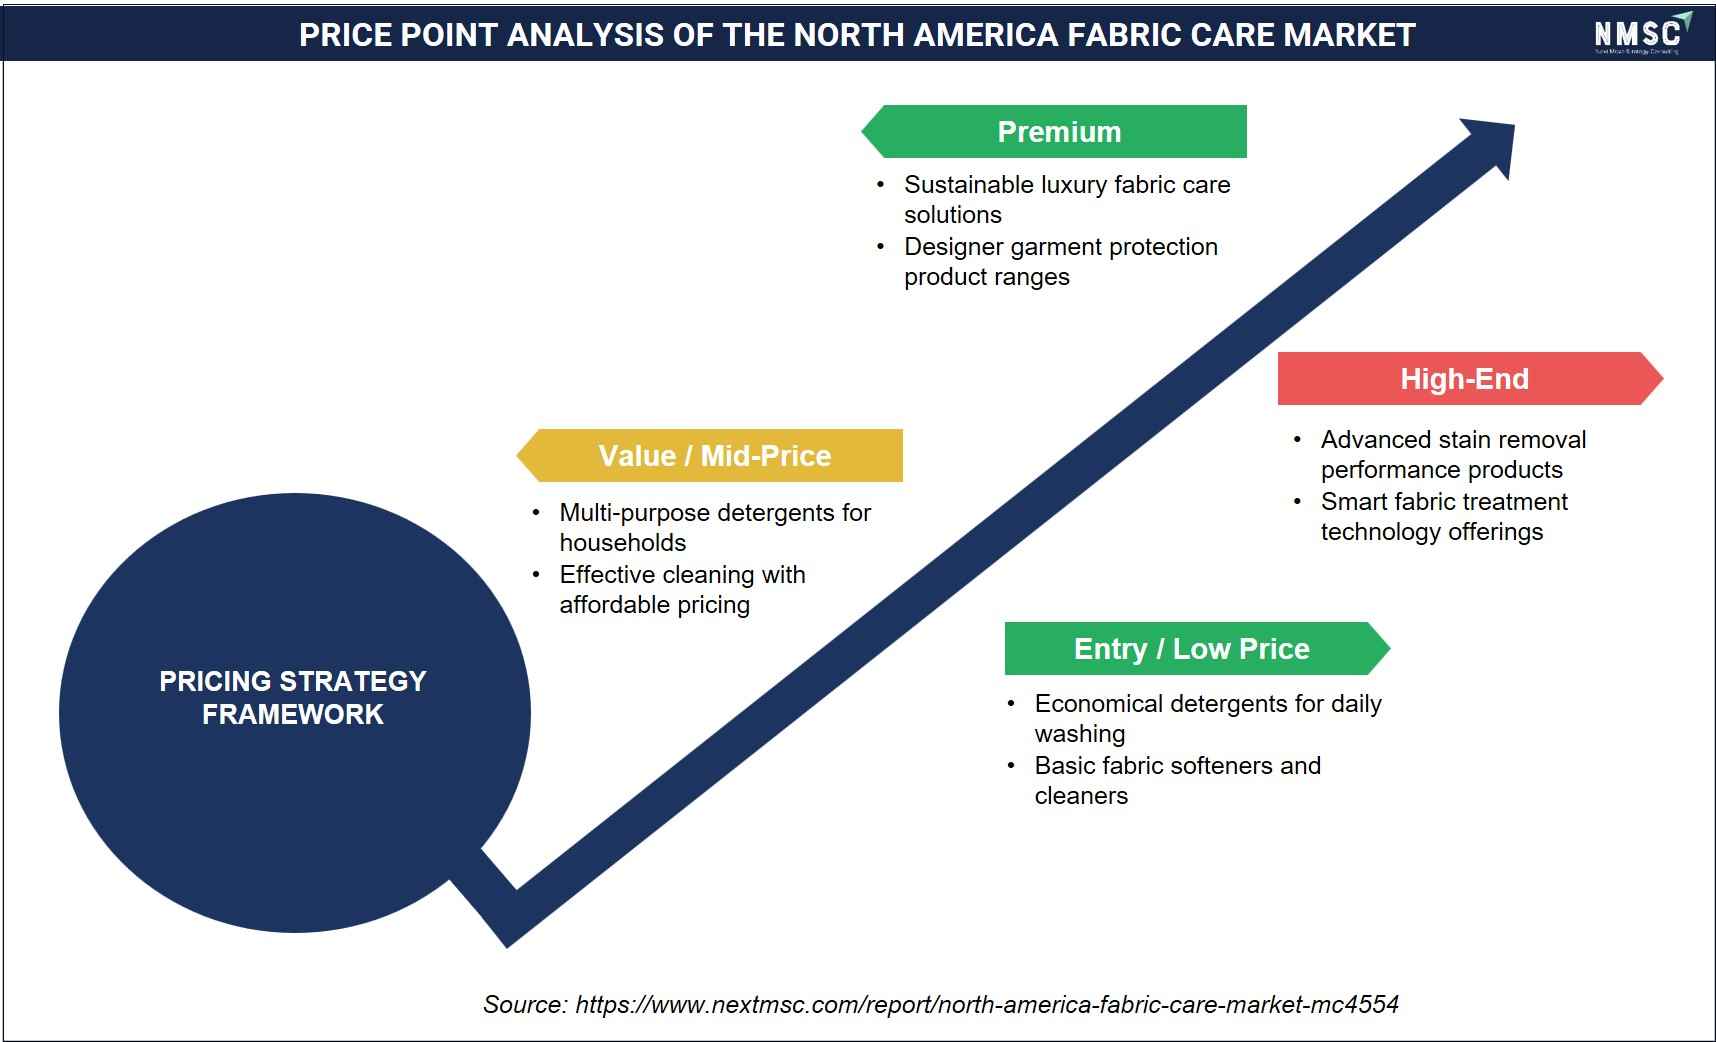
The above price point analysis maps the key pricing tiers, such as entry or low price, value or mid-price, premium, and high-end, shaping the North America fabric care market. From our analysis, we observed that the value or mid-price segment captures the largest consumer base, as affordability and everyday usability remain top priorities for most households, while premium and high-end segments are steadily gaining traction among urban consumers seeking specialized fabric protection and eco-friendly formulations. Sustainable luxury solutions and advanced stain removal technologies are increasingly influencing purchasing decisions across all tiers.
Key Benefits for Stakeholders
Next Move Strategy Consulting (NMSC) presents a comprehensive analysis of the North America Fabric Care Market, covering historical performance from 2020 through 2025 and detailed revenue forecasts extending through 2035 across the United States, Canada, and Mexico. The report delivers quantitative projections and qualitative insights across all primary segments, including product type, form, nature, price tier, distribution channel, and end-user categories. Strategic analysis encompasses legacy brand competitive dynamics, eco-brand disruption trajectories, format innovation impact, and demographic opportunity assessment, equipping stakeholders with the research foundation for informed investment and market strategy decisions.
Manufacturers, investors, and retail partners engaged in the North America Fabric Care Market gain strategic value from NMSC's competitive landscape benchmarking, e-commerce channel growth analysis, and format innovation impact assessment. Brand operators access actionable intelligence on unit-dose pod market share dynamics, plastic-free format adoption trajectories, and Hispanic consumer segment opportunity sizing that directly inform portfolio investment priorities. Retailers gain structured insights into private-label competitive positioning, channel shift velocity from offline to online formats, and category management optimization strategies enabling evidence-based supplier selection and shelf space allocation across North America's competitive fabric care retail landscape.
|
Parameters |
Details |
|
Customization Scope |
Free customization (equivalent to up to 80 analyst-working hours) after purchase. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |
|
Approach |
In-depth primary and secondary research; proprietary databases; rigorous quality control and validation measures. |
|
Analytical Tools |
Porter's Five Forces, SWOT, value chain, and Harvey ball analysis to assess competitive intensity, stakeholder roles, and relative impact of key factors. |
Conclusion
The North America Fabric Care Market, despite its 3.21% CAGR reflecting structural market maturity, represents the region with the largest absolute revenue opportunity in this report series, projecting USD 27.76 billion by 2035. Growth is no longer a volume story — it is a format transformation, sustainability disruption, and demographic evolution narrative where eco-brand challengers including Tru Earth Environmental Products Inc., Dropps, Inc., and Nellie's All-Natural Inc. are capturing disproportionate growth at legacy incumbents' expense through e-commerce-enabled direct-to-consumer models. Strategic success requires simultaneous defense of mass retail revenue and aggressive investment in digital, eco-certified, and Hispanic market segment development.
About the Author
 Mayurima Roy
— Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

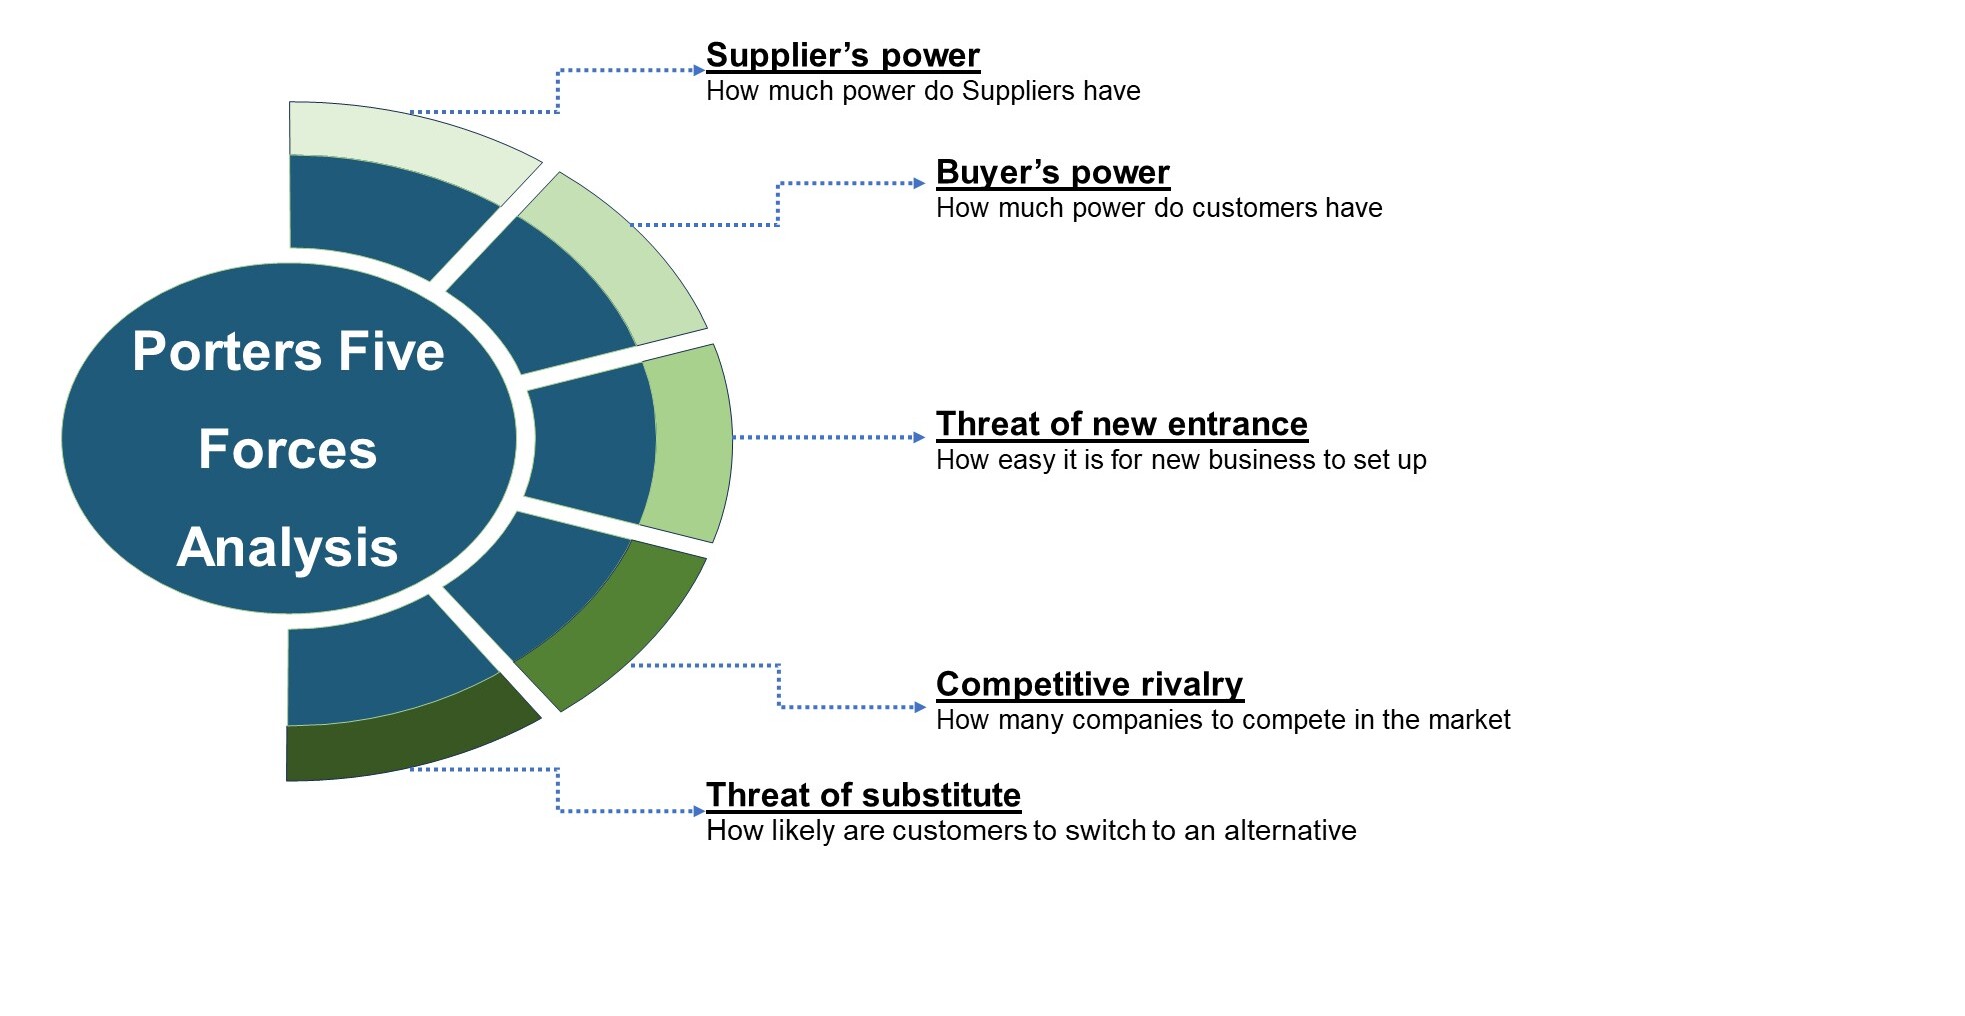
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.




 Speak to Our Analyst