NVMe-TCP Market

NVMe-TCP market size was USD 2.15 billion in 2025, projected to reach USD 16.85 billion by 2035 at a 22.7% CAGR from 2026 to 2035, per this market report.

Download Free Sample PDF
Base Year (2025)
$2.15 Billion
Forecast (2035)
$16.85 Billion
CAGR (2026-2035)
22.7%
Top Region
North America

What Is the NVMe-TCP Market Size?

The global NVMe-TCP market size was valued at USD 2.15 billion in 2025 and is estimated at USD 2.68 billion in 2026, forecast to reach USD 16.85 billion by 2035, expanding at a 22.7% CAGR between 2026 and 2035. North America leads with approximately 42% share, while Hardware dominates the component landscape with approximately 61% share.

We observed that AI inference and training workloads are pushing enterprises to standardize on NVMe over TCP as a cost-efficient alternative to proprietary RDMA fabrics and legacy SAN architectures.

NVMe-TCP Market Revenue Forecast

Values in USD Billion

2025 $2.15 Billion
2025
2026 $2.64 Billion
2026
2027 $3.24 Billion
2027
2028 $3.97 Billion
2028
2029 $4.87 Billion
2029
2030 $5.98 Billion
2030
2031 $7.34 Billion
2031
2032 $9.00 Billion
2032
2033 $11.05 Billion
2033
2034 $13.55 Billion
2034
2035 $16.85 Billion
2035

Key Takeaways

By Component: Hardware held the largest share of approximately 61% (USD 1.31 billion) in 2025; Services is the fastest-growing sub-segment at 25.8% CAGR from 2026–2035.

By Deployment Model: On-Premises held the largest share of approximately 56% (USD 1.20 billion) in 2025; Hybrid is the fastest-growing sub-segment at 29.3% CAGR from 2026–2035.

By Organization Size: Large Enterprises held the largest share of approximately 71% (USD 1.53 billion) in 2025; Small and Medium Enterprises is the fastest-growing sub-segment at 25.9% CAGR from 2026–2035.

By Application: AI and Machine Learning Workloads held the largest share of approximately 24% (USD 0.52 billion) in 2025; High Performance Computing is the fastest-growing sub-segment at 26.7% CAGR from 2026–2035.

By End User: Cloud Service Providers and Hyperscalers held the largest share of approximately 29% (USD 0.62 billion) in 2025; Financial Services is the fastest-growing sub-segment at 22.9% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 42% revenue share (USD 0.90 billion) in 2025.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 25.6% during 2026–2035.

Dominant Country: U.S. led with approximately USD 0.77 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 29.5% CAGR from 2026–2035.

Market Opportunity: The NVMe-TCP market is expected to create an absolute dollar opportunity of USD 14.17 billion between 2026 and 2035, presenting significant investment potential across AI-ready, disaggregated storage infrastructure.

According to NMSC analysis, storage vendors are increasingly embedding native NVMe-TCP support into flagship array controllers rather than treating it as an add-on protocol, a shift that is compressing the performance gap between Ethernet-based and RDMA-based fabric deployments.

What Does the NVMe-TCP Market Encompass?
The NVMe-TCP market encompasses hardware, software, and services that enable NVMe storage commands to run over standard TCP/IP Ethernet networks, eliminating the need for specialized RDMA-capable network interface cards or dedicated Fibre Channel fabrics. Our assessment indicates that the scope spans storage arrays, network interface cards, protocol stack software, and deployment and support services purchased by large enterprises and small and medium enterprises across cloud, financial services, telecommunications, and healthcare end markets, supported by the 20 companies profiled in this report.
The category has evolved from an emerging protocol standard into a mainstream storage networking option as AI workloads expose the cost and complexity limitations of proprietary RDMA fabrics. Regulatory and standards frameworks, including specifications maintained by the NVM Express organization governing the NVMe-TCP transport binding, continue to shape interoperability requirements across vendor implementations. We observed that technology adoption is shifting toward software-defined, disaggregated storage architectures that embed NVMe-TCP natively rather than as a bolt-on capability, redefining sourcing criteria across the NVMe-TCP market.

ECOSYSTEM ANALYSIS OF THE NVME-TCP MARKET

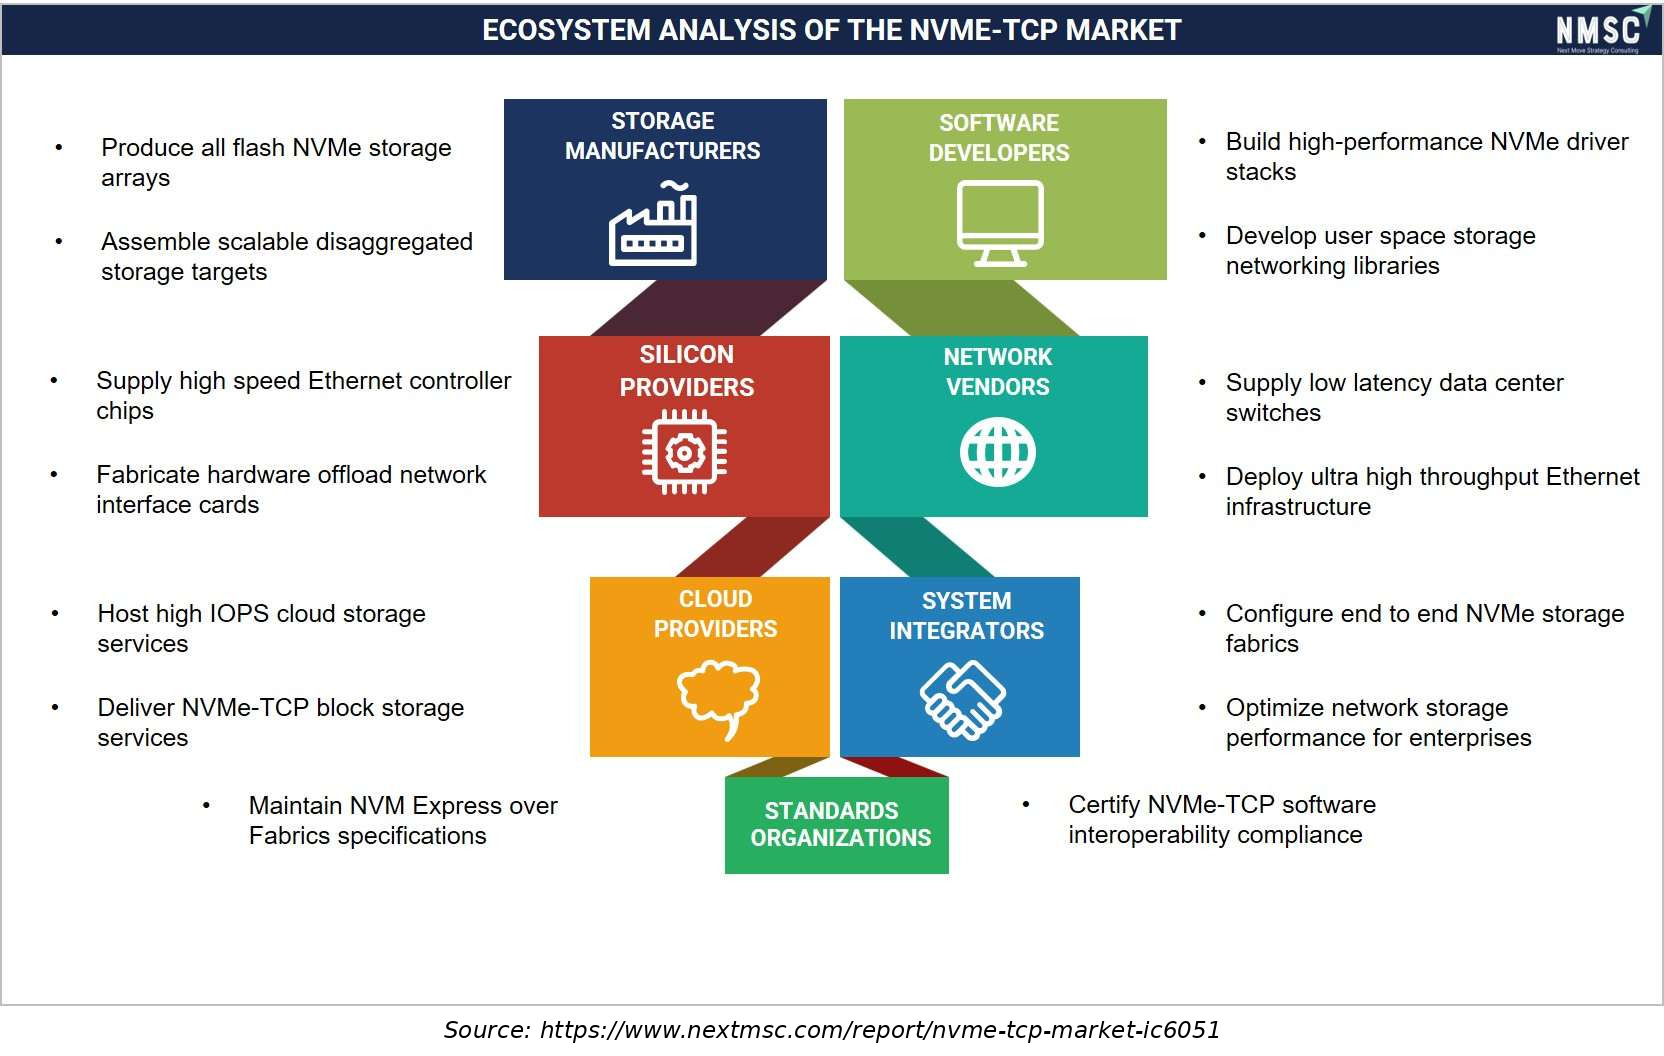
The ecosystem analysis of the NVMe-TCP market illustrates the key stakeholders contributing to the development and adoption of NVMe over TCP technology. The ecosystem includes storage manufacturers, software developers, silicon providers, network vendors, cloud providers, system integrators, and standards organizations, highlighting their interconnected roles in building, deploying, and standardizing NVMe-TCP-based storage infrastructure.

Market Drivers & Dynamics

Interactive Dataset
AI training and inference workload storage demand growth driver +5.8% Global 2026-2035
Native NVMe-TCP integration into flagship storage array controllers driver +3.4% North America, Europe 2026-2032
Cost and complexity advantages over proprietary RDMA fabrics driver +4.1% Global 2026-2035
Hyperconverged infrastructure external storage disaggregation trend driver +2.6% North America, Asia-Pacific 2026-2032
Cloud service provider and hyperscaler infrastructure expansion driver +3.9% Asia-Pacific, North America 2026-2035
Rising software-defined storage adoption in emerging markets driver +2.2% Asia-Pacific, Latin America 2026-2035
Legacy SAN and Fibre Channel installed base inertia restraint -1.8% North America, Europe 2026-2032
Network latency variability versus dedicated RDMA fabrics restraint -1.3% Global 2026-2030
Limited technical expertise for protocol migration in smaller enterprises restraint -0.9% Global 2028-2035
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the NVMe-TCP Market?

AI training and inference workload storage demand growth is the primary driver of the market. We observed that Lightbits Labs, Inc. reported accelerated customer adoption across financial services, e-commerce, neo-clouds, and cloud service providers in 2025 as organizations confronted the performance limits and rising costs of legacy SAN and hyperconverged infrastructure architectures. This behavioral shift continues to anchor baseline demand for NVMe-TCP hardware and software across AI-focused enterprise and cloud deployments.

How Is Native Array Integration Driving NVMe-TCP Market Growth?

Storage OEMs embedding NVMe-TCP support natively into flagship array controllers is accelerating market growth by removing the need for separate protocol licensing or specialized hardware. Our assessment indicates that this integration trend, exemplified by Dell Technologies Inc.'s PowerStore Gen 3 platform reset in May 2026, is compressing adoption timelines for enterprises replacing legacy SAN infrastructure during scheduled refresh cycles.

Growth Inhibitors

What Is Restraining NVMe-TCP Market Expansion?

Legacy SAN and Fibre Channel installed base inertia restrains broader market expansion, particularly among enterprises with substantial existing capital investment in Fibre Channel switching infrastructure. We found that organizations with mature Fibre Channel deployments face longer replacement cycles and higher switching costs compared with greenfield NVMe-TCP deployments, slowing protocol transition relative to newly built AI and cloud infrastructure.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Hardware 2025: $1.31 Billion | 2035: $8.76 Billion
Hardware
Software 2025: $0.52 Billion | 2035: $4.89 Billion
Software
Services 2025: $0.32 Billion | 2035: $3.20 Billion
Services
Hardware $1.31 Billion $8.76 Billion 20.9%
Software $0.52 Billion $4.89 Billion 25.2%
Services $0.32 Billion $3.20 Billion 25.8%

Which Component Segment Dominates the NVMe-TCP Market?

Hardware led the market with USD 1.31 billion in 2025, encompassing storage arrays, network interface cards, and SSDs purchased as core infrastructure for NVMe-TCP deployments. We observed that Services is the fastest-growing component, expanding at a 25.8% CAGR from 2026 to 2035, as deployment, integration, and support contracts scale alongside enterprises transitioning from legacy SAN architectures to NVMe-TCP-based storage.

2025 (USD Billion)
2035 (USD Billion)
On-Premises
Cloud-Based
Hybrid
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
On-Premises $10.0 USD Billion $40.0 USD Billion 25.0%
Cloud-Based $17.1 USD Billion $51.1 USD Billion 11.0%
Hybrid $24.2 USD Billion $62.2 USD Billion 25.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Deployment Model.

Unlock Full Data

Which Deployment Model Segment Is Growing Fastest in the NVMe-TCP Market?

On-Premises remained the largest deployment model in 2025, reflecting continued enterprise investment in owned data center infrastructure for latency-sensitive workloads. Our findings suggest that Hybrid is the fastest-growing deployment model, registering a 29.3% CAGR from 2026 to 2035, as enterprises increasingly extend NVMe-TCP storage architectures across both on-premises and cloud environments to support distributed AI workload placement.

2025 (USD Billion)
2035 (USD Billion)
Large Enterp
Small and Me
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Large Enterprises $10.0 USD Billion $40.0 USD Billion 27.0%
Small and Medium Enterprises $17.1 USD Billion $51.1 USD Billion 9.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Organization Size.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
AI and Machi
Database and
Virtualizati
High Perform
Backup and D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
AI and Machine Learning Workloads $10.0 USD Billion $40.0 USD Billion 14.0%
Database and Analytics $17.1 USD Billion $51.1 USD Billion 24.0%
Virtualization and Cloud Infrastructure $24.2 USD Billion $62.2 USD Billion 22.0%
High Performance Computing $31.3 USD Billion $73.3 USD Billion 12.0%
Backup and Disaster Recovery $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Application.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Cloud Servic
Enterprise D
Financial Se
Telecommunic
Healthcare
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Cloud Service Providers and Hyperscalers $10.0 USD Billion $40.0 USD Billion 24.0%
Enterprise Data Centers $17.1 USD Billion $51.1 USD Billion 22.0%
Financial Services $24.2 USD Billion $62.2 USD Billion 20.0%
Telecommunications $31.3 USD Billion $73.3 USD Billion 22.0%
Healthcare $38.4 USD Billion $84.4 USD Billion 13.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User.

Unlock Full Data

Which End User Segment Is Growing Fastest in the NVMe-TCP Market?

Cloud Service Providers and Hyperscalers remained the leading end user segment, reaching USD 0.62 billion in 2025 on sustained AI infrastructure buildout by cloud operators. We found that Financial Services, Telecommunications, Healthcare, and Media and Entertainment each registered a 22.9% CAGR, closely trailing Cloud Service Providers and Hyperscalers at 25.2%, as latency-sensitive transactional and real-time workloads increasingly specify NVMe-TCP storage for predictable performance.

Growth Opportunities

Our analysis shows that three forward-looking opportunities stand out for stakeholders positioning within the NVMe-TCP market over the 2026-2035 forecast period.

How Can Native Protocol Integration Unlock Value for Storage OEMs?

Storage OEMs that embed NVMe-TCP support natively into flagship array controllers, following the approach of Dell Technologies Inc.'s PowerStore Gen 3 reset, can capture recurring hardware refresh revenue from enterprises replacing legacy SAN infrastructure. This positions integrated storage vendors to capture share from competitors still offering NVMe-TCP as a separate licensed add-on.

Where Does Software-Defined Storage Create Opportunity for AI Cloud Providers?

Software-defined, NVMe-TCP-native storage platforms present a whitespace opportunity for AI cloud and neo-cloud providers seeking commodity-hardware alternatives to proprietary fabrics. Vendors following Lightbits Labs, Inc.'s approach of embedding NVMe-TCP natively into disaggregated block storage stand to capture share from providers relying on costlier RDMA-based architectures.

How Can Hyperconverged Infrastructure Integration Expand Enterprise Reach?

Hyperconverged infrastructure vendors that deepen integration with external NVMe-TCP storage arrays can capture recurring revenue from enterprises seeking independent compute and storage scaling. Vendors following Nutanix, Inc.'s external storage integration approach stand to capture share from customers previously limited to tightly coupled compute-storage architectures.

PORTER'S FIVE FORCES ANALYSIS OF THE NVME-TCP MARKET

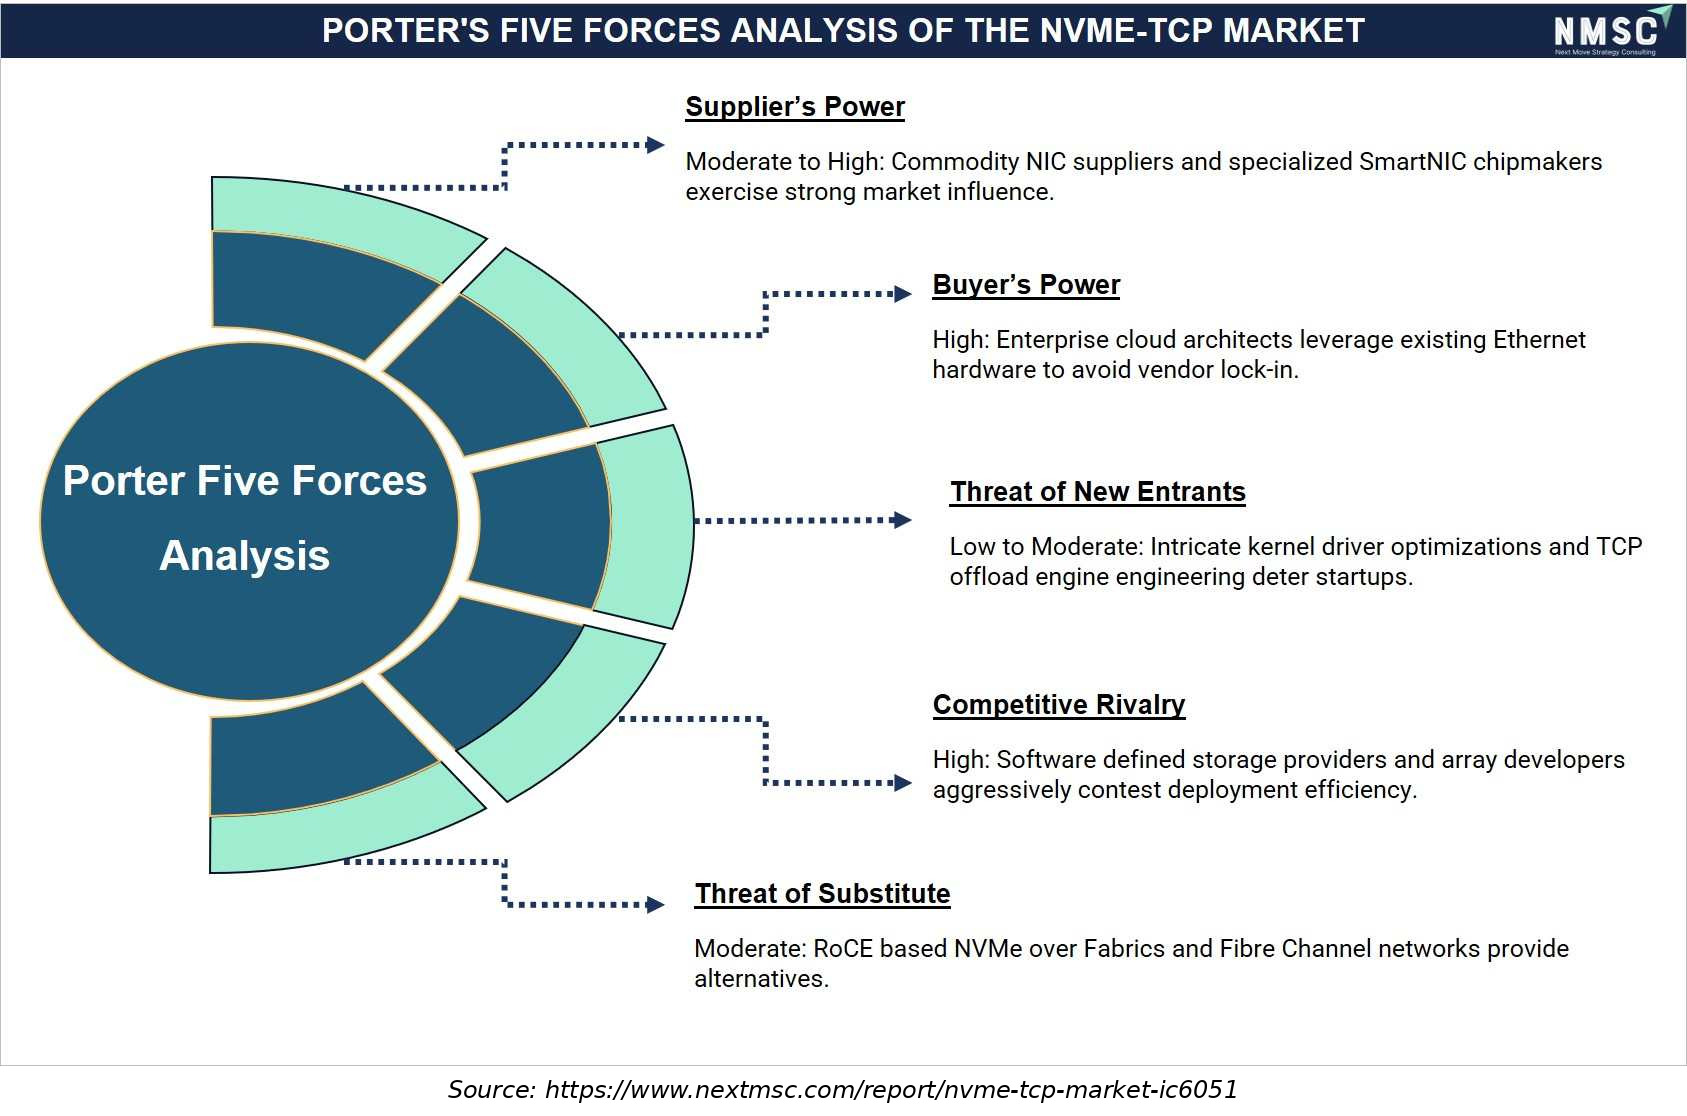
The Porter’s Five Forces analysis of the NVMe-TCP market assesses the competitive dynamics influencing market growth and attractiveness. It examines supplier and buyer bargaining power, the threat of new entrants, the threat of substitute technologies, and competitive rivalry. The analysis highlights how technology requirements, infrastructure dependencies, alternative storage protocols, switching costs, and competition among established vendors influence pricing, adoption, innovation, and strategic positioning in the NVMe-TCP market.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Asia-Pacific
Europe
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Asia-Pacific $17.1 USD Billion $51.1 USD Billion 27.0%
Europe $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the NVMe-TCP market features a moderately consolidated competitive landscape, with diversified storage OEMs competing alongside silicon and networking specialists and dedicated software-defined storage pioneers across the Industry.

Dimension Description
Market Structure Moderately consolidated; large storage OEMs profiled in this report compete alongside silicon and NIC vendors and specialized software-defined storage providers, with no single vendor commanding a majority share.
Innovation Focus Native controller-level NVMe-TCP integration, disaggregated software-defined storage, hyperconverged infrastructure external storage support, and AI-optimized data path acceleration dominate current innovation pipelines.
M&A Activity Selective corporate repositioning and strategic capital activity, exemplified by Everpure, Inc.'s February 2026 corporate rebrand from Pure Storage, Inc. to reposition as an enterprise data platform provider.

How Do Companies Compete in the NVMe-TCP Market?

Companies compete primarily on native protocol integration depth, hardware efficiency, and software-defined flexibility across the Industry. Large storage OEMs such as Dell Technologies Inc. and NetApp, Inc. leverage broad array portfolios spanning multiple protocol options to serve enterprise customers, while dedicated software-defined storage providers such as Lightbits Labs, Inc. compete on protocol-native architecture built specifically for NVMe-TCP performance and cost efficiency.

Which Competitive Archetypes Dominate the NVMe-TCP Market?

Three archetypes dominate the market: diversified storage OEMs offering multi-protocol array portfolios, silicon and networking specialists enabling protocol offload, and dedicated software-defined storage pioneers. Dell Technologies Inc. and NetApp, Inc. exemplify the diversified OEM archetype, NVIDIA Corporation and Marvell Technology, Inc. exemplify the silicon specialist archetype, and Lightbits Labs, Inc. exemplifies the protocol-native software archetype serving AI cloud and enterprise customers.

How Are Companies Differentiating Through Innovation in NVMe-TCP?

Innovation and differentiation strategy increasingly center on native controller-level protocol integration and disaggregated architecture design. Lightbits Labs, Inc. exemplifies this direction as the inventor of the NVMe over TCP storage protocol, embedding it natively into software-defined block storage. Our analysis shows that vendors unable to demonstrate native protocol support risk exclusion from AI infrastructure procurement shortlists as enterprises prioritize commodity-hardware compatibility.

What M&A and Repositioning Activity Is Shaping the NVMe-TCP Market?

Corporate repositioning and strategic partnerships continue to reshape competitive positioning within the Industry. Everpure, Inc.'s February 2026 rebrand from Pure Storage, Inc., alongside its acquisition of data intelligence company 1touch, illustrates how established storage vendors are broadening their platform positioning to compete for AI-driven enterprise data infrastructure spending beyond traditional storage array sales.

Competitive Dynamics and M&A Landscape

Recent strategic moves, partnerships, and acquisitions shaping the NVMe-TCP Market.

February 2026 Everpure, Inc. Corporate Rebrand Everpure, Inc.'s February 2026 corporate rebrand from Pure Storage, Inc. to reposition as an enterprise data platform provider.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping product innovation, protocol integration, and platform strategy within the global NVMe-TCP market.

Dell Technologies Inc. NetApp, Inc. Everpure, Inc. International Business Machines Corporation Hewlett Packard Enterprise Company Hitachi Vantara Corporation Huawei Technologies Co., Ltd. NVIDIA Corporation Marvell Technology, Inc. Broadcom Inc. Intel Corporation Lightbits Labs, Inc. (inventor of the NVMe over TCP protocol) Nutanix, Inc. VMware LLC Kioxia Corporation Samsung Electronics Co., Ltd. Western Digital Corporation Solidigm Micron Technology, Inc. Pavilion Data Systems, Inc.

Latest Developments

We found that recent activity within the NVMe-TCP market is concentrated on protocol-native platform recognition and enterprise deployment expansion, reflecting the industry's broader shift toward AI-ready, software-defined storage.

Date Event
April 2026 Nutanix detailed its integration with external storage arrays over NVMe/TCP, positioning standard Ethernet as an alternative to Fibre Channel. The company highlighted commodity networking, simpler operations and hybrid-cloud alignment, reinforcing NVMe/TCP as a practical storage-networking option for enterprise environments.
March 2026 Nutanix documented integration of its Cloud Platform with external arrays including Everpure FlashArray and Dell PowerStore using NVMe/TCP over standard Ethernet. The architecture enables independent scaling of compute and storage and provides a migration path from Fibre Channel-based external storage environments.
November 2025 Hitachi Vantara launched VSP One Block High End, an all-flash NVMe storage platform designed for mission-critical and AI workloads. The system supports up to 12 controllers and 288 60TB SSDs, with connectivity including 100G NVMe over TCP and 64G Fibre Channel.

Investment Opportunities

What Capital Inflows Are Targeting the NVMe-TCP Market?

Capital inflows into the market are increasingly directed toward software-defined storage platforms and native protocol integration capability. We observed that Lightbits Labs, Inc. is backed by enterprise technology investors including Cisco Investments, Dell Technologies Capital, Intel Capital, Lenovo, and Micron, reflecting sustained strategic investor confidence in NVMe-TCP-native storage infrastructure.

How Is Infrastructure Investment Supporting NVMe-TCP Deployment?

Infrastructure investment is expanding NVMe-TCP-compatible data center capacity across North America, Europe, and Asia-Pacific to serve rising AI and cloud workload demand. Our findings suggest that providers are investing in commodity Ethernet infrastructure and software-defined storage platforms, reducing dependence on specialized RDMA-capable networking hardware for high-performance storage deployments.

What ESG Considerations Are Shaping NVMe-TCP Investment Decisions?

Environmental, social, and governance considerations increasingly influence investment decisions, with power efficiency and hardware utilization as key criteria for NVMe-TCP deployments. We found that software-defined NVMe-TCP platforms deliver measurably higher hardware efficiency than legacy software-defined storage architectures, reducing infrastructure footprint, power consumption, and operational complexity. Investors increasingly favor vendors demonstrating validated efficiency gains as a governance indicator alongside performance metrics.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and infrastructure-planning decisions across the NVMe-TCP industry. Our analysis shows that detailed component, deployment model, and application breakdowns help IT teams align platform specifications with rising AI workload storage requirements while identifying underserved segments for expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the NVMe-TCP supply chain. We observed that the report's regional and segment-level growth differentials help identify which vendors are best positioned to capture above-market growth in Asia-Pacific and High Performance Computing categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including native controller-level protocol integration, hyperconverged infrastructure compatibility, and hybrid deployment support, that are reshaping the industry. Our findings suggest that this analysis helps product teams prioritize development roadmaps around software-defined, protocol-native architectures increasingly required by AI infrastructure procurement processes.

Key Market Segments Evaluated

By Component

  • Hardware
  • Software
  • Services

By Deployment Model

  • On-Premises
  • Cloud-Based
  • Hybrid

By Organization Size

  • Large Enterprises
  • Small and Medium Enterprises

By Application

  • AI and Machine Learning Workloads
  • Database and Analytics
  • Virtualization and Cloud Infrastructure
  • High Performance Computing
  • Backup and Disaster Recovery
  • Content Delivery and Media

By End User

  • Cloud Service Providers and Hyperscalers
  • Enterprise Data Centers
  • Financial Services
  • Telecommunications
  • Healthcare
  • Government
  • Media and Entertainment
  • Other End Users

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The long-term outlook for the market remains strongly positive, with global revenue projected to expand nearly eightfold from USD 2.15 billion in 2025 to USD 16.85 billion by 2035 at a 22.7% CAGR. We observed that sustained AI infrastructure buildout, native array protocol integration, and rising Asia-Pacific cloud adoption will continue underpinning demand across enterprise, cloud, and financial services applications through the forecast period.

What Strategic Positioning Should NVMe-TCP Vendors Pursue?

Vendors should prioritize native controller-level protocol integration and software-defined architecture to secure long-term enterprise and cloud provider contracts. Our assessment indicates that vendors investing early in hybrid deployment support and hyperconverged infrastructure compatibility will be best positioned to capture premium pricing within the NVMe-TCP market.

How Attractive Is the NVMe-TCP Market for New Investment?

The NVMe-TCP industry presents a highly attractive investment case, supported by a USD 14.17 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and High Performance Computing categories. We found that investment attractiveness is highest for vendors combining protocol-native architecture with scaled cloud infrastructure, positioning them to serve both large enterprise and small and medium enterprise buyer segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor legacy SAN and Fibre Channel installed base inertia, network latency variability versus dedicated RDMA fabrics, and limited technical expertise for protocol migration among smaller enterprises as key risks to the NVMe-TCP market. Our analysis shows that vendors unable to demonstrate native protocol support risk losing enterprise contracts to competitors with certified, software-defined platforms.

What Are the Key Growth Pathways for the NVMe-TCP Market?

Key growth pathways include expanding native controller-level protocol integration, scaling software-defined storage platforms for AI cloud providers, and deepening penetration into hybrid and hyperconverged infrastructure deployments. NMSC's analysis indicates that vendors pursuing these pathways while maintaining cost competitiveness for small and medium enterprises will be best positioned to capture the NVMe-TCP market's projected growth through 2035.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Gaurav Jaiswal

GAURAV JAISWAL

Founder & CEO

Yano Charge Private Limited

The EV Charging market research report provided by the NextMSC was exceptionally detailed and insightful. It offered a comprehensive analysis that proved to be a game-changer for our strategic planning. Truly a testament to the NextMSC’s expertise and thoroughness in EV market landscape & analysis.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖