Operational Database Management System Market Global Industry Analysis and Forecast (2026-2035)

Operational database management system market size is estimated at USD 102.08 billion in 2026, projected to reach USD 161.51 billion by 2035, growing at a CAGR of 5.23% from 2026 to 2035. Key drivers include cloud migration of transaction workloads, rising distributed SQL adoption, and expanding real-time application data serving demand, with North America leading the market and Asia-Pacific registering the fastest growth.

Download Free Sample PDF
Base Year (2025)
$95.47 Billion
Forecast (2035)
$161.51 Billion
CAGR (2026-2035)
5.2%
Top Country
North America

What Is the Operational Database Management System Market Size?

The global operational database management system market size was valued at USD 95.47 billion in 2025 and is estimated at USD 102.08 billion in 2026, forecast to reach USD 161.51 billion by 2035, expanding at a 5.23% CAGR between 2026 and 2035. North America leads with approximately 40% share, while Relational Databases dominate all other architectures with approximately 54% share.

We observed that growth is broad-based across every segmentation axis, with public cloud deployment and graph database adoption driving the most pronounced structural shifts through 2035.

Operational Database Management System Market Global Industry Analysis and Forecast (2026-2035) Revenue Forecast

Values in USD Billion

2025 $95.47 Billion
2025
2026 $102.08 Billion
2026
2027 $107.42 Billion
2027
2028 $113.04 Billion
2028
2029 $118.95 Billion
2029
2030 $125.17 Billion
2030
2031 $131.72 Billion
2031
2032 $138.60 Billion
2032
2033 $145.85 Billion
2033
2034 $153.48 Billion
2034
2035 $161.51 Billion
2035

Key Takeaways

By Architecture: Relational Databases held the largest share of approximately 54% (USD 51.55 billion) in 2025; Graph Databases is the fastest-growing sub-segment at a 10.6% CAGR from 2026–2035.

By Deployment: Public Cloud held the largest share of approximately 42% (USD 40.10 billion) in 2025; Edge and Embedded is the fastest-growing sub-segment at a 12.2% CAGR from 2026–2035.

By Operational Workload: Transaction Processing held the largest share of approximately 38% (USD 36.28 billion) in 2025; Real-Time Data Processing is the fastest-growing sub-segment at a 9.8% CAGR from 2026–2035.

By Revenue: Subscription Revenue held the largest share of approximately 46% (USD 43.92 billion) in 2025; Usage-Based Revenue is the fastest-growing sub-segment at a 10.4% CAGR from 2026–2035.

By End User Industry: BFSI held the largest share of approximately 23% (USD 21.96 billion) in 2025; Information Technology and Software is the fastest-growing sub-segment at a 7.3% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 40% revenue share (USD 38.19 billion) in 2025.

Fastest-Growing Region: Latin America is expected to register the highest CAGR of 10.1% during 2026–2035.

Dominant Country: The U.S. led with approximately USD 30.20 billion in 2025.

Fastest-Growing Country: India is the fastest-growing country at approximately 12.1% CAGR from 2026–2035.

Market Opportunity: The operational database management system market is expected to create an absolute dollar opportunity of USD 59.43 billion between 2026 and 2035, presenting significant investment potential across distributed SQL platforms and real-time data processing workloads.

According to NMSC analysis, enterprises are increasingly consolidating database procurement around cloud-native, multi-model platforms that combine relational, document, and key-value capability, a shift that favors full-platform vendors over single-model specialists as application modernization accelerates through 2035.

What Does the Operational Database Management System Market Encompass?

The operational database management system market encompasses software platforms that store, manage, and serve transactional and application data in real time, spanning relational, document, key-value, wide-column, graph, time-series, and multi-model architectures. Our assessment indicates that the scope spans on-premises, private cloud, public cloud, and edge deployment models sold to enterprises across BFSI, healthcare, retail, manufacturing, and technology sectors worldwide. The category has evolved from monolithic relational systems into a diverse, workload-specialized software category, driven by application modernization, microservices adoption, and rising demand for real-time transaction processing at global scale.
We observed that data residency and privacy regulations increasingly shape deployment architecture decisions, while cloud provider ecosystems inform database platform selection. NMSC's analysis indicates that technology adoption is shifting toward distributed SQL and multi-model platforms that combine transactional consistency with horizontal scalability, a structural shift redefining sourcing criteria across the operational database management system market.

Ecosystem Analysis of the Operational Database Management System Market

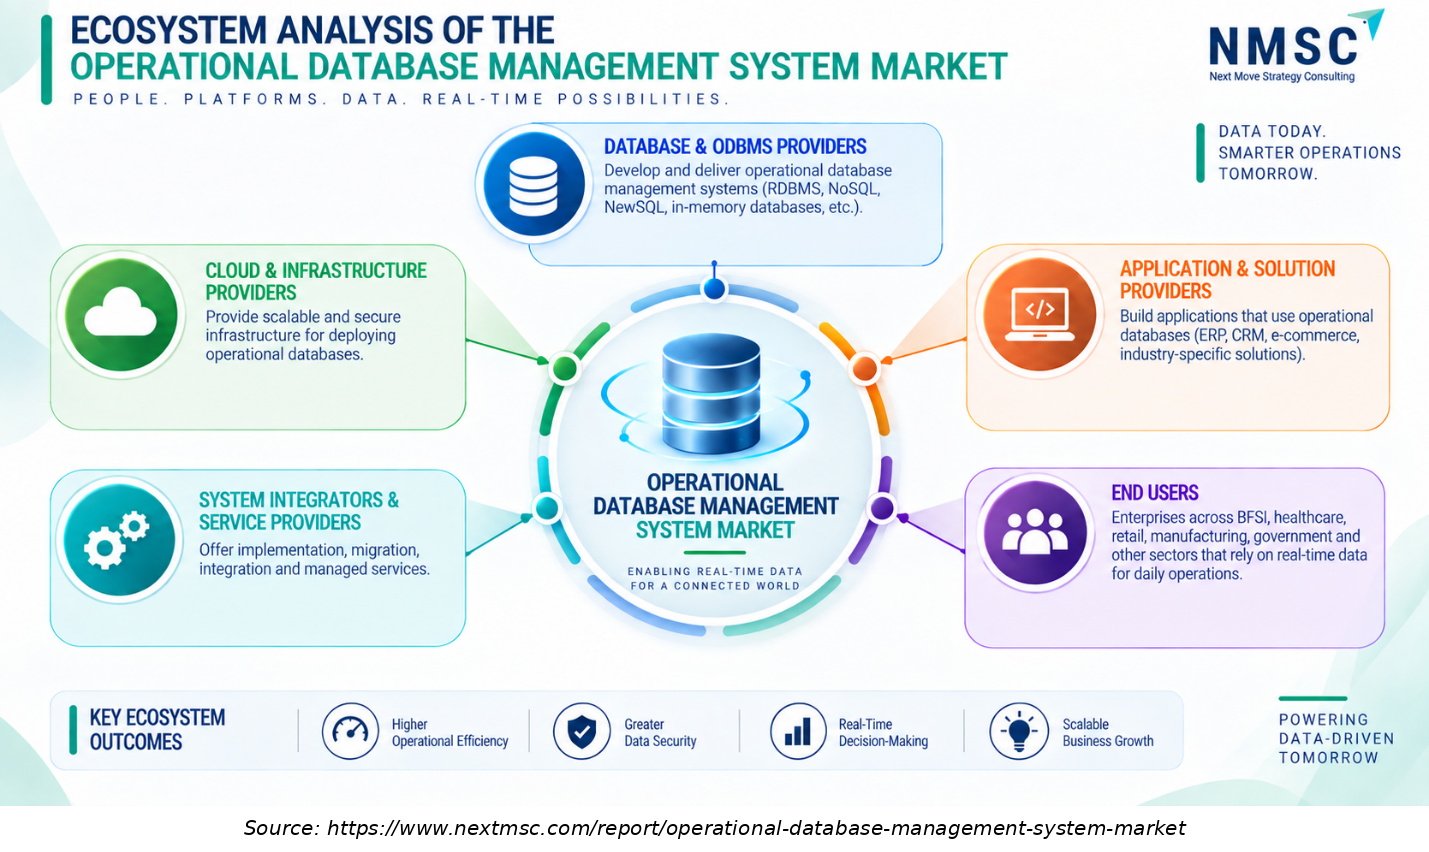
The infographic presents the Ecosystem Analysis of the Operational Database Management System Market, highlighting the key stakeholders shaping the market. It covers database and ODBMS providers, cloud and infrastructure providers, application and solution providers, system integrators, and enterprise end users. The interconnected ecosystem demonstrates how these participants support real-time data processing, secure operations, system integration, scalability, operational efficiency, and data-driven business decision-making.

Market Drivers & Dynamics

Interactive Dataset
Cloud migration of legacy transactional workloads driver +1.2% Global 2026–2035
Rising distributed SQL and horizontal scalability demand driver +0.9% North America, Asia-Pacific 2026–2032
Expanding real-time application data serving requirements driver +0.8% Global 2026–2032
Growing microservices and application modernization investment driver +0.7% North America, Europe 2026–2032
Rising data localization and sovereign cloud requirements driver +0.5% Europe, Asia-Pacific 2026–2035
Expanding digital services adoption across emerging economies driver +0.6% Asia-Pacific, Latin America 2026–2035
High migration cost from legacy relational systems restraint −0.6% Global 2026–2032
Data governance and cross-border compliance complexity restraint −0.4% Europe, Asia-Pacific 2026–2035
Database administration skill shortages constraining adoption pace restraint −0.3% Global 2026–2032
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver of the Operational Database Management System Market?

Cloud migration of legacy transactional workloads is the primary driver of the market. The U.S. National Institute of Standards and Technology continue to publish cloud computing reference architectures that inform enterprise migration planning, reflecting sustained federal and commercial cloud adoption. We observed that this migration trajectory, reinforced by rising distributed SQL demand, continues to anchor demand for operational database platforms across developed and emerging markets alike.

How Is Real-Time Data Processing Driving Operational Database Management System Market Growth?

Expanding real-time application data serving requirements is accelerating growth in in-memory and low-latency database categories. The U.S. Federal Trade Commission continues to monitor data-driven personalization and fraud detection practices that rely on real-time transactional data platforms. Our assessment indicates that this regulatory and commercial pathway is compressing adoption timelines for real-time data processing modules across financial services and retail enterprises.

Growth Inhibitors

What Is Restraining Operational Database Management System Market Expansion?

High migration cost from legacy relational systems restrains market expansion, particularly among enterprises with deeply embedded mainframe and legacy database dependencies. National digital government modernization programs indicate that legacy system migration remains a persistent barrier to broader database platform adoption. We found that enterprises lacking dedicated migration expertise face particular exposure, as incomplete data model conversion increases downtime risk compared with phased, professionally managed migrations.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Traditional
Enterprise R
Mid-Market R
Embedded RDB
Distributed
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Traditional RDBMS $10.0 USD Billion $40.0 USD Billion 14.0%
Enterprise RDBMS $17.1 USD Billion $51.1 USD Billion 8.0%
Mid-Market RDBMS $24.2 USD Billion $62.2 USD Billion 14.0%
Embedded RDBMS $31.3 USD Billion $73.3 USD Billion 20.0%
Distributed Relational Databases $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Architecture.

Unlock Full Data

Which Architecture Dominates the Operational Database Management System Market?

Relational Databases led the market with USD 51.56 billion in 2025, supported by decades of enterprise application dependency on SQL-based transactional consistency. We observed that Graph Databases is the fastest-growing architecture, expanding at a 10.6% CAGR from 2026 to 2035, as relationship-intensive fraud detection, recommendation, and knowledge graph applications scale across BFSI and technology enterprises.

2025 (USD Billion)
2035 (USD Billion)
On-Premises
Private Clou
Public Cloud
Edge and Emb
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
On-Premises $10.0 USD Billion $40.0 USD Billion 25.0%
Private Cloud $17.1 USD Billion $51.1 USD Billion 11.0%
Public Cloud $24.2 USD Billion $62.2 USD Billion 25.0%
Edge and Embedded $31.3 USD Billion $73.3 USD Billion 11.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Deployment.

Unlock Full Data

Which Deployment Model Leads Operational Database Management System Market Demand?

Public Cloud remained the dominant deployment model across the market, reaching USD 40.10 billion in 2025 due to enterprise preference for managed, elastically scalable database services. Our findings suggest that Edge and Embedded is the fastest-growing deployment segment, registering a 12.2% CAGR from 2026 to 2035, as Internet of Things and industrial applications scale distributed data processing closer to data sources.

2025 (USD Billion)
2035 (USD Billion)
Transaction
Application
Operational
Real-Time Da
Relationship
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Transaction Processing $10.0 USD Billion $40.0 USD Billion 27.0%
Application Data Serving $17.1 USD Billion $51.1 USD Billion 9.0%
Operational Data Management $24.2 USD Billion $62.2 USD Billion 19.0%
Real-Time Data Processing $31.3 USD Billion $73.3 USD Billion 17.0%
Relationship Processing $38.4 USD Billion $84.4 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Operational Workload.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
License Reve
Subscription
Usage-Based
Support and
Other Direct
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
License Revenue $10.0 USD Billion $40.0 USD Billion 14.0%
Subscription Revenue $17.1 USD Billion $51.1 USD Billion 24.0%
Usage-Based Revenue $24.2 USD Billion $62.2 USD Billion 22.0%
Support and Maintenance Revenue $31.3 USD Billion $73.3 USD Billion 12.0%
Other Direct Database Revenue $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Revenue.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
BFSI
Healthcare a
Retail and E
Manufacturin
Telecommunic
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
BFSI $10.0 USD Billion $40.0 USD Billion 24.0%
Healthcare and Life Sciences $17.1 USD Billion $51.1 USD Billion 22.0%
Retail and E-Commerce $24.2 USD Billion $62.2 USD Billion 20.0%
Manufacturing $31.3 USD Billion $73.3 USD Billion 22.0%
Telecommunications $38.4 USD Billion $84.4 USD Billion 13.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User Industry.

Unlock Full Data

Which End User Industry Drives the Operational Database Management System Market?

BFSI remained the leading end user industry within the market, valued at USD 21.96 billion in 2025 on sustained transaction processing and regulatory reporting requirements. Based on research conducted by NMSC, we found that Information Technology and Software is the fastest-growing end user industry, registering a 7.3% CAGR from 2026 to 2035, as software companies embed operational databases within an expanding base of cloud-native applications.

Growth Opportunities

Three forward-looking whitespace opportunities stand out for suppliers positioning ahead of 2035 demand across the market.

How Can Distributed SQL Migration Services Unlock Value for Enterprise IT?

Distributed SQL migration services present a whitespace opportunity for suppliers serving enterprises transitioning legacy relational workloads to horizontally scalable platforms. Vendors that commercialize automated schema conversion and migration tooling stand to capture recurring modernization contracts as enterprises seek reduced downtime during platform transitions.

Where Does Edge Database Deployment Create New Demand in Industrial IoT?

Edge and embedded database deployment represents an underpenetrated opportunity for suppliers targeting industrial Internet of Things and manufacturing operators seeking local data processing capability. Providers that package lightweight, embedded database engines with time-series processing can secure long-term equipment monitoring contracts, benefiting from recurring licensing revenue tied to device fleet expansion.

How Can Multi-Model Consolidation Benefit Mid-Market Enterprise Buyers?

Multi-model database consolidation creates an opportunity for suppliers serving mid-market enterprises seeking to reduce the total number of database platforms in their technology stack. Early movers that bundle relational, document, and key-value capability within a single licensing agreement can differentiate ahead of broader platform consolidation investment through 2035.

SWOT Analysis

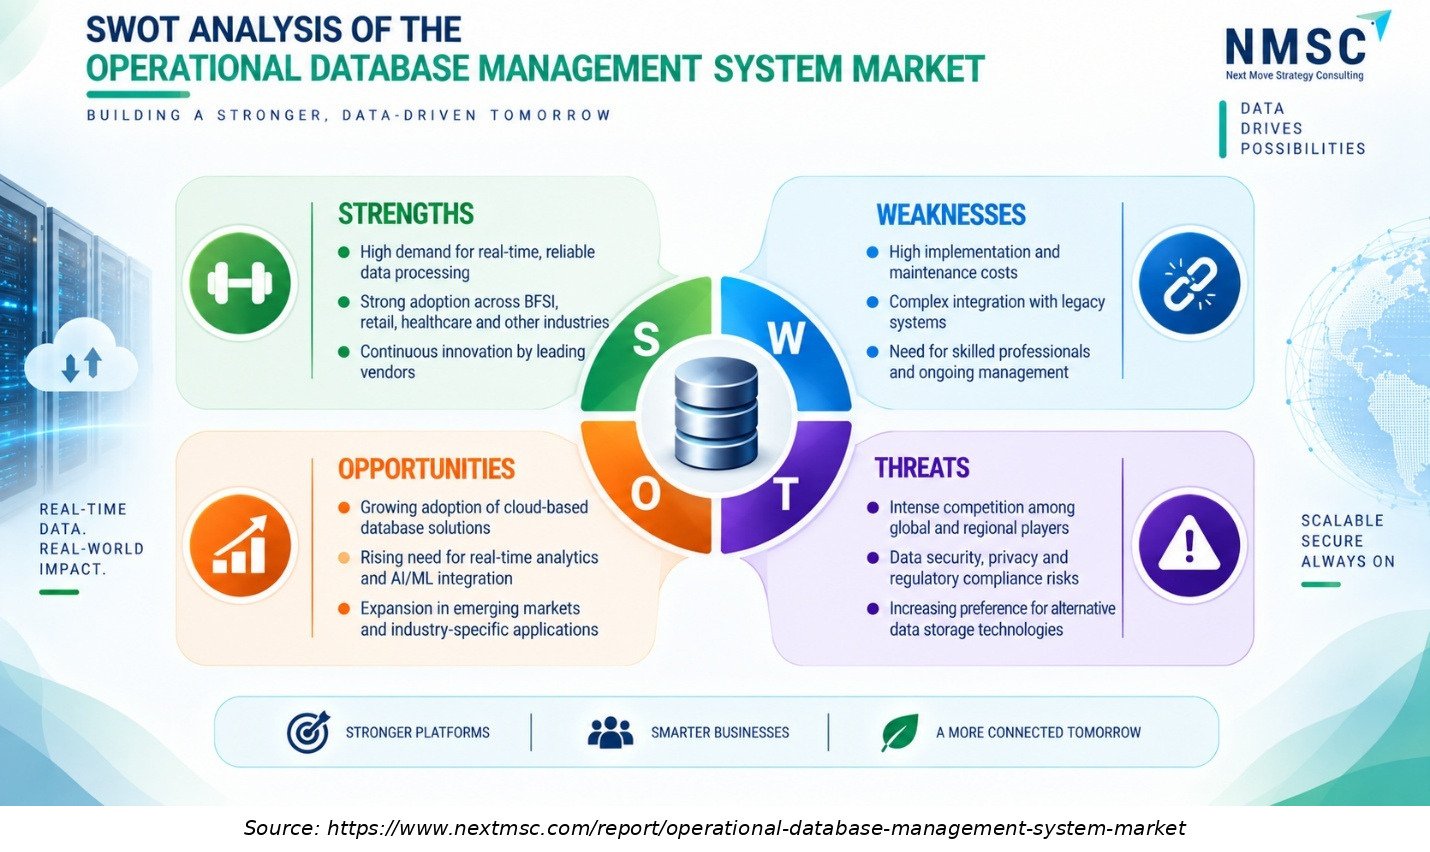
This SWOT view highlights structural strengths, strategic gaps, expansion headroom, and external risks shaping outcomes in the Operational Database Management System Market Global Industry Analysis and Forecast (2026-2035).

Strengths

real-time data processing and broad industry adoption

Weaknesses

integration complexity and management costs

Opportunities

cloud adoption and AI integration

Threats

competition, cybersecurity, privacy, and alternative database technologies

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

We observed that the operational database management system market features a moderately consolidated competitive landscape, with established enterprise software and hyperscale cloud majors competing alongside specialized NoSQL and distributed SQL vendors on architecture breadth, cloud integration, and enterprise support scale.

Dimension Description
Dimension Assessment
Market Structure Moderately consolidated; leading companies profiled in this report account for a substantial share of Industry revenue, while numerous specialized database vendors serve fragmented workload-specific demand.
Innovation Focus Distributed SQL scalability, multi-model consolidation, and cloud-native managed database services dominate current innovation pipelines across leading suppliers.
M&A Activity Selective consolidation through platform acquisition and cloud service integration, exemplified by continued hyperscale cloud provider investment in managed database service portfolios.

How Do Companies Compete in the Operational Database Management System Market?

Companies compete primarily on architecture breadth, cloud integration depth, and enterprise support scale across the Industry. Established vendors such as Oracle Corporation and Microsoft Corporation leverage decades of enterprise relational database engineering to serve mature global markets, while hyperscale cloud providers such as Amazon.com and Alphabet compete on managed service breadth and cross-portfolio cloud integration.

Which Competitive Archetypes Dominate the Operational Database Management System Market?

Two archetypes dominate the market: established enterprise database and hyperscale cloud majors with decades of platform engineering experience, and specialized NoSQL and distributed SQL vendors offering purpose-built architectures for specific operational workloads. Oracle Corporation and Amazon.com exemplify the enterprise and hyperscale archetype, while MongoDB and Cockroach Labs exemplify the specialized architecture archetype.

How Are Companies Differentiating Through Innovation in Operational Database Management Systems?

Innovation and differentiation strategy increasingly center on distributed SQL scalability and multi-model consolidation. MongoDB's expansion of document, search, and vector capabilities within a unified platform and SingleStore's real-time analytical and transactional convergence both demonstrate how vendors differentiate through architecture consolidation. Our analysis shows that suppliers unable to demonstrate credible cloud-native scalability risk exclusion from enterprise modernization procurement shortlists.

What M&A and Expansion Activity Is Shaping the Operational Database Management System Market?

Strategic acquisitions, cloud service integration, and geographic expansion continue to consolidate capabilities within the Industry. Progress Software's continued acquisition-driven expansion of its data connectivity and database portfolio illustrates how established vendors pursue rapid capability scaling through consolidated platform ownership across relational and NoSQL categories.

Key Market Players

Our assessment indicates that the following 20 companies are actively shaping architecture innovation, cloud platform integration, and geographic expansion within the global operational database management system market.

Oracle Corporation Microsoft Corporation Amazon.com, Inc. International Business Machines Corporation Alphabet Inc. SAP SE Alibaba Group Holding Limited Tencent Holdings Limited Huawei Technologies Co., Ltd. MongoDB, Inc. Couchbase, Inc. Redis, Inc. MariaDB plc Progress Software Corporation EnterpriseDB Corporation InterSystems Corporation Neo4j, Inc. SingleStore, Inc. Cockroach Labs, Inc. Aerospike, Inc.

Latest Developments

We observed that recent developments across the industry reflect continued investment in distributed SQL scaling and AI-native database capability.

Date Event
September, 2026 Neo4j announced GraphAware Financial Crime Intelligence, a graph-native solution for full-cycle detection, investigation, and prevention. It combines connected-data analysis with a knowledge layer to support trustworthy AI. The launch expands graph database use in regulated operational environments where relationship analysis, explainability, and near-real-time investigation are critical
September, 2026 Cockroach Labs introduced Cockroach Continuum, an agentic database cloud designed to run an enterprise database estate as one elastic system. It pools capacity across databases, automates operations, and prices usage by work performed. The initiative targets scalable, resilient operational databases for rapidly growing AI-driven application estates.

Investment Opportunities

What Capital Inflows Are Targeting the Operational Database Management System Market?

Capital inflows into the operational database management system market are increasingly directed toward distributed SQL and multi-model platform development. We observed that strategic investors continue to fund platform expansion, as seen in continued private investment supporting Cockroach Labs' distributed SQL platform development. Investors favor vendors demonstrating validated enterprise scalability credentials, viewing hyperscale cloud partnership as a proxy for long-term market access.

How Is Infrastructure Investment Supporting Operational Database Management System Deployment?

Infrastructure investment is expanding global cloud data center capacity to serve rising enterprise database workload demand. Our findings suggest that hyperscale cloud providers are scaling regional data center footprints to improve latency and data residency compliance for managed database services across North America, Europe, and Asia-Pacific.

What ESG Considerations Are Shaping Operational Database Management System Investment Decisions?

Environmental, social, and governance considerations are increasingly central to investment decisions across the Industry, with data center energy efficiency and data governance as key criteria. We found that investors increasingly favor vendors demonstrating measurable improvements in compute efficiency for database workloads, treating it as a governance indicator alongside data privacy compliance.

Key Benefits for Stakeholders

How Does This Report Benefit Enterprise and Industry Leaders?

Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and regional demand forecasts that support sourcing and vendor-selection decisions across the operational database management system Industry. Our analysis shows that detailed architecture, deployment, and end user industry breakdowns help procurement teams align specifications with workload requirements while identifying underserved revenue model and operational workload segments for portfolio expansion.

How Does This Report Benefit Investors and Financial Analysts?

Investors and financial analysts benefit from consistent, single-point market size and CAGR estimates that support valuation and capital-allocation decisions across the operational database management system supply chain. We observed that the report's regional and segment-level growth differentials help identify which vendors are best positioned to capture above-market growth in distributed SQL and Asia-Pacific categories through 2035.

How Does This Report Benefit Technology Vendors and Product Teams?

Technology vendors and product teams gain insight into emerging design requirements, including multi-model consolidation and distributed SQL scalability, that are reshaping the Industry. Our findings suggest that this analysis helps R&D teams prioritize development roadmaps around cloud-native architecture and real-time processing capability increasingly required by enterprise modernization procurement processes.

Key Market Segments Evaluated

By Architecture

  • Relational Databases 
    • Traditional RDBMS
      • Enterprise RDBMS
      • Mid-Market RDBMS
      • Embedded RDBMS
    • Distributed SQL Databases
      • Distributed Relational Databases
      • Cloud-Native Distributed SQL
  • Document Databases 
    • General-Purpose Document
    • JSON-Native Document
  • Key-Value Databases 
    • Persistent Key-Value
    • In-Memory Key-Value
  • Wide-Column Databases 
    • Distributed Wide-Column
    • Cloud-Native Wide-Column
  • Graph Databases 
    • Property Graph
    • RDF and Semantic Graph
  • Time-Series Databases 
    • General-Purpose
    • Industrial and IoT
  • Specialized Operational Databases 
    • Object-Oriented
    • Other Transaction-Capable Specialized
  • Multi-Model Databases 
    • Relational and Document
    • Relational and Key-Value
    • Relational and Graph
    • Document and Graph
    • General-Purpose Multi-Model

By Deployment

  • On-Premises
  • Private Cloud
  • Public Cloud
  • Edge and Embedded

By Operational Workload

  • Transaction Processing
  • Application Data Serving
  • Operational Data Management
  • Real-Time Data Processing
  • Relationship Processing
  • Time-Series Processing

By Revenue

  • License Revenue
  • Subscription Revenue
  • Usage-Based Revenue
  • Support and Maintenance Revenue
  • Other Direct Database Revenue

By End User Industry

  • BFSI
  • Healthcare and Life Sciences
  • Retail and E-Commerce
  • Manufacturing
  • Telecommunications
  • Information Technology and Software
  • Media and Entertainment
  • Government and Public Services
  • Transportation and Logistics
  • Energy and Utilities
  • Professional Services
  • Education and Research
  • Other Industries

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico.
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe.
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC.
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA.
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM.

Conclusion & Recommendations

The long-term outlook for the operational database management system market remains positive, supported by a USD 59.43 billion absolute dollar opportunity between 2026 and 2035 and sustained enterprise cloud migration momentum. NMSC's analysis indicates that vendors combining distributed SQL scalability with multi-model consolidation will be best positioned to capture the market's projected growth from USD 102.08 billion in 2026 to USD 161.51 billion by 2035.

What Strategic Positioning Should Suppliers Pursue in the Operational Database Management System Market?

Suppliers should prioritize multi-model and distributed SQL capability to secure long-term access to enterprise modernization procurement channels. Our assessment indicates that vendors investing early in cloud-native architecture and real-time processing capability, alongside expanded managed service offerings, will be best positioned to capture premium pricing within the operational database management system market as workload diversity intensifies.

How Attractive Is the Operational Database Management System Market for New Investment?

The operational database management system Industry presents an attractive investment case, supported by a USD 59.43 billion absolute dollar opportunity between 2026 and 2035 and above-average growth in Asia-Pacific and information technology end user categories. We found that investment attractiveness is highest for vendors combining validated cloud-native scalability with scaled global infrastructure, positioning them to serve both mature North American and emerging Asia-Pacific segments simultaneously.

What Market Shifts and Key Risks Should Stakeholders Monitor?

Stakeholders should monitor legacy migration cost, data sovereignty compliance burden, and competitive pressure from bundled hyperscale cloud database services as key risks to the operational database management system market. Our analysis shows that vendors unable to demonstrate seamless cloud interoperability risk losing market access to competitors with pre-integrated, cloud-native platforms, particularly within increasingly consolidated enterprise IT markets.

What Are the Key Growth Pathways for the Operational Database Management System Market?

Key growth pathways include expanding distributed SQL and multi-model portfolios, scaling real-time processing capability for financial services and retail enterprises, and deepening penetration into Asia-Pacific digital services markets. NMSC's analysis indicates that vendors pursuing these pathways while maintaining cost competitiveness in traditional relational offerings will be best positioned to capture the operational database management system market's projected growth through 2035.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Historical Market Revenue Analysis
  • Historical revenue analysis of operational DBMS across architecture, deployment model, and end user industry segments.
  • Identifies fastest-growing segments and supports investment and portfolio prioritization.
Company-Level Revenue and Offering Share Analysis
  • Vendor-level DBMS revenue and share benchmarking by architecture type and deployment model, based on company filings and investor disclosures.
  • Clarifies vendor positioning and highlights share gaps for competitive strategy and partnerships.
Market Opportunity Sizing (TAM / SAM / VAM)
  • Total, serviceable, and valuable market sizing across end user industries, deployment models, and operational workloads.
  • Prioritizes target segments and supports go-to-market and investment decisions.
Cloud Migration and Deployment Shift Assessment
  • Analysis of the shift from on-premises to cloud, hybrid, and managed database deployments across end user industries, using vendor cloud revenue disclosures and public cloud adoption data.
  • Guides cloud-versus-licensed offering mix, pricing models, and migration-focused sales strategy.
Workload-Based Architecture Fit Mapping
  • Mapping of relational, NoSQL, NewSQL, and in-memory architectures to transactional, real-time, and mixed operational workloads, with vendor offering coverage.
  • Reveals architecture-workload white spaces to steer product roadmap and positioning.
Industry Vertical Demand and Compliance Assessment
  • Demand analysis of operational DBMS by end user industry (such as BFSI, healthcare, retail, telecom, government), with data residency and regulatory requirements shaping deployment choices.
  • Identifies priority verticals and compliance-driven entry points for targeted customer acquisition.

FAQs

About the Author

Liza Phukan

Liza Phukan

Liza Phukan is Research Associate at Next Move Strategy Consulting, where she has covered emerging industries and market research across sectors for 3.5 years. Her work includes analyzing industry developments, validating market data, and developing structured business content from research findings. She uses secondary research and data-validation practices to turn complex market information into clear decision-useful market analysis for business audiences and support report development and B2B.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Nishant Awate

NISHANT AWATE

Business Development Global Sales

Zehnder Group Deutschland GmbH

Our experience working with Next Move Strategy Consulting was positive. The team was responsive, professional, and open to incorporating our specific requirements throughout the project. The India AHU market study was comprehensive and well structured, covering market value and volume forecasts, product and application segments, and key industry trends. The inclusion of both AHU and residential MVHR market insights made the study particularly relevant for our strategic market assessment. Overall, the report provides a solid foundation for evaluating market potential, identifying priority segments, and supporting business-development decisions in India.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖