Autonomous Security Operations Center Market Global Industry Analysis and Forecast (2026–2035)

Autonomous Security Operations Center Market revenue climbs from USD 1,600.00 Million in 2025 to USD 14,100.00 Million in 2035, a 23.9% CAGR over 2026–2035, as analyst shortages, costlier breaches, and AI-enabled attacks lift demand, with North America leading adoption.

Download Free Sample PDF
Base Year (2025)
$1,600.0 Million
Forecast (2035)
$14,100.0 Million
CAGR (2026-2035)
23.9%
Top Region
North America

What Is the Autonomous Security Operations Center Market Size?

The global Autonomous Security Operations Center Market is estimated at USD 1,600.00 Million in 2025 and USD 2,050.00 Million in 2026, and is projected to reach USD 14,100.00 Million by 2035, growing at a CAGR of 23.9% from 2026 to 2035. According to NMSC estimates, North America accounted for approximately 46% of 2025 revenue, while Autonomous SecOps Platforms represented approximately 44%

Based on research conducted by NMSC, we identified that the adoption of AI agents in security operations is moving rapidly from initial pilot projects to full-scale enterprise production.

Autonomous Security Operations Center Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast

Values in USD Million

2025 $1,600.0 Million
2025
2026 $2,050.0 Million
2026
2027 $2,540.0 Million
2027
2028 $3,147.0 Million
2028
2029 $3,899.1 Million
2029
2030 $4,831.0 Million
2030
2031 $5,985.6 Million
2031
2032 $7,416.2 Million
2032
2033 $9,188.7 Million
2033
2034 $11,384.8 Million
2034
2035 $14,100.0 Million
2035

Key Takeaways

By Offering: Autonomous SecOps Platforms led with USD 708.80 Million in 2025 and is projected at USD 4,709.40 Million in 2035; AI SOC Analyst Agents is the fastest growing at 30.1% CAGR from 2026 to 2035

By Deployment Model: Cloud SaaS led with USD 988.80 Million in 2025 and is projected at USD 11,026.20 Million in 2035; it is also the fastest growing at 26.3% CAGR from 2026 to 2035

By End User Industry: BFSI led with USD 438.40 Million in 2025 and is projected at USD 3,539.10 Million in 2035; Healthcare and Life Sciences is the fastest growing at 25.7% CAGR from 2026 to 2035

Dominant Region: North America, valued at USD 739.20 Million in 2025 with about 46% share

Fastest Growing Region: Asia-Pacific, at 27.8% CAGR from 2026 to 2035, reaching USD 3,539.10 Million in 2035

Dominant Country: U.S., valued at USD 620.93 Million in 2025

Fastest Growing Country: India, at 31.4% CAGR from 2026 to 2035, reaching USD 637.04 Million in 2035

The market adds USD 12,050.00 Million of absolute opportunity between 2026 and 2035, an attractive entry point for platform investors.

According to NMSC analysis, agent bundling inside existing security suites will cap standalone pricing while expanding total usage across enterprises.

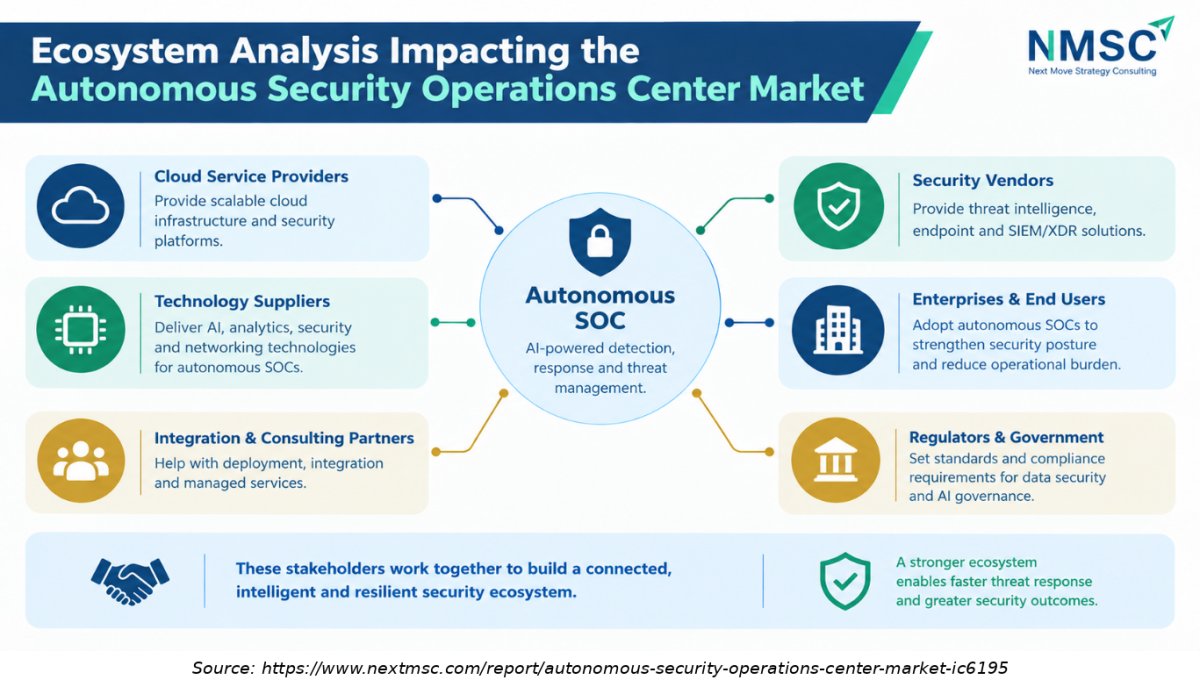
Ecosystem Analysis Impacting the Autonomous Security Operations Center Market

The Autonomous Security Operations Center ecosystem connects cloud service providers, security vendors, technology suppliers, integration partners, enterprises and regulators. These stakeholders work together to enable AI-driven threat detection, automated incident response and stronger cybersecurity across digital environments.

What Does the Autonomous Security Operations Center Market Encompass?

The Market covers software and services in which AI agents autonomously triage alerts, investigate incidents, enrich context, and execute approved response actions under human oversight. It spans AI native SIEM and XDR operations platforms, standalone AI SOC analyst agents, agentic SOAR, and managed services that run an agentic SOC for customers.

Revenue includes only the defined autonomy layer, comprising agentic modules, AI SOC platforms and agent-driven managed services. Conventional SIEM log licences, traditional SOAR products without AI agents, endpoint-protection licences and other security-operations spending outside this scope are excluded. The methodology should specify how vendor and service-provider revenue is treated when platforms are bundled or resold, to prevent double counting when a partner resells a platform. AI based security operations spending outside this layer is not included.

Market Drivers & Dynamics

Interactive Dataset
Persistent cybersecurity skills shortage driver +3.4% Global 2026–2029
Rising alert volume and breach cost driver +3.0% North America, Europe 2026–2028
AI-enabled attacks compressing response windows driver +2.6% Global 2026–2030
Agent bundling by platform vendors driver +2.2% North America, Europe 2026–2031
Regulatory incident reporting deadlines driver +1.5% U.S., Europe, Asia-Pacific 2026–2032
Trust and explainability gaps in autonomous action restraint −2.1% Global 2026–2028
Data quality and integration complexity restraint −1.6% Global 2026–2030
Model cost and pricing uncertainty restraint −1.1% Global 2026–2027
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver in the Autonomous SOC Industry?

The shortage of trained cybersecurity analysts is a major driver of the Autonomous Security Operations Center Market, as AI agents can automate routine alert triage and investigation. A 2025 workforce study covering more than 16,000 professionals found that 95% see at least one skills gap on their team, and 88% had suffered a significant incident linked to skills shortages. Agents that perform routine investigation let scarce staff focus on threat hunting and decisions that need judgment.

How Is Rising Breach Cost and Attack Speed Driving the Market Growth?

IBM's 2026 Cost of a Data Breach study reported that one in four malicious breaches involved AI and that these breaches cost approximately USD 6 Million on average. These findings highlight the potential value of faster detection and response, although they do not independently establish the market's projected growth rate.

Growth Inhibitors

What Is Restraining the Autonomous Security Operations Center Market?

Trust is the main restraint on the Autonomous Security Operations Center Market. Security teams hesitate to let an agent isolate host or disable accounts without review, and false positives that disrupt business operations erode confidence quickly. Integration debt across fragmented tooling and unpredictable model consumption costs also slow rollouts, which keeps many deployments in recommendation mode rather than fully autonomous response.

What Are the Growth Opportunities?

Can Independent Agent Vendors Win Multi-Platform Environments?

Large enterprises often run several SIEM and EDR tools after mergers and migrations. Vendor neutral agents that investigate across all of them offer an alternative to single suite consolidation. Specialists such as Torq, 7AI, and Prophet Security have raised venture capital to capture this mixed estate, which benefits the AI SOC Analyst Agents segment of the Autonomous Security Operations Center Market.

Does the Mid-Market Managed Service Channel Represent Untapped Volume?

Mid-sized organizations face the same attacks as large firms but lack a night shift. Agent driven managed detection and response lowers delivery cost per customer, so providers can price below traditional services. The managed segment is expected to reach USD 3,087.90 Million by 2035, with MSSPs and carriers as the main route to this volume.

Can Operational Technology and Healthcare Become Premium Verticals?

Industrial and clinical environments combine high downtime cost with scarce security talent, so buyers will pay for agents tuned to their protocols and safety rules. Linking SOC agents with cyber physical systems security telemetry can open specialized contracts, and Healthcare and Life Sciences already shows the fastest vertical growth at 25.7% CAGR.

Segmentation Analysis

2025 (USD Million)
2035 (USD Million)
Autonomous SecOps Platforms 2025: $708.8 Million | 2035: $863.1 Million
Autonomous S
AI SOC Analyst Agents 2025: $220.8 Million | 2035: $352.6 Million
AI SOC Analy
Agentic SOAR and Automation 2025: $289.6 Million | 2035: $360.8 Million
Agentic SOAR
Autonomous Managed SOC Services 2025: $380.8 Million | 2035: $473.6 Million
Autonomous M
Autonomous SecOps Platforms $708.8 Million $863.1 Million 4,709.40
AI SOC Analyst Agents $220.8 Million $352.6 Million 3,764.70
Agentic SOAR and Automation $289.6 Million $360.8 Million 2,538.00
Autonomous Managed SOC Services $380.8 Million $473.6 Million 3,087.90
2025 (USD Million)
2035 (USD Million)
Autonomous S
AI SOC Analy
Agentic SOAR
Autonomous M
Cloud SaaS
Segment Item 2025 (USD Million) 2035 (USD Million) CAGR
Autonomous SecOps Platforms $10.0 USD Million $40.0 USD Million 18.0%
AI SOC Analyst Agents $17.1 USD Million $51.1 USD Million 24.0%
Agentic SOAR and Automation $24.2 USD Million $62.2 USD Million 26.0%
Autonomous Managed SOC Services $31.3 USD Million $73.3 USD Million 8.0%
Cloud SaaS $38.4 USD Million $84.4 USD Million 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Deployment Model.

Unlock Full Data
2025 (USD Million)
2035 (USD Million)
Autonomous S
AI SOC Analy
Agentic SOAR
Autonomous M
Cloud SaaS
Segment Item 2025 (USD Million) 2035 (USD Million) CAGR
Autonomous SecOps Platforms $10.0 USD Million $40.0 USD Million 20.0%
AI SOC Analyst Agents $17.1 USD Million $51.1 USD Million 26.0%
Agentic SOAR and Automation $24.2 USD Million $62.2 USD Million 24.0%
Autonomous Managed SOC Services $31.3 USD Million $73.3 USD Million 26.0%
Cloud SaaS $38.4 USD Million $84.4 USD Million 9.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End User Industry.

Unlock Full Data

Growth Opportunities

Our assessment indicates that three openings offer the clearest path to incremental revenue through 2035.

Can Independent Agent Vendors Win Multi-Platform Environments?

Large enterprises often run several SIEM and EDR tools after mergers and migrations. Vendor neutral agents that investigate across all of them offer an alternative to single suite consolidation. Specialists such as Torq, 7AI, and Prophet Security have raised venture capital to capture this mixed estate, which benefits the AI SOC Analyst Agents segment of the Autonomous Security Operations Center Market.

Does the Mid-Market Managed Service Channel Represent Untapped Volume?

Mid-sized organizations face the same attacks as large firms but lack a night shift. Agent driven managed detection and response lowers delivery cost per customer, so providers can price below traditional services. The managed segment is expected to reach USD 3,087.90 Million by 2035, with MSSPs and carriers as the main route to this volume.

Can Operational Technology and Healthcare Become Premium Verticals?

Industrial and clinical environments combine high downtime cost with scarce security talent, so buyers will pay for agents tuned to their protocols and safety rules. Linking SOC agents with cyber physical systems security telemetry can open specialized contracts, and Healthcare and Life Sciences already shows the fastest vertical growth at 25.7% CAGR.

Regional Outlook

2025 (USD Million)
2035 (USD Million)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Million) 2035 (USD Million) CAGR (%)
North America $10.0 USD Million $40.0 USD Million 9.0%
Europe $17.1 USD Million $51.1 USD Million 27.0%
Asia-Pacific $24.2 USD Million $62.2 USD Million 25.0%
Middle East & Africa $31.3 USD Million $73.3 USD Million 23.0%
Latin America $38.4 USD Million $84.4 USD Million 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

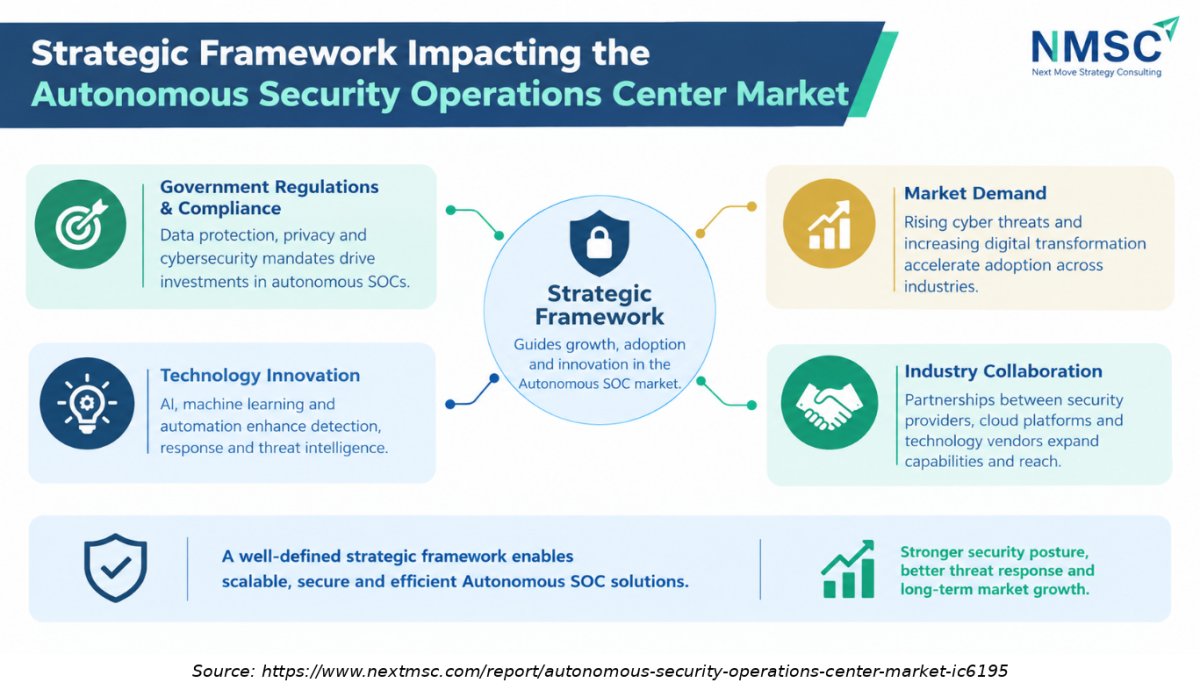
Strategic Framework Impacting the Autonomous Security Operations Center Market

Strategic Framework Impacting the Autonomous Security Operations Center Market
The strategic framework highlights the key factors shaping the Autonomous Security Operations Center Market, including government regulations, technology innovation, market demand, and industry collaboration. These factors support the development and adoption of scalable, secure, and efficient autonomous security solutions

Competitive Landscape

Our findings suggest that competition in this industry turns on telemetry ownership and provable investigation accuracy.

How Do Companies Compete in the Autonomous Security Operations Center Market?

Competition in the Autonomous Security Operations Center Market increasingly centers on access to security telemetry, investigation accuracy and the ability to integrate with existing tools. Platform vendors can bundle agents with their existing security offerings, while Microsoft's announced Security Copilot inclusion for eligible Microsoft 365 E5 customers may intensify pricing pressure on standalone providers. Independent vendors differentiate through interoperability, while managed providers compete on service outcomes and geographic coverage

Which Competitive Archetypes Dominate the Market?

Three competitive archetypes coexist. Platform incumbents such as Palo Alto Networks and CrowdStrike integrate agentic capabilities into their security platforms. Hyperscalers such as Microsoft and Google Cloud connect AI agents with their security clouds, while independent vendors such as Torq, 7AI and Prophet Security focus on integrations across security tools. Managed providers such as Arctic Wolf and IBM offer security operations services, with differentiation centered on investigation accuracy, interoperability and governance.

What Innovation and Differentiation Strategies Are Companies Pursuing?

Vendors are expanding agent capabilities beyond alert triage into threat hunting, detection engineering and remediation. Fortinet announced the availability of FortiSOC in June 2026, while Google Cloud introduced additional security-agent capabilities in 2026. Product roadmaps also emphasize frameworks that allow customers to build and govern agents, while usage-based pricing is emerging as an alternative to traditional seat-based licensing.

What M&A and Partnership Activity Is Shaping the Market?

Consolidation is reshaping the field. Palo Alto Networks announced its Console acquisition in 2026, Cisco integrated Splunk into its security portfolio, and venture rounds funded Torq at a valuation of USD 1,200.00 Million in January 2026 and 7AI with USD 130.00 Million in December 2025. We expect further acquisitions of agent startups by platform vendors, and regional partnerships to speed entry into Asia-Pacific and the Middle East.

Key Market Players

Based on research conducted by NMSC, the following 12 companies represent the validated leadership set in autonomous security operations platforms, agents, and services.

Palo Alto Networks, Inc. CrowdStrike Holdings, Inc. Microsoft Corporation Alphabet Inc. Cisco Systems, Inc. International Business Machines Corporation SentinelOne, Inc. Fortinet, Inc. Arctic Wolf Networks, Inc. Torq 7AI Prophet Security, Inc.

Latest Developments

We observed that 2026 announcements concentrated on agentic platforms, acquisitions, and large venture rounds.

Date Event
August 2026 Fortinet launched FortiSOC, a unified security operations platform with agentic AI covering detection, investigation, and response
August 2026 CrowdStrike reported ARR of USD 5,840.00 Million for its second quarter of fiscal 2027 and expanded agentic Falcon capabilities
March 2026 Arctic Wolf launched Aurora Agentic SOC, described as the largest commercial agentic SOC by event volume
December 2025 7AI raised USD 130.00 Million in a Series A round led by Index Ventures to expand its agentic security platform
September 2025 Cisco introduced Splunk Enterprise Security editions with a Triage Agent and other agentic capabilities

Expert Insights

George Kurtz

George Kurtz

CEO | CrowdStrike

"There is too much coming in, and there is not enough time to get through this at the speed at which the adversary is operating."

Analyst Interpretation

Kurtz made this statement in a discussion of CrowdStrike’s agentic SOC strategy, highlighting how increasing alert volumes and rapidly evolving cyberthreats are challenging traditional security operations

Investment Opportunities

Where Are Capital Inflows Concentrating in the Autonomous Security Operations Center Market?

Venture capital is concentrating in agent native startups, with Torq raising USD 140.00 Million in January 2026 and 7AI raising USD 130.00 Million in December 2025. Public vendors direct acquisition budgets toward agentic workflow and data assets. Capital favors companies that show measurable reduction in investigation time and can integrate with existing SIEM and EDR estates.

How Is Infrastructure Investment Shaping Market Capacity?

Agent workloads need security data lakes and inference capacity. Microsoft, Google Cloud, and Cisco invest in data platforms that store telemetry cheaply and let agents query it at scale. Providers that secure efficient inference and low-cost storage can offer agentic detection at prices that undercut traditional analyst heavy services, widening the addressable base.

What ESG Considerations Are Influencing Market Investment?

Responsible AI practice now influences procurement. Investors and buyers ask for explainable verdicts, audit logs, and data loss prevention style controls on model data use. Reducing analyst burnout is also cited as a workforce benefit, and vendors that evidence safe autonomy and privacy preserving model operation tend to win regulated accounts with longer contract terms.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders and Security Operations Teams?

Cybersecurity leaders get a view of where autonomy is production ready, which offerings and deployment models scale fastest, and how peers justify spending. The report quantifies segment growth and regional demand so teams can sequence investments and set realistic automation targets for triage, enrichment, and response across their security operations centers.

How Does This Report Benefit Investors and Financial Analysts?

Investors receive a reconciled size and forecast from USD 1,600.00 Million in 2025 to USD 14,100.00 Million in 2035, with segment growth rates and competitive archetypes. Evidence on funding rounds, acquisitions, and vendor disclosures helps separate durable platform positions from point products that larger vendors may absorb as the category consolidates over the coming years.

How Does This Report Benefit Technology Vendors and Service Providers?

Vendors can benchmark positioning against platform incumbents, Hyperscalers, and independent specialists, and identify gaps in verticals and regions. Service providers can seize the managed segment and judge how agents change delivery economics, staffing models, and pricing relative to traditional managed detection and response offerings, while planning regional expansion with channel partners.

Key Market Segments Evaluated

By Offering

  • Autonomous SecOps Platforms
  • AI SOC Analyst Agents
  • Agentic SOAR and Automation
  • Autonomous Managed SOC Services

By Deployment Model

  • Cloud SaaS
  • Hybrid
  • On-Premises

By End User Industry

  • BFSI
  • IT and Telecom
  • Government and Defense
  • Healthcare and Life Sciences
  • Manufacturing and Energy
  • Retail and Ecommerce
  • Other Industries

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico.
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe.
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC.
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA.
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM.

Conclusion & Recommendations

The Autonomous Security Operations Center Market is set to expand from USD 2,050.00 Million in 2026 to USD 14,100.00 Million by 2035 as agents move from assisting analysts to running routine investigation and response under supervision. Cloud SaaS delivery and AI SOC Analyst Agents will gain share, while platforms remain the largest offering through the forecast period.
What Strategic Positioning Recommendations Does NMSC Offer?

Platform vendors should publish verifiable accuracy metrics and open their agents to third party tools. Specialists should anchor on multi-platform investigation and pursue marketplace and MSSP channels. Service providers should productize agent assisted MDR for mid-sized buyers, and every vendor should treat approval workflows and audit trails as core features.

How Strong Is the Investment Attractiveness of the Market?

Investment attractiveness is high given a 23.9% CAGR, strong customer pain, and active venture and strategic funding. Risks include price compression as vendors bundle agents, and the trust barrier to autonomous response. Asia-Pacific and Healthcare and Life Sciences offer the fastest growth, while North America remains the largest revenue pool.

What Are the Market Shifts and Key Risks in the Autonomous Security Operations Center Market?

Key shifts include bundling of agents into existing suites, rising demand for agent governance, migration from on-premises tooling to cloud platforms, and underwriting scrutiny of response speed in cyber liability insurance pricing. Key risks are model errors that trigger harmful automated actions, adversaries targeting the agents themselves, and consolidation that leaves customers with fewer independent choices.

What Are the Primary Growth Pathways Through 2035?

Growth will come from converting pilots into production deployments, expanding agents from triage into threat hunting and remediation, and reaching mid-sized firms through managed channels. The offering that scales fastest is AI SOC Analyst Agents at 30.1% CAGR, and vendors that link it to attack surface management data will broaden addressable use cases.

FAQs

Sources & References

1.

Palo Alto Networks, Inc. fiscal fourth quarter 2026 results

paloaltonetworks.com
2.

CrowdStrike Holdings, Inc. second quarter fiscal 2027 results

ir.crowdstrike.com
3.

SentinelOne, Inc. second quarter fiscal 2027 results

s28.q4cdn.com
4.

Google Cloud agentic SOC

cloud.google.com
5.

Cisco Systems, Inc. newsroom: agentic AI for the SOC

newsroom.cisco.com
6.

IBM newsroom: autonomous security operations

newsroom.ibm.com
7.

IBM newsroom: Cost of a Data Breach Report 2026

newsroom.ibm.com
8.

ISC2: 2025 Cybersecurity Workforce Study

isc2.org
9.

FBI Internet Crime Complaint Center

ic3.gov
10.

Fortinet, Inc. newsroom: FortiSOC

fortinet.gcs-web.com
11.

Arctic Wolf Networks, Inc. press release: Aurora Agentic SOC

arcticwolf.com
12.

7AI press release: Series A

businesswire.com
13.

Microsoft Corporation: Security Copilot blog

microsoft.com
14.

Torq: company website

torq.io

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Amos Chang

AMOS CHANG

Strategy Consultant

Kardex Group

I have bought the intralogistics market reports from NMSC two times so far. Joseph and his team are always very helpful and flexible in responding to any customization requirements on the report. Their expertise in market reports really helps us steer the day-to-day business. I will definitely recommend and come back myself whenever there is a need.

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖