Denmark Industrial Robotics Market Size, Share, Trends and Growth Analysis, By Robot Type (Articulated Robots, SCARA Robots, Cartesian and Gantry Robots, Delta Robots, Collaborative Robots, Autonomous Mobile Robots (AMRs), Automated Guided Vehicles (AGVs), and Other Robots), By Offering (Hardware, Software, and Services), By Application (Handling, Welding and Soldering), By Mounting Type, By Mobility, By Payload Capacity, By End User – Opportunity Analysis and Industry Forecast, 2025–2035
Industry: Construction & Manufacturing | Latest Edition: September 1, 2026 | No of Pages: 268 | No. of Tables: 144 | No. of Figures: 130 | Format: PDF | Report Code: CM3717
What Is the Denmark Industrial Robotics Market Size?
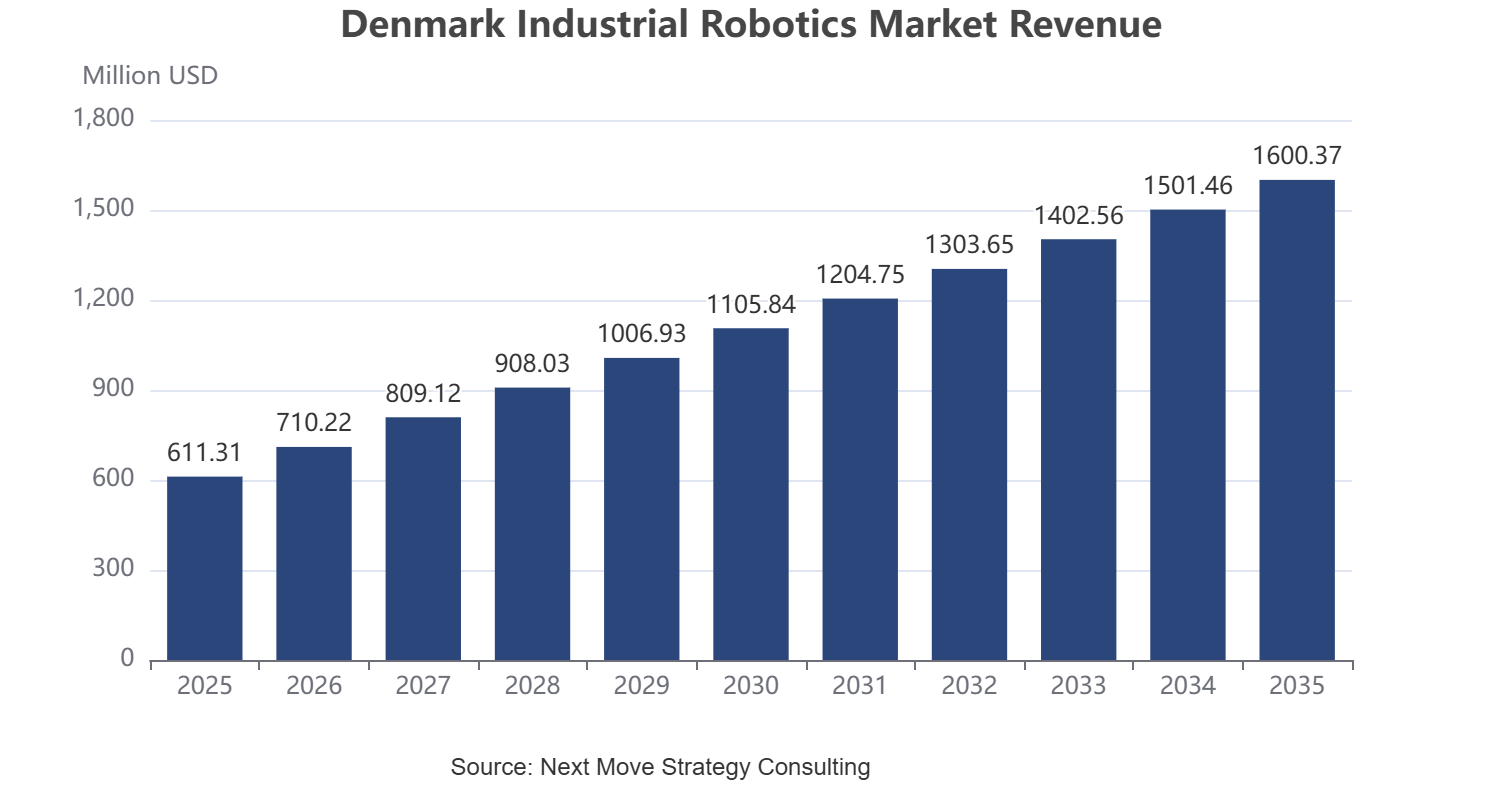
The Denmark industrial robotics Industry size was valued at USD 611.31 million in 2025 and is estimated at USD 674.66 million in 2026, forecast to reach USD 1,600.37 million by 2035, expanding at a 10.07% CAGR between 2026 and 2035. Collaborative robots dominate the market by robot type, reflecting Denmark's globally recognized cobot manufacturing base.
In unit terms, deployed robot volume in the Denmark market is estimated at 9 thousand units in 2025 and 10 thousand units in 2026, rising to 28 thousand units by 2035 at a 11.57% CAGR between 2026 and 2035. The steady increase in deployment reflects continued automation across Denmark’s manufacturing and industrial sectors, supported by growing adoption of collaborative robots and other cost-efficient robotic solutions.
We observed that market growth is supported by Denmark's concentrated Odense robotics cluster, rising adoption of autonomous mobile robots, and increasing automation investment across food, pharmaceutical, and logistics sectors through 2035.
|
Key Takeaways |
|
Our assessment indicates that the following segment-level dynamics define the competitive and technological trajectory of the Denmark Industrial Robotics Market through 2035. |
|
By Robot Type: Collaborative Robots is the dominant segment, while Autonomous Mobile Robots (AMRs) is the fastest-growing segment. |
|
By Offering: Hardware is the dominant segment, while Software is the fastest-growing segment. |
|
By Application: Handling is the dominant segment, while Inspection and Quality Control is the fastest-growing segment. |
|
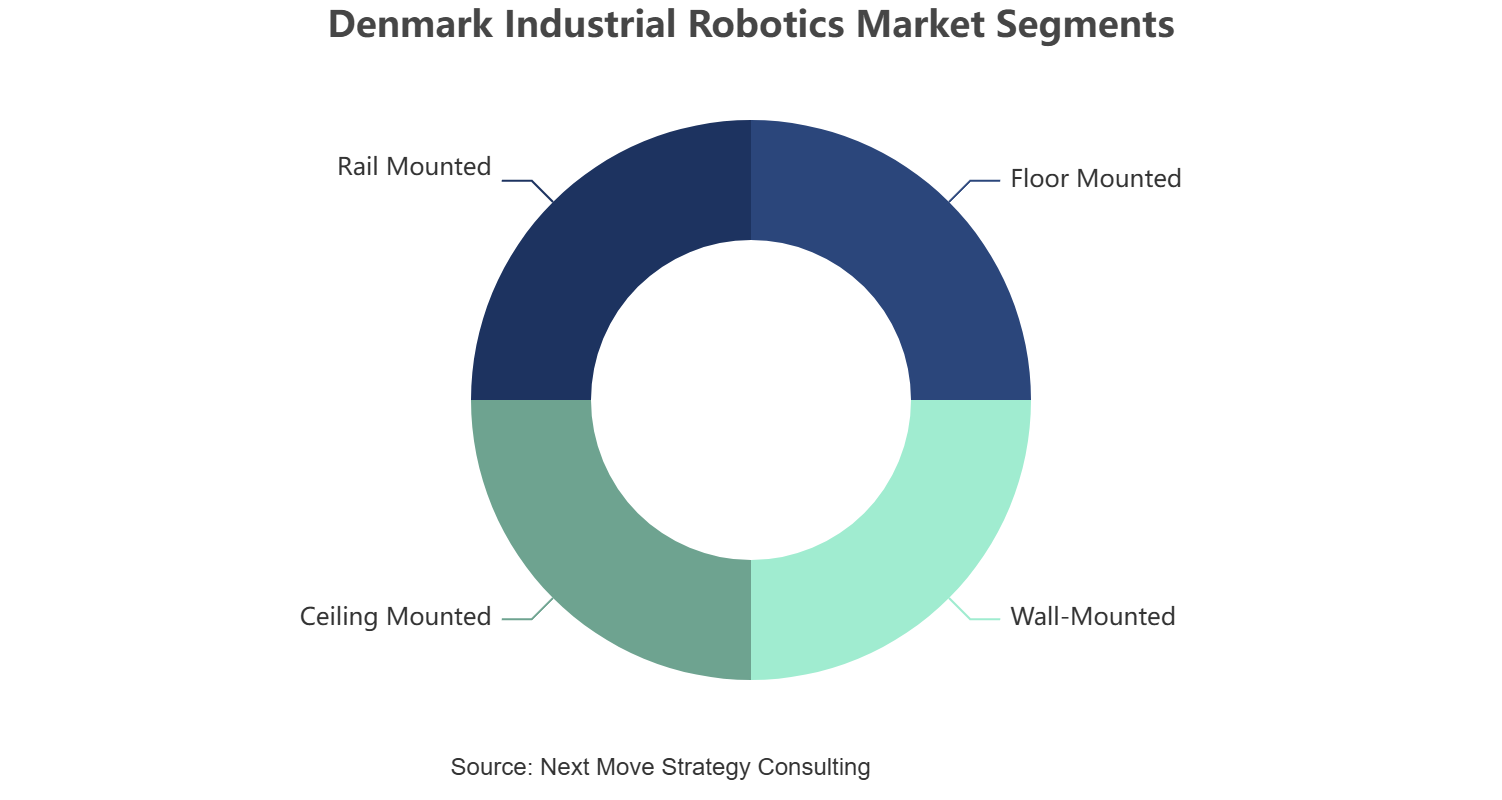
By Mounting Type: Floor Mounted is the dominant segment, while Rail Mounted is the fastest-growing segment. |
|
By Mobility: Stationary Robots is the dominant segment, while Mobile Robots is the fastest-growing segment. |
|
By Payload Capacity: Low Payload Up to 20 kg is the dominant segment, while Medium Payload 20 kg to 100 kg is the fastest-growing segment. |
|
By End User: Food and Beverages Industry is the dominant segment, while Pharmaceuticals and Medical Devices Industry is the fastest-growing segment. |
Market Opportunity: The Denmark Industrial Robotics Sector is expected to create an absolute dollar opportunity of USD 925.71 million between 2026 and 2035, presenting significant investment potential across collaborative robotics, autonomous mobile robots, and advanced gripping technology segments.
According to NMSC's analysis, Denmark industrial robotics industry, concentrated Odense robotics cluster is accelerating product development cycles for cobots and mobile robots, positioning domestic manufacturers to capture sustained global demand through 2035.
Strategic Framework of the Denmark Industrial Robotics Market:
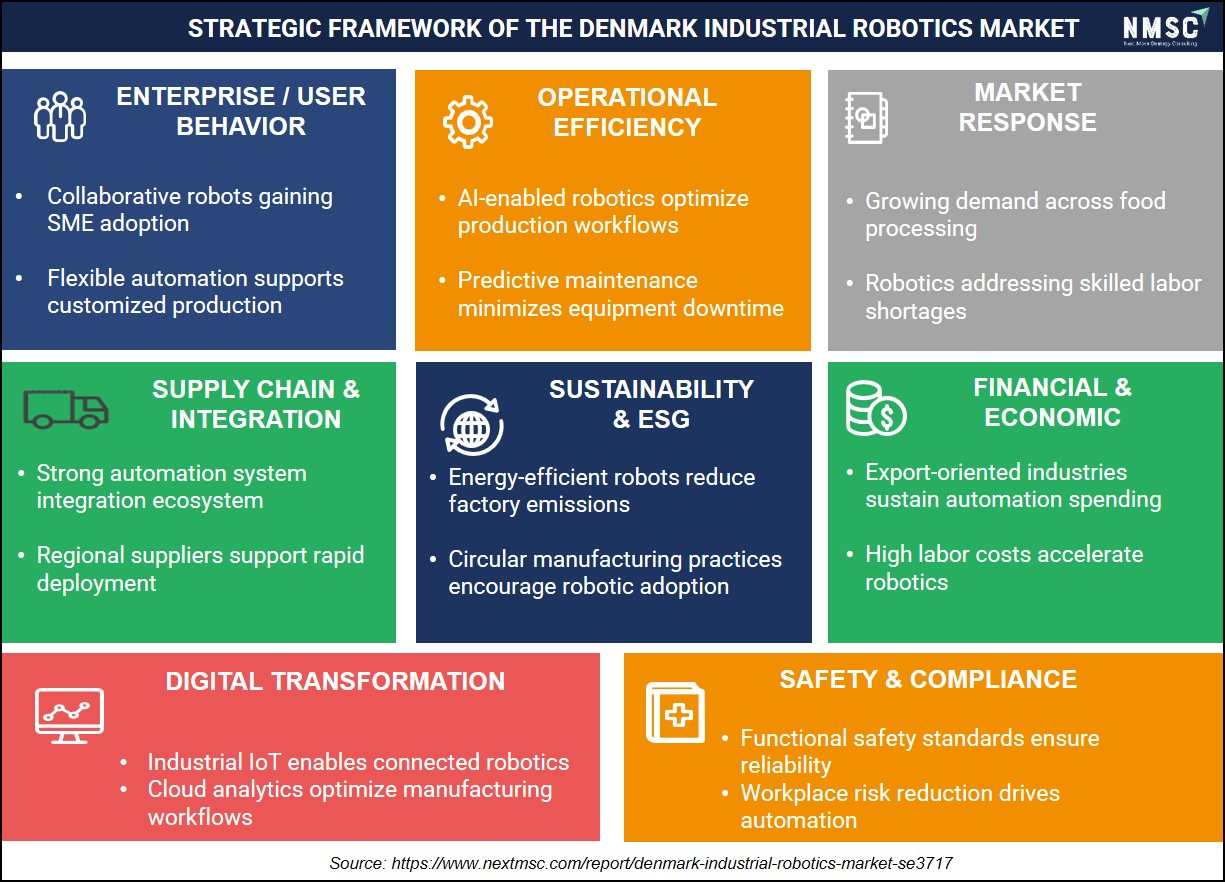
Based on our market evaluation, we noticed that Denmark’s industrial robotics Sector is driven by collaborative robot adoption, AI-enabled production optimization, and sustainable manufacturing practices. Moreover, Industrial IoT, predictive maintenance, and cloud analytics enhance operational efficiency, while regional supply chains support faster deployment. As a result, strict safety standards, export-oriented industries, and rising demand across food processing strengthen long-term automation growth and reinforce Denmark’s competitive industrial robotics ecosystem.
What does the Denmark Industrial Robotics Market Encompass?
The Denmark Industrial Robotics Market encompasses hardware, software, and services deployed to automate manufacturing, food processing, and logistics operations across Danish industry. Our assessment indicates that the market spans articulated, SCARA, cartesian, delta, collaborative, and mobile robot platforms integrated with controllers, end effectors, vision systems, and fleet management software. These solutions are deployed by food and beverage, pharmaceutical, machinery, and logistics companies through system integrators, original equipment manufacturers, and direct robot suppliers operating across Denmark's Odense-centered robotics cluster.
Denmark's robotics industry benefits from a concentrated innovation ecosystem centered on Odense, home to globally recognized cobot and mobile robot manufacturers. We observed that occupational safety requirements enforced by the Danish Working Environment Authority and machinery directives aligned with European Union regulations shape robot design, guarding, and collaborative operation standards. NMSC's analysis indicates that rising integration of artificial intelligence, machine vision, and cloud-connected fleet management is transforming robot programming, predictive maintenance, and production flexibility across Danish manufacturing and logistics facilities.
|
Parameter |
Details |
|
Market Size in 2025 |
USD 611.31 Million |
|
Market Size in 2026 |
USD 674.66 Million |
|
Revenue Forecast in 2035 |
USD 1,600.37 Million |
|
Growth Rate |
CAGR of 10.07% from 2026 to 2035 |
|
Market Volume in 2025 |
9 Thousand Units |
|
Market Volume in 2026 |
10 Thousand Units |
|
Volume Forecast in 2035 |
28 Thousand Units |
|
Volume Growth Rate |
CAGR of 11.57% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Revenue (USD Million) |
|
Companies Profiled |
15 |
|
Market Share |
Available for Top 10 Companies |
Key Emerging Trends
Based on research conducted by NMSC, we found that four structural trends are reshaping robot adoption, technology integration, and competitive dynamics across the Denmark Industrial Robotics industry.
How Are Danish Cobot Manufacturers Expanding Global Leadership?
Denmark's collaborative robot manufacturers continue to expand global Denmark industrial robotics market presence through new product launches and extended-reach platforms. We observed that companies such as Universal Robots A/S are broadening payload and reach capabilities to address welding, palletizing, and assembly applications beyond traditional light-duty tasks. This expansion strengthens Denmark's position as a global cobot innovation hub while supporting adoption among small and mid-sized manufacturers seeking flexible, easy-to-program automation across food, pharmaceutical, and metalworking industries.
Why Is Autonomous Mobile Robot Adoption Accelerating in Danish Logistics?
Autonomous mobile robots are increasingly deployed across Danish warehouses and distribution centers to automate material transport and reduce reliance on manual forklifts. Our findings suggest that logistics operators are prioritizing fleet management software capable of coordinating multiple mobile units across shared warehouse floors. Odense-based robotics manufacturers continue to expand mobile robot product lines, reflecting sustained demand for flexible, reconfigurable intralogistics automation across Danish distribution and fulfillment operations.
How Is End-of-Arm Tooling Innovation Enhancing Cobot Versatility?
Advanced grippers and end-of-arm tooling are expanding the range of tasks collaborative robots can perform across Danish manufacturing lines. We observed that companies such as OnRobot A/S are introducing higher-payload vacuum and electric grippers that enable palletizing, machine tending, and handling of irregular or fragile items. This innovation is lowering integration complexity for manufacturers deploying cobots across food processing, pharmaceuticals, and general assembly applications throughout Denmark.
What Role Does Artificial Intelligence Play in Danish Robotics Innovation?
Artificial intelligence is increasingly embedded in robot perception, deployment automation, and predictive maintenance across Danish robotics platforms. NMSC's analysis indicates that manufacturers are integrating AI-enabled vision, automatic deployment software, and cloud-connected diagnostics to shorten commissioning time and improve uptime. Danish robotics companies are collaborating with global technology partners to accelerate physical AI capabilities, positioning Denmark's robotics cluster at the forefront of intelligent automation adoption.
Growth Drivers and Restraints
Growth Catalyst and Risk Assessment Matrix
|
Factors |
Type |
(+/−) % Impact on CAGR |
Geographic Relevance |
Impact Timeline |
|
Rising labor costs and persistent workforce shortages driving automation demand across Danish manufacturing |
Driver |
+3.05% |
Denmark (nationwide; strongest around Odense and Jutland) |
Medium to Long term (2–6 years) |
|
Concentrated Odense robotics cluster accelerating cobot and AMR innovation and adoption |
Driver |
+2.64% |
Denmark (strongest in Odense and the Funen region) |
Long term (3–8 years) |
|
Expanding pharmaceutical and life sciences manufacturing increasing demand for cleanroom-compatible robots |
Driver |
+2.02% |
Denmark (strongest in Greater Copenhagen and Zealand) |
Medium term (2–5 years) |
|
Growing food and beverage processing automation supporting hygienic handling robot demand |
Driver |
+1.58% |
Denmark (nationwide; strongest in Jutland food processing hubs) |
Medium term (2–5 years) |
|
Rising e-commerce and warehouse automation driving autonomous mobile robot deployment |
Driver |
+1.21% |
Denmark (strongest in logistics hubs near Copenhagen and Aarhus) |
Short to Medium term (1–4 years) |
|
High integration costs limiting robotics adoption among small manufacturers |
Restraint |
−1.62% |
Denmark (nationwide; strongest among SMEs) |
Short to Medium term (1–4 years) |
|
Shortage of skilled robotics engineers and integration technicians |
Restraint |
−1.31% |
Denmark (nationwide) |
Medium term (2–5 years) |
What Is the Primary Growth Driver of the Denmark Industrial Robotics Market?
Rising labor costs and persistent workforce shortages in manufacturing are the primary growth driver of the Denmark Industrial Robotics Market. Industry-derived estimates, given the absence of a single publicly verifiable dataset, indicate that unfilled production and logistics roles across Danish industry continue to encourage automation adoption. We observed that food processing, pharmaceutical, and machinery companies are prioritizing collaborative and mobile robot deployments to maintain output while addressing recruitment challenges across Danish industrial regions.
How Is the Odense Robotics Cluster Driving Market Growth?
Denmark's concentrated robotics innovation ecosystem centered on Odense is accelerating cobot and autonomous mobile robots adoption across the Denmark Industrial Robotics Market. The cluster brings together robot manufacturers, component suppliers, and research institutions, an industry-derived estimate given the absence of a single publicly verifiable dataset on cluster output, supporting faster product development cycles and talent availability. We observed that this ecosystem is reinforcing Denmark's position as a global cobot innovation hub while strengthening local supply chains for grippers, sensors, and control software.
What Is Restraining Denmark Industrial Robotics Market Expansion?
High integration costs and a shortage of qualified robotics engineers continue to restrain market expansion, particularly among small and mid-sized Danish manufacturers. We found that limited in-house automation expertise and lengthy commissioning timelines increase total cost of ownership for smaller enterprises. Our analysis shows that these constraints slow automation adoption outside large food processing, pharmaceutical, and machinery manufacturers, limiting near-term robot density growth across smaller production facilities in Denmark.
Segmentation Analysis
By Robot Type Insights
How Is the Denmark Industrial Robotics Market Segmented by Robot Type?
Based on robot type, the Denmark Industrial Robotics Market is segmented into articulated robots, SCARA robots, cartesian and gantry robots, delta robots, collaborative robots, autonomous mobile robots, automated guided vehicles, and other robots. Each robot type addresses distinct application requirements across Danish manufacturing and logistics environments. Collaborative robots provide flexible, easy-to-program automation suited to food handling, packaging, and assembly, while articulated robots support heavier welding and material handling tasks. Autonomous mobile robots and automated guided vehicles extend automation beyond fixed workstations into warehouse and intralogistics operations.
Collaborative robots dominate the Denmark Industrial Robotics Market, reflecting the country's globally recognized cobot manufacturing base and strong domestic adoption among food, pharmaceutical, and metalworking manufacturers. We observed that autonomous mobile robots represent the fastest-growing robot type, driven by rising warehouse automation demand and Denmark's concentrated expertise in mobile robotics development. This shift reflects broader industry trends toward flexible, software-enabled automation that lowers barriers to adoption across Danish industrial facilities.
By End User Insights
How Is the Denmark Industrial Robotics Market Segmented by End User?
Based on end user, the Denmark Industrial Robotics Market is segmented into automotive, electrical and electronics, metals and machinery, food and beverages, pharmaceuticals and medical devices, plastics rubber and chemicals, logistics and warehousing, and other industries. Each end-use industry applies robotics differently depending on production complexity and regulatory requirements. Food and beverage manufacturers rely heavily on hygienic handling and packaging robots, while pharmaceutical companies prioritize cleanroom-compatible and precision-controlled automation. Machinery and logistics operators increasingly adopt collaborative and mobile robots for flexible material handling.
The food and beverages industry remains the dominant end user within the Denmark Industrial Robotics Market, reflecting the sector's strong reliance on hygienic handling, packaging, and palletizing automation across Danish food processing facilities. Our analysis indicates that the pharmaceuticals and medical devices industry is the fastest-growing end user, supported by expanding life sciences manufacturing investment across Denmark. This growth reflects increasing demand for cleanroom-compatible, precision handling, and quality control robots capable of supporting sensitive pharmaceutical production processes.
Growth Opportunities
Our analysis shows that three forward-looking opportunities stand out for stakeholders operating in the Denmark Industrial Robotics Market over the 2026–2035 forecast period.
How Can Cobot-as-a-Service Models Unlock Small Manufacturer Adoption?
Flexible leasing and subscription-based deployment models present a significant opportunity to expand collaborative robot adoption among small and mid-sized Danish manufacturers constrained by upfront capital costs. Providers offering bundled hardware, software, and integration services can lower adoption barriers and accelerate deployment across food processing and metal fabrication segments. Companies developing these models are positioned to capture demand from manufacturers previously unable to justify traditional capital expenditure on automation.
Where Do Autonomous Mobile Robots Create New Warehouse Automation Demand?
Rising e-commerce fulfillment and warehouse automation needs create substantial opportunities for autonomous mobile robot providers across Danish logistics and warehousing operations. Companies investing in fleet management software and multi-robot coordination can capture demand from third-party logistics providers and retailers expanding distribution capacity. This opportunity is reinforced by Denmark's established mobile robotics expertise and growing adoption of flexible material transport systems across Danish distribution centers.
How Can Advanced Gripping and Vision Technology Benefit Pharmaceutical and Food Manufacturers?
Growing demand for hygienic handling, cleanroom compatibility, and regulatory-compliant quality control creates opportunities for gripper and vision system providers serving Danish food and pharmaceutical manufacturers. Companies integrating advanced end-of-arm tooling and AI-enabled vision with robotic cells can help manufacturers meet strict quality standards while reducing manual handling labor. This opportunity particularly benefits suppliers offering validated, easy-to-deploy tooling suited to regulated production environments.
Competitive Landscape
We observed that the Denmark Industrial Robotics Market features a highly competitive landscape, with globally recognized Danish cobot and mobile robot manufacturers competing alongside multinational automation leaders and system integrators.
Key Takeaways
|
Dimension |
Description |
|
Market Structure |
Highly competitive with the presence of globally recognized Danish collaborative and mobile robot manufacturers alongside multinational automation leaders. Domestic cobot specialists account for a significant share of the Denmark Industrial Robotics Market, while global suppliers continue to expand local distribution and integration partnerships. |
|
Innovation Focus |
Collaborative robotics, advanced end-of-arm tooling, autonomous mobile robot fleet management, and AI-enabled deployment software dominate current product development strategies across leading Danish and multinational robot manufacturers. |
|
M&A Activity |
Ownership transitions, strategic investments, and distribution partnerships continue to shape the competitive landscape as companies strengthen their presence in high-growth segments such as collaborative robotics, service robots, and mobile automation. |
How Do Companies Compete in the Denmark Industrial Robotics Market?
Companies compete primarily through cobot ease of use, software ecosystem breadth, gripper and tooling compatibility, and service network reach. Leading manufacturers such as Universal Robots A/S and OnRobot A/S leverage extensive partner ecosystems, established distribution networks, and strong brand recognition to maintain market leadership. Meanwhile, multinational suppliers including ABB A/S, KUKA Nordic AB Danish Branch, and FANUC Nordic AB Danish Branch differentiate themselves through broader articulated robot portfolios, heavy-payload capabilities, and established automotive and machinery integration expertise.
Which Competitive Archetypes Dominate the Denmark Industrial Robotics Market?
Two primary competitive archetypes characterize the market. The first comprises domestic collaborative and mobile robot specialists offering flexible, easy-to-program automation platforms supported by extensive partner ecosystems. Companies such as Universal Robots A/S, OnRobot A/S, and Capra Robotics ApS represent this category. The second includes multinational automation suppliers such as ABB A/S, OMRON Electronics A/S, KUKA Nordic AB Danish Branch, and FANUC Nordic AB Danish Branch, which focus on articulated robots, heavy-payload applications, and established industrial integration capabilities.
How Are Companies Differentiating Through Innovation in Denmark Industrial Robotics?
Innovation strategies increasingly focus on cobot payload expansion, advanced gripping technology, automatic deployment software, and autonomous mobile robot fleet coordination. Companies are investing in easier programming interfaces, modular end-of-arm tooling, and cloud-connected diagnostics to reduce commissioning time and improve uptime. Our analysis indicates that manufacturers capable of combining hardware reliability with software-driven flexibility are strengthening their competitive positioning across the Denmark Industrial Robotics Market's food, pharmaceutical, and logistics segments.
What M&A and Expansion Activity Is Shaping the Denmark Industrial Robotics Market?
Ownership transitions, strategic investments, and distribution partnerships continue to shape competition across the market. Leading companies are strengthening their positions through new majority ownership structures, expanded partner ecosystems, and enhanced local system integration capabilities across Denmark. These initiatives enable manufacturers to broaden their automation offerings, enter high-growth segments such as mobile robotics and service robots, and respond more effectively to evolving customer requirements across Danish industry.
Key Market Players
Our assessment indicates that the following 15 companies are actively shaping product innovation, service expansion, and competitive dynamics within the Denmark Industrial Robotics Market.
-
Zebra Technologies Denmark ApS
-
Dematic Denmark ApS
-
Blue Ocean Robotics ApS
-
DENSO Robotics Europe S.A.
-
Kawasaki Robotics GmbH Danish Branch
-
Yaskawa Nordic AB Danish Branch
-
OMRON Electronics A/S
-
KUKA Nordic AB Danish Branch
-
FANUC Nordic AB Danish Branch
-
Enabled Robotics ApS
-
OnRobot A/S
-
Robotize ApS
-
Capra Robotics ApS
PORTER’S Five Forces Analysis of the Denmark Industrial Robotics Market:
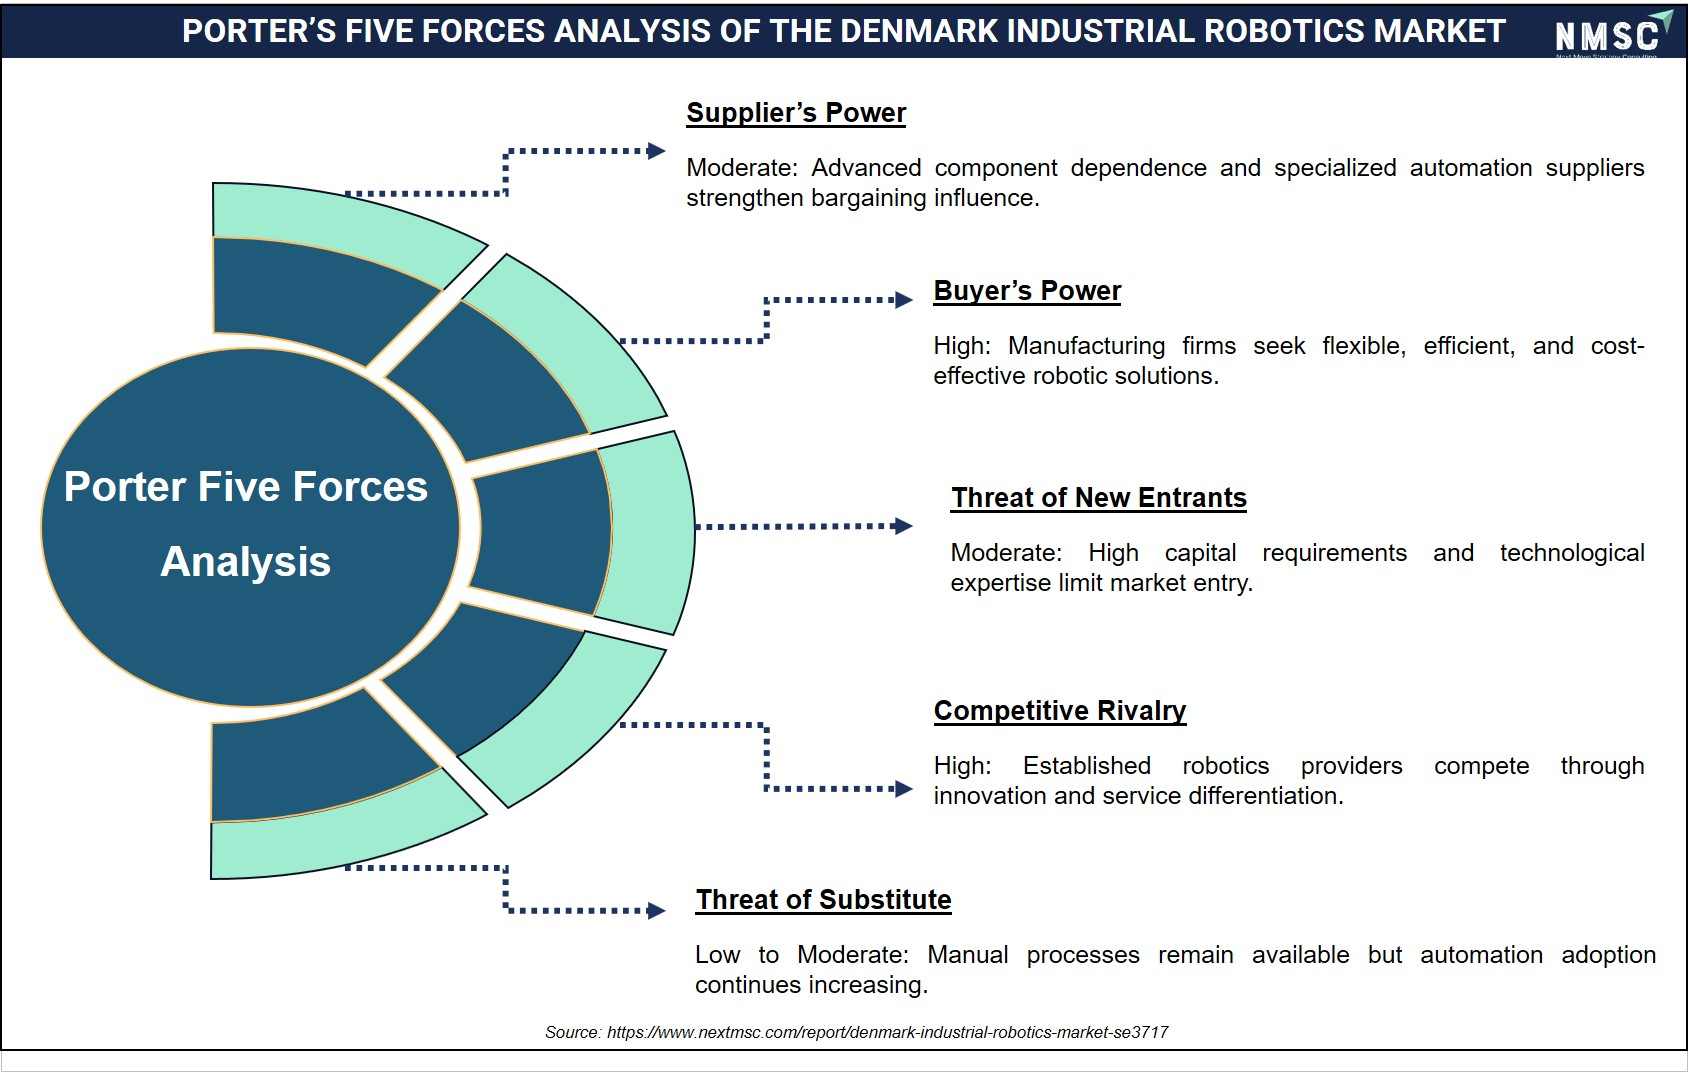
NMSC’s analysis indicates that the Denmark industrial robotics market is shaped by strong buyer demand for flexible automation, moderate supplier influence, and high competitive rivalry among established robotics providers. Additionally, technological expertise and capital requirements create moderate barriers for new entrants, whereas manual alternatives exert relatively low substitution pressure. Therefore, manufacturers increasingly prioritize innovative, cost-efficient robotic solutions to improve productivity, maintain competitiveness, and support ongoing industrial automation initiatives.
Investment Opportunities
What Capital Inflows Are Targeting the Denmark Industrial Robotics Market?
Capital inflows into the Denmark Industrial Robotics Market are increasingly directed toward collaborative robotics, mobile automation, and AI-enabled deployment software. Leading Danish robot manufacturers continue to attract ownership investment and strategic capital to expand product development and global distribution. We observed that investors favor companies demonstrating strong partner ecosystems, established service networks, and diversified end-user exposure, viewing these attributes as key indicators of long-term market growth across Denmark.
How Is Infrastructure Investment Supporting the Denmark Industrial Robotics Market?
Infrastructure investment is expanding robot manufacturing, research, and training facilities across Denmark's Odense-centered robotics cluster. Our findings suggest that companies are investing in local application engineering centers, demonstration facilities, and technician training programs to support faster commissioning and after-sales service. In addition, manufacturers are strengthening partnerships with food processing, pharmaceutical, and logistics operators to enhance market penetration across Denmark.
What ESG Considerations Are Shaping Investment Decisions in the Denmark Industrial Robotics Market?
Environmental, social, and governance considerations are increasingly integral to investment decisions across the Denmark Industrial Robotics Market, with energy-efficient robot design, workplace safety, and workforce reskilling emerging as key priorities. We found that investors increasingly favor companies demonstrating measurable progress in reducing robot energy consumption, improving human-robot collaboration safety, and supporting technician retraining programs. These initiatives strengthen brand reputation while supporting long-term value creation across Denmark's evolving industrial automation sector.
Key Benefits for Stakeholders
How Does This Report Benefit Enterprise and Industry Leaders?
Enterprise and industry leaders gain access to validated segmentation, competitive benchmarking, and technology adoption analysis that support strategic planning, capital allocation, and automation roadmap development across the Denmark Industrial Robotics Market. Our analysis shows that detailed assessments of robot type, offering, application, and end-user trends help manufacturers and integrators identify high-growth opportunities, strengthen market positioning, and develop effective long-term automation strategies.
How Does This Report Benefit Investors and Financial Analysts?
Investors and financial analysts benefit from consistent market size estimates, growth forecasts, and competitive assessments that support investment evaluation and capital allocation decisions across the Denmark Industrial Robotics Market. We observed that the report's detailed analysis of collaborative robotics, mobile automation, and software segments enables stakeholders to identify companies and market categories with the strongest long-term growth potential through 2035.
How Does This Report Benefit Technology Vendors and Product Teams?
Technology vendors and product development teams gain valuable insights into emerging innovation trends, including advanced gripping technology, autonomous mobile robot fleet management, and AI-enabled deployment software that are transforming Danish industrial automation. Our findings suggest that this analysis helps research and development teams prioritize future product pipelines, accelerate innovation initiatives, and align product offerings with evolving customer expectations across the Denmark Industrial Robotics Market.
Key Market Segments
By Robot Type
-
Articulated Robots
-
SCARA Robots
-
Cartesian and Gantry Robots
-
Delta Robots
-
Collaborative Robots
-
Autonomous Mobile Robots (AMRs)
-
Automated Guided Vehicles (AGVs)
-
Other Robots
By Offering
-
Hardware
-
Robot Arms
-
Controllers
-
End Effectors and Grippers
-
Sensors and Vision Systems
-
-
Software
-
Control and Programming Software
-
Simulation and Offline Programming Software
-
Fleet Management Software
-
-
Services
-
System Integration and Installation
-
Maintenance and Support
-
Training and Consulting
-
By Application
-
Handling
-
Pick and Place
-
Machine Tending
-
Palletizing and Depalletizing
-
-
Welding and Soldering
-
Assembly and Disassembly
-
Dispensing
-
Painting
-
Adhesive and Sealant Application
-
-
Processing
-
Cutting and Machining
-
Grinding and Polishing
-
-
Cleanroom Operations
-
Inspection and Quality Control
-
Packaging and Labeling
-
Intralogistics and Transport
By Mounting Type
-
Floor Mounted
-
Wall-Mounted
-
Ceiling Mounted
-
Rail Mounted
By Mobility
-
Stationary Robots
-
Mobile Robots
By Payload Capacity
-
Low Payload Up to 20 kg
-
Medium Payload 20 kg to 100 kg
-
High Payload 100 kg to 500 kg
-
Heavy Duty Payload Over 500 kg
By End User
-
Automotive Industry
-
Electrical and Electronics Industry
-
Metals and Machinery Industry
-
Food and Beverages Industry
-
Pharmaceuticals and Medical Devices Industry
-
Plastics Rubber and Chemicals Industry
-
Logistics and Warehousing
-
Other Industries
Conclusion and Recommendations
What Is the Long-Term Outlook for the Denmark Industrial Robotics Market?
The long-term outlook for the Denmark Industrial Robotics Market remains positive, supported by sustained labor cost pressures, expanding pharmaceutical and food processing automation, and continued strength of Denmark's cobot and mobile robotics innovation cluster. We observed that growing adoption of collaborative robots, autonomous mobile robots, and AI-enabled deployment software will continue to drive market expansion across food, pharmaceutical, and logistics segments throughout the forecast period.
What Strategic Positioning Should Robotics Companies Pursue?
Manufacturers should prioritize investments in collaborative robotics, advanced end-of-arm tooling, and local system integration capabilities while strengthening service networks across Danish industrial regions. Our assessment indicates that companies expanding flexible financing models, application-specific automation solutions, and AI-enabled deployment software will be well positioned to capture demand from small and mid-sized manufacturers within the Denmark Industrial Robotics Market.
How Attractive Is the Denmark Industrial Robotics Market for New Investment?
The Denmark Industrial Robotics Market presents an attractive investment opportunity, supported by rising automation spending, expanding pharmaceutical manufacturing, and continued innovation in collaborative and mobile robotics. We found that investment potential is particularly strong for companies focused on advanced gripping technology, fleet management software, and flexible financing models, enabling them to capitalize on evolving customer preferences and long-term market growth.
What Market Shifts and Key Risks Should Stakeholders Monitor?
Stakeholders should closely monitor evolving automation technology standards, shortages of qualified robotics engineers, and fluctuations in component supply chains. Our analysis shows that companies unable to continuously innovate, expand service capacity, or address integration cost barriers may face increasing competitive pressure within the Denmark Industrial Robotics Market.
What Are the Key Growth Pathways for the Denmark Industrial Robotics Market?
Key growth pathways include expanding collaborative and mobile robot portfolios, accelerating innovation in advanced gripping and AI-enabled deployment software, strengthening flexible financing models, and enhancing local system integration capabilities. NMSC's analysis indicates that companies successfully combining hardware reliability, software-driven flexibility, and strong partner ecosystems will be best positioned to capture the Denmark Industrial Robotics Market's projected growth through 2035.
About the Author
 Mihul Sharma
— Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

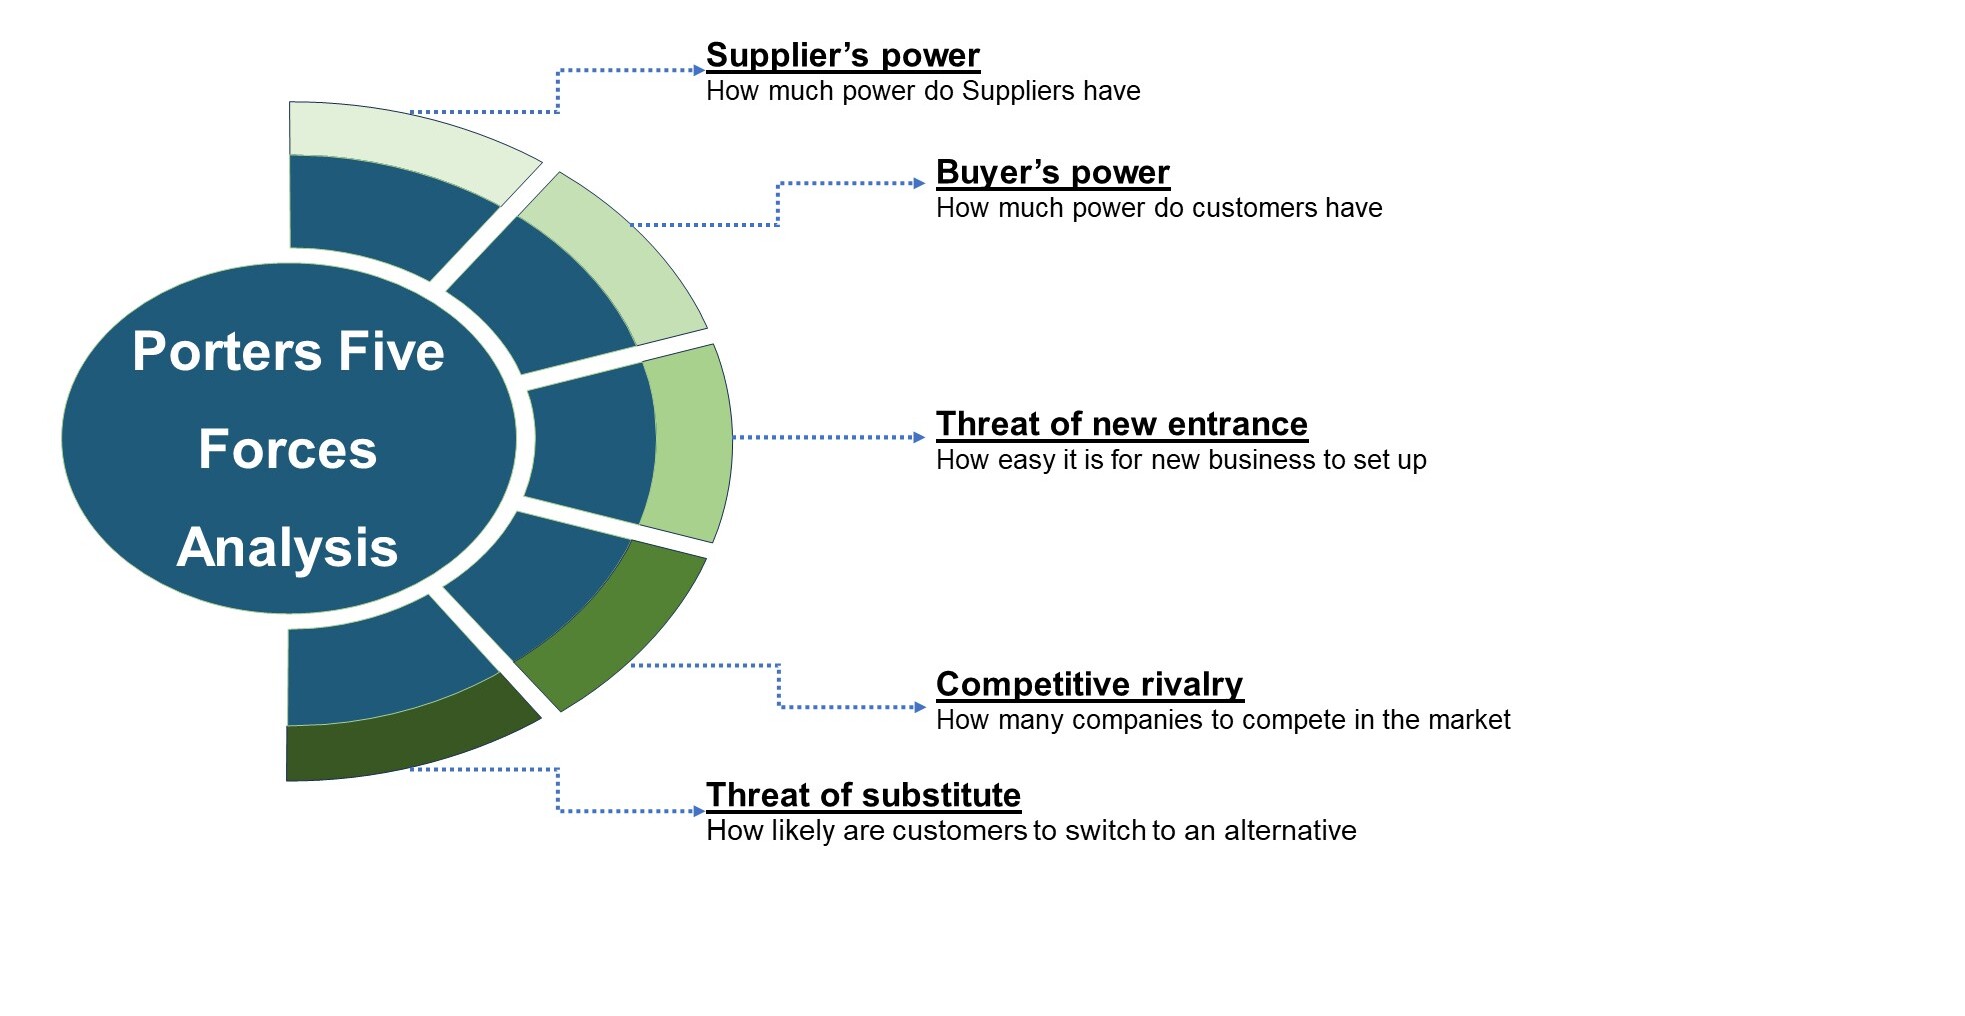
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.



 Speak to Our Analyst