Electromagnetic Components Market Global Industry Analysis and Forecast (2026–2035)

Electromagnetic Components Market size was USD 26.52 Billion in 2025, projected to reach USD 48.49 Billion by 2035, growing at a CAGR of 6.01% from 2026 to 2035. Key drivers include AI data center power demand, EV electrification, and tighter EMC rules, with Asia-Pacific leading the market.
Download Free Sample PDF
Base Year (2025)
$26.52 Billion
Forecast (2035)
$48.49 Billion
CAGR (2026-2035)
6.0%
Top Region
Asia-Pacific

What Is the Electromagnetic Components Market Size?
The Electromagnetic Components Market covers inductors, transformers, EMI suppression parts, relays, contactors, and actuators that store, convert, filter, or switch electrical energy. The market reached USD 26.52 Billion in 2025 and is estimated at USD 28.68 Billion in 2026. It will reach USD 48.49 Billion by 2035, a CAGR of 6.01% from 2026 to 2035. Asia-Pacific held about a 55% share and Inductors about 38% in 2025.
We observed that demand is shifting from consumer devices toward AI servers, electric vehicles, and power grids, as the quick stats below show.

Electromagnetic Components Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast
Values in USD Billion

2025 $26.52 Billion
2025
2026 $28.68 Billion
2026
2027 $30.40 Billion
2027
2028 $32.23 Billion
2028
2029 $34.17 Billion
2029
2030 $36.22 Billion
2030
2031 $38.40 Billion
2031
2032 $40.71 Billion
2032
2033 $43.15 Billion
2033
2034 $45.75 Billion
2034
2035 $48.49 Billion
2035

Key Takeaways

By Component: Inductors held the largest share, expanding from USD 10.02 Billion in 2025 to USD 19.40 Billion by 2035; EMI Suppression Components is the fastest-growing at 7.98% CAGR from 2026–2035.

By Type: Standard held the largest share, expanding from USD 18.15 Billion in 2025 to USD 31.03 Billion by 2035; Custom is the fastest-growing at 7.40% CAGR from 2026–2035.

By End-Use Industry: Automotive and Mobility held the largest share, expanding from USD 7.93 Billion in 2025 to USD 15.03 Billion by 2035; Data Centers and IT is the fastest-growing at 10.90% CAGR from 2026–2035.

By Sales Channel: Direct Sales held the largest share, expanding from USD 13.85 Billion in 2025 to USD 24.25 Billion by 2035; Distribution Partners is the fastest-growing at 6.49% CAGR from 2026–2035.

Dominant Region: Asia-Pacific, with about 55% share and USD 14.53 Billion in 2025, rising to USD 27.64 Billion by 2035.

Fastest-Growing Region: Middle East & Africa at 8.67% CAGR from 2026–2035, rising from USD 1.03 Billion in 2025 to USD 2.43 Billion by 2035.

Dominant Country: China, with USD 7.26 Billion in 2025, rising to USD 13.82 Billion by 2035.

Fastest-Growing Country: India at 12.58% CAGR from 2026–2035, rising from USD 0.81 Billion in 2025 to USD 2.76 Billion by 2035.

The Electromagnetic Components Market offers an absolute investment opportunity of about USD 19.81 Billion between 2026 and 2035, which signals strong returns for suppliers that secure automotive and data center qualifications early.
According to NMSC analysis, EMI Filters are the least discussed growth engine, because every new fast charger, inverter, and AI server board needs certified noise control.

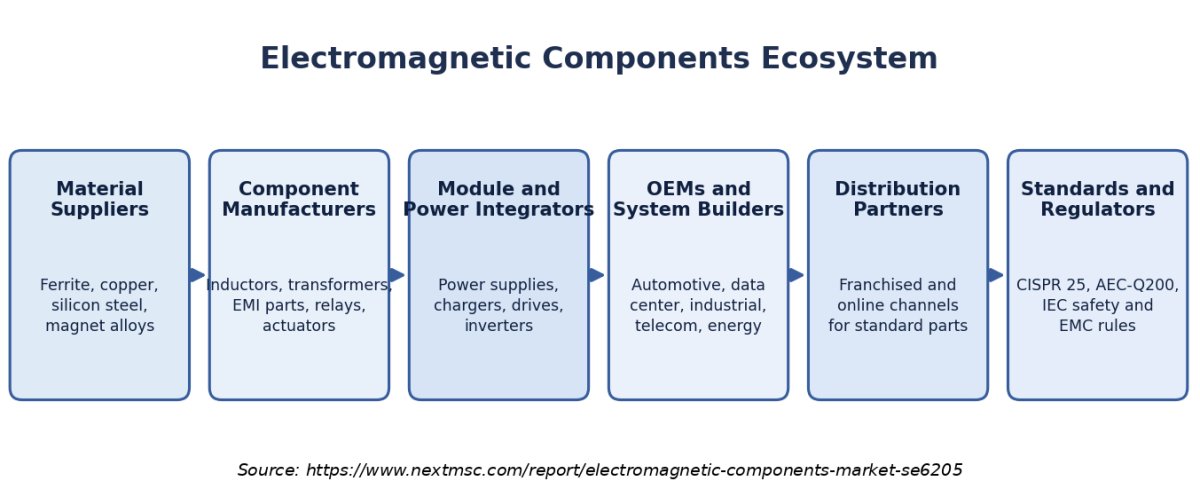
Ecosystem Analysis of the Electromagnetic Components Industry

The above infographic presents the ecosystem in six linked groups. Material suppliers provide ferrite, copper and alloy inputs to component makers. Module and power integrators turn parts into chargers, drives and power supplies, which OEMs install in vehicles, servers and machines. Distribution partners serve smaller designers, while standards bodies and regulators set safety, noise, and automotive qualification rules that shape every design decision.

What does the Electromagnetic Components Market Encompass?
The Electromagnetic Components Market includes passive and electromechanical devices that use magnetic fields to store energy, transfer power, filter noise, or switch circuits. Core product groups are inductors, transformers, EMI suppression components, relays and contactors, and actuators. We found that buyers increasingly specify these parts as sets, because power stages, filters and switching devices must be validated together. Standard catalog parts serve volume designs, while custom parts address high current, high voltage, and tight space limits.
Regulation shapes design choices across the value chain. Automotive buyers require AEC-Q200 qualification and compliance with CISPR 25 emission limits. Industrial and building customers follow IEC safety rules for relays and contactors. Technology adoption is moving toward thin film and metal composite inductors, planar magnetics, and higher switching frequencies. Our analysis shows that thermal performance, qualification time, and material cost now decide supplier selection more than unit price alone.

Market Drivers & Dynamics

Interactive Dataset
AI data center power demand lifting inductor and transformer content driver +1.4% North America, Asia-Pacific 2026–2035
EV production and rising onboard electronics content driver +1.2% Asia-Pacific, Europe 2026–2035
Grid modernization and battery energy storage projects driver +0.7% Global 2026–2032
Stricter EMC rules and automotive qualification needs driver +0.5% Europe, North America, Asia-Pacific 2026–2030
Wireless charging adoption in phones and vehicles driver +0.4% Global 2026–2033
Rare earth, copper and ferrite supply volatility restraint −0.9% Global 2026–2029
Tariffs and component price cycles restraint −0.6% North America, Europe 2026–2028
Mature consumer electronics and declining ICE vehicle volumes restraint −0.5% Global 2026–2035
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver in the Electromagnetic Components Market?

AI data center buildout is the primary driver of the Electromagnetic Components Market. The IEA estimates that data center electricity use was about 415 TWh in 2024 and will reach around 945 TWh by 2030. Every added megawatt needs transformers, chokes, and power inductors across conversion stages. Data Centers and IT rise from USD 3.01 Billion in 2025 to USD 8.73 Billion in 2035. Hyperscale datacenter operators are placing large multiyear orders.

How Is Vehicle Electrification Driving Market Growth?

Electrification raises magnetic content in every vehicle class. The IEA expects global electric car sales to reach 23 million in 2026, about 28% of new car sales. EVs within Automotive and Mobility grow from USD 3.97 Billion in 2025 to USD 10.52 Billion by 2035, a CAGR of 9.98% from 2026 to 2035. Charging networks add demand for contactors, transformers, and filters outside the vehicle. Expansion of EV charging station networks supports DC contactor orders.

Growth Inhibitors

What Is Restraining the Electromagnetic Components Market?

Material and policy risk is the main restraint. China placed export controls on selected rare earth items in April 2025, and licensing delays continue to affect buyers. China exported 5,375 metric tons of rare earth magnets in July 2026, yet shipments to the United States from January to July 2026 stayed about 16% below the same period of 2024. Actuators, relays, and motors that use magnets face price swings and longer lead times. Buyers are qualifying second sources and rare earth magnet alternatives.

What Are the Growth Opportunities?

Can Thin Film and Metal Composite Inductors Capture AI Server Power Stages?

Thin film Power Inductors grow from USD 0.72 Billion in 2025 to USD 1.86 Billion by 2035. Compact, low-loss parts fit optical transceivers and point-of-load converters where board space is scarce. Suppliers with alloy powder and plating expertise can serve server boards and edge datacenter nodes. Vendors that qualify early with hyperscale designers can secure multiyear platform wins.

Is EMI Filtering a Whitespace Opportunity in Electrified Platforms?

EMI Filters grow at 10.03% CAGR from 2026 to 2035, the fastest rate among EMI subsegments. Inverters, onboard chargers, and fast data links need filters that pass CISPR 25 limits without adding weight. Suppliers that package chokes, beads and filters into tested reference designs shorten customer validation time. Tier one automotive suppliers and server builders are the main beneficiaries.

Does DC Contactor Demand Create a Premium Niche in Charging and Storage?

DC Contactors rise from USD 0.49 Billion in 2025 to USD 1.17 Billion by 2035, a CAGR of 8.75% from 2026 to 2035. Storage systems, charging stations, and electric trucks need contactors that interrupt high direct current safely. Makers with sealed, high-voltage designs and arc control know-how can win long qualification cycles. Battery energy storage system integrators and charger makers benefit most.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Inductors 2025: $10.02 Billion | 2035: $19.40 Billion
Inductors
Transformers 2025: $6.98 Billion | 2035: $11.15 Billion
Transformers
EMI Suppression Components 2025: $3.64 Billion | 2035: $8.00 Billion
EMI Suppress
Relays and Contactors 2025: $4.30 Billion | 2035: $6.79 Billion
Relays and C
Actuators 2025: $1.58 Billion | 2035: $3.15 Billion
Actuators
Inductors $10.02 Billion $19.40 Billion 6.62%
Transformers $6.98 Billion $11.15 Billion 4.57%
EMI Suppression Components $3.64 Billion $8.00 Billion 7.98%
Relays and Contactors $4.30 Billion $6.79 Billion 4.45%
Actuators $1.58 Billion $3.15 Billion 6.95%

Segment Sizing: By Component

2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 26.0%
Category B $17.1 USD Billion $51.1 USD Billion 24.0%
Category C $24.2 USD Billion $62.2 USD Billion 18.0%
Category D $31.3 USD Billion $73.3 USD Billion 8.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Type.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 9.0%
Category B $17.1 USD Billion $51.1 USD Billion 11.0%
Category C $24.2 USD Billion $62.2 USD Billion 25.0%
Category D $31.3 USD Billion $73.3 USD Billion 15.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End-Use Industry.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Category A
Category B
Category C
Category D
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Category A $10.0 USD Billion $40.0 USD Billion 26.0%
Category B $17.1 USD Billion $51.1 USD Billion 24.0%
Category C $24.2 USD Billion $62.2 USD Billion 22.0%
Category D $31.3 USD Billion $73.3 USD Billion 20.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Sales Channel.

Unlock Full Data

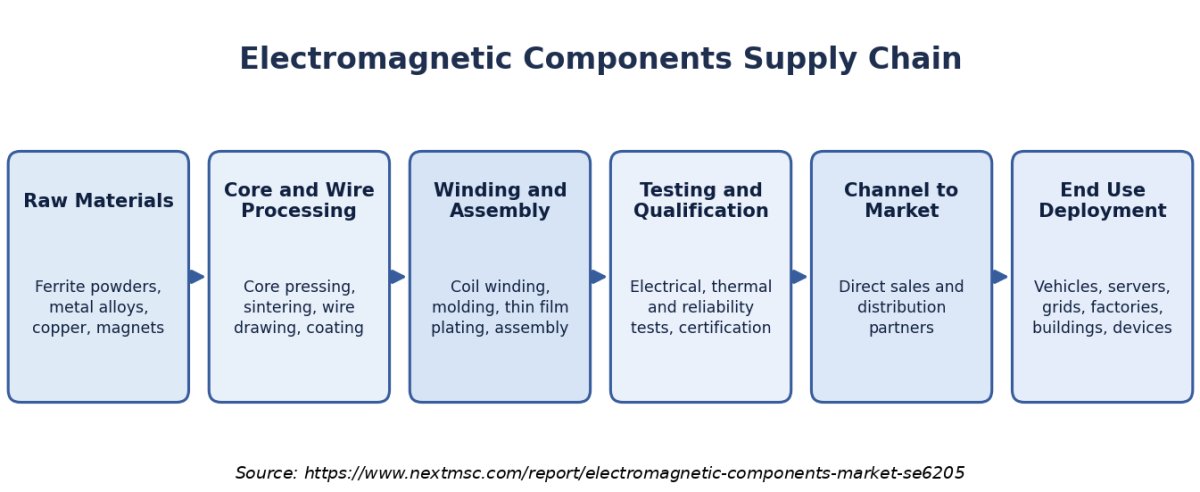
Supply Chain Analysis of the Electromagnetic Components Industry

Supply Chain Analysis of the Electromagnetic Components Industry
The above infographic maps the supply chain from raw materials to end use deployment. Ferrite powders, metal alloys, copper and magnets move into core pressing, sintering and wire coating. Coil winding, molding and thin film plating follow, then electrical, thermal and reliability tests. Manufacturers sell directly to large buyers or through distributors, and the final parts enter vehicles, servers, grids, factories, buildings and devices.

Growth Opportunities

Our findings suggest that three whitespace opportunities can generate faster growth than the overall market.

Can Thin Film and Metal Composite Inductors Capture AI Server Power Stages?

Thin film Power Inductors grow from USD 0.72 Billion in 2025 to USD 1.86 Billion by 2035. Compact, low-loss parts fit optical transceivers and point-of-load converters where board space is scarce. Suppliers with alloy powder and plating expertise can serve server boards and edge datacenter nodes. Vendors that qualify early with hyperscale designers can secure multiyear platform wins.

Is EMI Filtering a Whitespace Opportunity in Electrified Platforms?

EMI Filters grow at 10.03% CAGR from 2026 to 2035, the fastest rate among EMI subsegments. Inverters, onboard chargers, and fast data links need filters that pass CISPR 25 limits without adding weight. Suppliers that package chokes, beads and filters into tested reference designs shorten customer validation time. Tier one automotive suppliers and server builders are the main beneficiaries.

Does DC Contactor Demand Create a Premium Niche in Charging and Storage?

DC Contactors rise from USD 0.49 Billion in 2025 to USD 1.17 Billion by 2035, a CAGR of 8.75% from 2026 to 2035. Storage systems, charging stations, and electric trucks need contactors that interrupt high direct current safely. Makers with sealed, high-voltage designs and arc control know-how can win long qualification cycles. Battery energy storage system integrators and charger makers benefit most.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

Our findings suggest that the competitive landscape rewards scale in materials, qualification depth and application engineering.

Dimension Description
Market Structure Fragmented by product line, with global leaders in inductors and relays and many specialists in transformers and actuators.
Innovation Focus Low-loss materials, thin-film and metal-composite inductors, planar magnetics, and automotive-grade EMC parts.
M&A Activity Portfolio reshaping, including the 2026 separation of OMRON electronic components business into Aratas Corporation.

How Do Companies Compete in the Electromagnetic Components Market?

Companies compete on materials expertise, qualification records, capacity and application support. Large Japanese, Taiwanese and Chinese makers use scale to serve consumer and automotive volumes, while specialists win in high current, high voltage and custom designs. Pricing follows raw material and capacity cycles. Geographic expansion focuses on Southeast Asia, India, and Europe to reduce tariff and concentration risk. Distributors extend reach to small designers, so channel coverage is a strategic asset in the Electromagnetic Components Market.

Which Competitive Archetypes Dominate the Market?

Three archetypes dominate. Global passive leaders such as Murata, TDK, YAGEO, and Taiyo Yuden compete through materials science and broad catalogs. Switching and electromechanical specialists such as Hongfa, TE Connectivity, Panasonic Industry, Aratas, Kendrion and Standex compete through reliability and certification. Magnetics-focused firms such as Coilcraft, Würth Elektronik, Bourns, Sumida, Tamura and Cyntec compete through design flexibility and fast samples. Differentiation themes include loss reduction, thermal margin and safety approvals.

What Innovation and Differentiation Strategies Are Companies Pursuing?

Leaders invest in thin film, metal alloy, and nanocrystalline materials to cut losses and shrink footprints. TDK, Murata and Vishay launched new inductor families in 2025 and 2026 aimed at AI servers and vehicles. Coilcraft targets automotive emission limits with high isolation chokes. Suppliers also publish reference designs and simulation models, which shorten customer design cycles. Higher temperature ratings, lower DC resistance, and AEC-Q200 qualification are now common differentiators.

What M&A and Partnership Activity Is Shaping the Market?

Portfolio reshaping is the main theme. OMRON separated its electronic components business, which began operating as Aratas Corporation on 1 July 2026 and became independent on 1 October 2026 after acquisition by Carlyle. The new company plans to focus on switching, connecting, and sensing, with attention to energy management and mobility. We expect further carve-outs, bolt-on deals for magnetics specialists, and supply agreements with data center and automotive customers.

Key Market Players

During our market evaluation, we noticed that the leading suppliers span passive component groups, relay specialists, and magnetics-focused firms.

Murata Manufacturing Co., Ltd. TDK Corporation Hongfa Technology Co., Ltd. YAGEO Corporation TE Connectivity plc Aratas Corporation Panasonic Industry Co., Ltd. SUMIDA CORPORATION TAIYO YUDEN CO., LTD. Samsung Electro-Mechanics Co., Ltd. Shenzhen Sunlord Electronics Co., Ltd. Cyntec Co., Ltd. Vishay Intertechnology, Inc. Tamura Corporation Würth Elektronik eiSos GmbH & Co. KG Kendrion N.V. Littelfuse, Inc. Standex International Corporation Coilcraft, Inc. Bourns, Inc.

Latest Developments

We observed that recent launches and ownership changes center on AI data centers, vehicles, and EMC compliance.

Date Event
September 2026 Murata added nine inductance values, from 0.10 µH to 4.7 µH, to its automotive-grade DFE2MCPH_JL metal power inductor series for ADAS and infotainment circuits.
May 2026 Vishay Intertechnology added four IHXL series inductors rated up to 209 A, with 20% lower core losses and operation up to 155 °C.
February 2026 Coilcraft expanded its CMA family of surface-mount toroidal common mode chokes with high isolation voltage for power line EMI suppression in automotive and industrial systems.
August 2025 TDK expanded its PLEC69B thin film inductor series for separating data signals from power in optical transceivers used in AI data centers; mass production began in August 2025.

Expert Insights

Rohit Saini

Rohit Saini

Head of Sales (Global and Domestic) | Cosmo Ferrites

"“Smart metering and grid infrastructure are also driving ferrite use because digital meters, converters, and power systems require magnetic components.”"

Analyst Interpretation

The statement highlights the growing use of magnetic components in power conversion, electric vehicles, renewable energy and smart metering. Ferrite cores support inductors, transformers and EMI filters, enabling efficient power management and electromagnetic compatibility. These applications create opportunities for manufacturers offering high-performance components with improved thermal stability, frequency performance and noise suppression across automotive, industrial and energy sectors.

Investment Opportunities

Where Are Capital Inflows Concentrating in the Electromagnetic Components Market?

Capital is flowing toward capacity for inductors and EMI parts serving AI servers and vehicles. Private equity interest, shown by Carlyle purchasing the OMRON electronic components business that became Aratas, signals confidence in relays and switching parts. Listed leaders continue to add production and research capacity. We found that investors favor firms with automotive qualification, data center exposure, and secure material supply.

How Is Infrastructure Investment Shaping Market Capacity?

Grid expansion and data center construction translate into long-lived demand for transformers, contactors and chokes. The IEA warns that around 20% of planned data center projects could face delays unless grid constraints are addressed, which keeps power equipment in focus. Manufacturers respond by adding winding lines, automation, and test capacity near customers. Capacity additions concentrate in Asia, with selective expansion in Europe and North America for resilience.

What ESG Considerations Are Influencing Market Investment?

Buyers now ask for lower loss designs, recycled copper content, and responsible sourcing of rare earths. Efficient inductors and transformers reduce heat and electricity use in servers and vehicles. Aratas notes that low contact resistance means less heat and less energy wasted in its switching products. Investors also review conflict mineral compliance and supplier emissions reporting, which favors transparent, well-governed manufacturers.

Key Benefits for Stakeholders

How Does This Report Benefit Industry Leaders and Design Engineers?

Industry leaders gain a segmented view of demand across five component groups, ten end-use industries, and five regions. The report shows which parts grow faster than the 6.01% market rate, such as EMI Filters and DC Contactors. Procurement teams can use the forecasts to plan multiyear supply agreements. Design engineers can compare technology paths, from thin film inductors to planar magnetics, against automotive and data center requirements.

How Does This Report Benefit Investors and Financial Analysts?

Investors receive a USD 19.81 Billion absolute growth view for 2026 to 2035, split by segment and region. The analysis highlights faster growth pockets, including Data Centers and IT at 10.90% CAGR and India at 12.58% CAGR. Analysts can test supplier exposure to automotive, data center, and energy demand. The report also outlines supply risks, such as rare earth licensing, that can affect margins and valuation.

How Does This Report Benefit Component Manufacturers and Technology Vendors?

Manufacturers can identify which product lines and channels deserve capacity and research spending. The report compares Standard and Custom demand, showing Custom parts growing at a 7.40% CAGR. Vendors can map competitor strategies, recent launches and ownership changes, including the Aratas separation from OMRON. Product teams can align roadmaps with EMC rules, thermal needs, and miniaturization trends in vehicles and AI servers.

Key Market Segments Evaluated

By Component

  • Inductors 
    • Power Inductors
      • Wire-Wound
      • Molded
      • Multilayer
      • Thin-Film
    • RF and Signal Inductors
      • Wire-Wound
      • Multilayer
      • Thin-Film
    • Wireless Power Coils
  • Transformers 
    • Power Transformers
      • SMPS Transformers
      • Low-Frequency Transformers
    • Signal Transformers
      • LAN Transformers
      • Pulse and Specialty Transformers
  • EMI Suppression Components 
    • Common Mode Chokes
    • Ferrite Beads
    • EMI Filters
  • Relays and Contactors 
    • Armature Relays
      • Signal Relays
      • Power Relays
    • Reed Relays
    • Contactors
      • AC Contactors
      • DC Contactors
  • Actuators 
    • Solenoids
      • Linear Solenoids
      • Rotary Solenoids
    • Brakes and Clutches
    • Other Actuators

By Type

  • Standard
  • Custom

By End-Use Industry

  • Automotive and Mobility 
    • EVs
    • ICE Vehicles
  • Industrial
  • Data Centers and IT
  • Telecom
  • Consumer Electronics and Appliances
  • Energy and Utilities
  • Building and HVAC
  • Healthcare
  • Aerospace and Defense
  • Others

By Sales Channel

  • Direct Sales
  • Distribution Partners

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The long-term outlook for the Electromagnetic Components Market is positive. Revenue climbs from USD 28.68 Billion in 2026 to USD 48.49 Billion by 2035, which equals a 6.01% CAGR. Growth comes from AI data centers, EVs, and grid projects rather than from mature consumer devices. Asia-Pacific stays the volume base, while the Middle East and Africa and India add the fastest incremental growth. Technology shifts toward thin film, planar, and metal composite magnetics.
What Strategic Positioning Recommendations Does NMSC Offer?

Suppliers should prioritize automotive-grade and data center-grade product lines, where qualification creates durable relationships. Investment in low-loss materials, automation, and local inventory supports pricing power. Custom design capability and reference designs shorten customer cycles. Firms should dual-source critical magnet and copper inputs and keep distributor partnerships strong. NMSC advises focusing on EMI suppression, DC contactors and thin film inductors, which outgrow the market.

How Strong Is Investment Attractiveness in the Electromagnetic Components Market?

Investment attractiveness is moderate to high. Revenue gains of USD 19.81 Billion over the forecast period come with several subsegments growing at close to double-digit rates. Barriers include qualification time, materials know-how, and customer relationships. Returns depend on cycle management, since price swings and inventory adjustments can compress margins. Selective exposure to data center, EV, and energy-linked suppliers appears most attractive.

What Are the Market Shifts and Key Risks in the Electromagnetic Components Market?

Key shifts include the move from catalog parts toward custom designs, the rise of automotive-grade filters, and the growth of data center power magnetics. Ownership changes such as the creation of Aratas also reshape competition. Key risks include rare earth licensing, copper and ferrite price swings, tariffs, and slower electric car sales in some markets. The IEA noted that global electric car sales fell 8% in the first quarter of 2026 after policy changes in China and the United States.

What Are the Primary Growth Pathways Through 2035?

Primary pathways include Data Centers and IT demand for power inductors and transformers, EV platforms that raise magnetic content per vehicle, and storage projects that need contactors and transformers. India, Saudi Arabia, and the UAE offer the fastest country growth. Wireless Power Coils grow at 8.81% CAGR as wireless charging spreads. Suppliers that combine materials innovation with strong application engineering can capture these pathways.

FAQs

Sources & References

1.

International Energy Agency, Energy and AI (Executive Summary)

iea.org
2.

International Energy Agency, Global EV Outlook 2026 (Executive Summary)

iea.org
3.

International Energy Agency, news release on electric car sales in 2026

iea.org
4.

TDK Corporation, press release of 26 August 2025

tdk.com
5.

Coilcraft, Inc., CMA series high isolation common mode chokes

coilcraft.com
6.

Vishay Intertechnology, Inc., press release of 27 May 2026

vishay.com
7.

Murata Manufacturing Co., Ltd., news release of 7 September 2026

murata.com
8.

Aratas Corporation, official company site

aratas.com/eu-en
9.

Silverado Policy Accelerator, China rare earth exports update (August 2026)

silverado.org
10.

Dealroom News, coverage of the Aratas carve out and European launch

dealroom.co

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Henri Knyphausen

HENRI KNYPHAUSEN

Partner at Singulier [Ex-BCG]

Singulier

I recently engaged NEXTMSC.com for a commercial due diligence project within the intralogistics sector, and I am pleased to provide a reference based on my experience. In utilizing NEXTMSC.com's services, I found their report to offer valuable insights into market dynamics and key industry players. The initial report provided a solid foundation for our analysis. However, as we were investigating a smaller target in the market, and I had specific customization requests requiring additional research. These requests included detailed information on product portfolios of various players and sub-market sizes, both inclusive and exclusive of certain product categories. NEXTMSC.com demonstrated commendable responsiveness and agility in accommodating these customization requests. Within a timeframe of 1-2 weeks, they delivered a revised report that met our specific needs. Furthermore, they were receptive to my follow-up inquiries, ensuring clarity and understanding of the data provided. The final deliverable significantly contributed to our due diligence efforts. One of NEXTMSC.com's notable strengths lies in their qualitative research capabilities. However, for future engagements, I would recommend the inclusion of a quantified market model in Excel format. Such a model would offer the ability to conduct in-depth analyses and explore various market segments, including country-specific data and subcomponent breakdowns. Based on my positive experience, I would not hesitate to work with NEXTMSC.com again. Their responsiveness, willingness to accommodate customization requests, and commitment to delivering actionable insights make them a reliable partner for commercial research projects.

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Mohit Agarwal

MOHIT AGARWAL

Chief Manager

DryChem India Pvt. Ltd.

Next Move Strategy Consulting is an amazing team of consultants. We required a market study report for our investors on top priority and the team went above and beyond our expectations to deliver the same with ample supporting data within a short time span enabling us to secure the investments and keep our project timeline maintained. Their professionalism, attention to detail, and timely delivery of actionable recommendations have left a lasting impression on our organization.

Gustaf Hummel Burstrom

GUSTAF HUMMEL BURSTROM

Founder

Revline Tools AB

Joseph and the team at Next Move Strategy Consulting have been excellent to work with, in supplying us with relevant market data and forecasts for our specific category. We had some special requirements and they were able to do a custom package to suit our needs. We would definitely recommend them to any other company needing market data and forecasts

Diana Trejo

DIANA TREJO

Assistant Manager

Sumitomo Corporation de Mexico, S.A. de C.V.

Recently, we purchased a report on the Mexico Data Center Market from Next Move Strategy Consulting. The service has been excellent, with support that is always timely and thoroughly professional. The information provided is interesting, highly useful, and delivered with clarity. I would highly recommend NextMSC for anyone seeking insightful and dependable analysis.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖