Open All Photonics Network Market Global Industry Analysis and Forecast (2026–2035)

The global Open All Photonics Network Market size was valued at USD 1.42 billion in 2025 and is estimated at USD 1.82 billion in 2026, forecast to reach USD 10.90 billion by 2035, expanding at a 22.0% CAGR between 2026 and 2035. Asia-Pacific leads with approximately 56% share, while Hardware dominates all other offering segments with approximately 62% share.
Download Free Sample PDF
Base Year (2025)
$1.42 Billion
Forecast (2035)
$10.90 Billion
CAGR (2026-2035)
22.0%
Top Region
Asia-Pacific

What Is the Open All Photonics Network Market Size?
The Open All Photonics Network Market was valued at USD 1.42 Billion in 2025 and is estimated at USD 1.82 Billion in 2026. Revenue is forecast to reach USD 10.90 Billion by 2035, a 22.0% CAGR over 2026–2035. Asia-Pacific held about 56% share in 2025, and Hardware led the offering mix with roughly 62% share.
We observed that spending remains concentrated around the commercial APN services of the NTT group in Japan, yet the architecture defined by the IOWN Global Forum is drawing carriers, cloud providers and data center operators into trials across Asia, Europe and North America. Demand is moving from demonstrations toward purchased transponders, gateways, controllers and hollow core fiber. The 2026 estimate steps up 28% over 2025 because of identifiable commercial activity, including NTT group service rollouts between major cities during fiscal 2026, NTT’s order for NEC’s SpectralWave WX-T white box transponder, deployment tests of hollow core cable by Prysmian and Relativity Networks, and the start of APN InterLink service in Hong Kong.

Our analysis shows that the leading segments differ sharply between the 2025 base and the 2035 forecast, as the Key Takeaways below summarize.

Open All Photonics Network Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast
Values in USD Billion

2025 $1.42 Billion
2025
2026 $1.82 Billion
2026
2027 $2.22 Billion
2027
2028 $2.71 Billion
2028
2029 $3.30 Billion
2029
2030 $4.03 Billion
2030
2031 $4.92 Billion
2031
2032 $6.00 Billion
2032
2033 $7.32 Billion
2033
2034 $8.93 Billion
2034
2035 $10.90 Billion
2035

Key Takeaways

By Offering: Hardware held the largest share, expanding from USD 0.88 Billion in 2025 to USD 6.38 Billion by 2035; Software is the fastest growing at 27.2% CAGR from 2026–2035.

By Network Domain: Data Center Interconnect (DCI) held the largest share, expanding from USD 0.48 Billion in 2025 to USD 4.14 Billion by 2035; Other Dedicated APN Links is the fastest growing at 24.0% CAGR from 2026–2035.

By Buyer Type: Telecom Operators and Wholesale Carriers held the largest share, expanding from USD 0.73 Billion in 2025 to USD 3.92 Billion by 2035; Cloud Service Providers is the fastest growing at 28.6% CAGR from 2026–2035.

By End-User Industry: Telecommunications held the largest share, expanding from USD 0.53 Billion in 2025 to USD 2.84 Billion by 2035; Cloud and Digital Infrastructure is the fastest growing at 26.8% CAGR from 2026–2035.

By Sales Channel: Direct Vendor Sales held the largest share, expanding from USD 0.89 Billion in 2025 to USD 5.89 Billion by 2035; Systems Integrators and Prime Contractors is the fastest growing at 25.0% CAGR from 2026–2035.

By Route Type: Terrestrial held the largest share, expanding from USD 1.36 Billion in 2025 to USD 9.81 Billion by 2035; Submarine is the fastest growing at 31.9% CAGR from 2026–2035.

Dominant Region: Asia-Pacific held about 56% of 2025 revenue, growing from USD 0.80 Billion in 2025 to USD 4.80 Billion by 2035.

Fastest-Growing Region: North America is projected to expand at 25.9% CAGR from 2026–2035, rising from USD 0.25 Billion in 2025 to USD 2.62 Billion by 2035.

Dominant Country: Japan led 2025 revenue at USD 0.38 Billion, supported by commercial services of the NTT group.

Fastest-Growing Country: India is the fastest growing at 28.5% CAGR from 2026–2035, rising from USD 0.05 Billion in 2025 to USD 0.67 Billion by 2035.

The Open All Photonics Network Market is projected to increase in annual value by approximately USD 9.08 Billion between 2026 and 2035, from USD 1.82 Billion to USD 10.90 Billion, which positions photonic path services as one of the faster compounding pools within optical infrastructure.
According to NMSC analysis, the shift from vendor specific optical transport to standards based wavelength and fiber path services is the most important structural change, because it lets buyers combine transceivers, gateways and controllers from different suppliers.

What Does the Open All Photonics Network Market Encompass?
The Open All Photonics Network Market covers equipment, software and services used to build photonic paths that carry traffic end to end without electronic processing at intermediate points. The scope follows the Open APN functional architecture of the IOWN Global Forum, which separates wavelength exchange (Open APN.WX) from fiber exchange (Open APN.FX) and adds an APN controller for control and management. Hardware, software, services and dedicated APN fiber with passive connectivity are sized together in this report.
Our findings suggest that the standards and policy environment is still forming. The IOWN Global Forum revised its Open APN functional architecture in June 2025 to add an APN splitter, and NTT targets completion of the related ITU-T draft recommendation in the first half of fiscal 2026. Japan's Ministry of Internal Affairs and Communications also funds cross carrier control and equipment configuration work for all photonics networks under its Beyond 5G fund.

SWOT Analysis

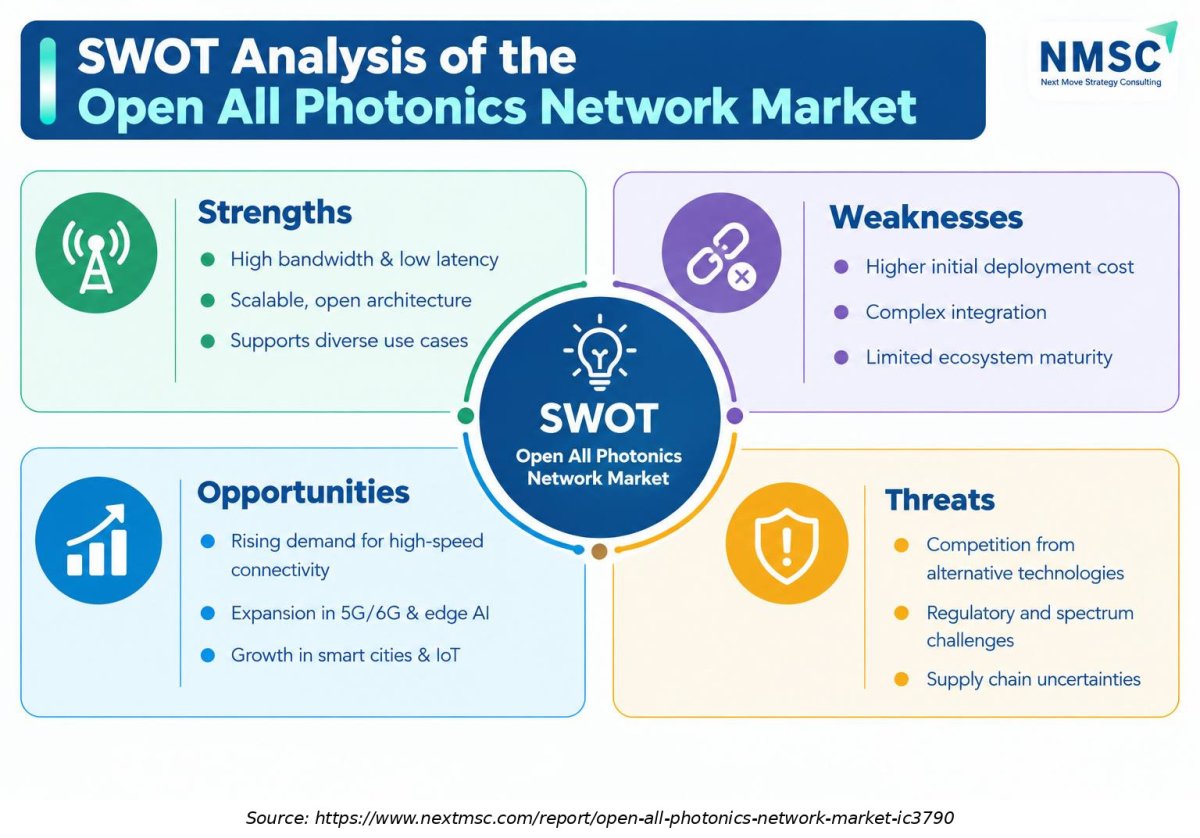
This SWOT view highlights structural strengths, strategic gaps, expansion headroom, and external risks shaping outcomes in the Open All Photonics Network Market Global Industry Analysis and Forecast (2026–2035).
Strengths

high bandwidth, low latency, scalable architecture, and support for diverse applications

Weaknesses

high deployment costs, integration complexity, and limited ecosystem maturity

Opportunities

Growing demand for high-speed connectivity, 5G/6G networks, edge AI, and smart cities

Threats

alternative technologies, regulatory challenges, and supply chain uncertainties

Market Drivers & Dynamics

Interactive Dataset
AI cluster and data center interconnect demand driver +3.1% Global, led by Asia-Pacific and North America 2026–2032
Commercial rollout of IOWN based services by the NTT group driver +2.6% Japan, Hong Kong, then Europe 2026–2030
Open APN standardization and controller maturity driver +2.2% Global 2026–2031
Energy efficiency pressure on data centers driver +1.8% Global 2026–2035
Hollow core fiber commercialization driver +1.4% North America, Europe, Asia-Pacific 2027–2035
Limited multivendor interoperability maturity restraint −2.4% Global 2026–2029
Dependence on one anchor operator for early demand restraint −1.9% Japan 2026–2028
Integration cost with existing ROADM and fiber plant restraint −1.5% Europe and North America 2026–2030
Component supply constraints for advanced optics restraint −0.9% Global 2026–2027
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver in the Open All Photonics Network Industry?

AI infrastructure is the primary driver of the Open All Photonics Network Market. The IEA projects that global data center electricity demand will more than double to about 945 TWh by 2030, which pushes operators toward architectures that move data between sites with less power and less delay. Open APN paths suit distributed GPU clusters, and ZTE reported field trials of large model training across three AI data centers over 600 km, evidence that long reach optical design now shapes cluster performance.

How Is Commercial Rollout by the NTT Group Driving Market Growth?

The NTT group has offered APN services since March 2023, and its All-Photonics Connect service provides guaranteed bandwidth of up to 800 Gbit/s between user sites. NTT plans major city links through fiscal 2026, prefectural capitals in fiscal 2027 and nationwide expansion by 2030. NTT Com Asia also began APN InterLink service for Hong Kong financial institutions from November 1, 2025, showing early export of the model.

Growth Inhibitors

What Is Restraining the Open All Photonics Network Market?

Interoperability maturity is the primary restraint. The Forum released its Open APN Controller PoC Reference in November 2025, which shows that multivendor control is still at proof of concept stage, while NTT targets commercial deployment of its step three architecture around 2028. Buyers outside Japan therefore wait for proven multivendor operation, and suppliers face uneven revenue until second operators commit to scale.

What Are the Growth Opportunities?

Can Hollow Core Fiber and Cable Become a Premium APN Fiber Category?

Hollow core fiber lets light travel faster than in glass within the Open All Photonics Network Market, so path delay falls and cluster reach extends. Fiber and cable makers gain a premium category, and the segment grows from USD 0.02 Billion in 2026 to USD 0.33 Billion by 2035 in our forecast. Keio University, OKI and Lightera Japan demonstrated bidirectional wideband WDM over a single hollow core fiber in May 2026, a step toward commercial line systems.

Does APN Control Software Create a Recurring Revenue Layer for Vendors?

APN-C control and management software authenticates endpoints, sets admission policy and provisions wavelength paths. APN deployment therefore requires appropriate control and management functionality, generally implemented through APN-C and its associated management interfaces. Where vendors license this functionality as software, they earn license and upgrade fees, and the line grows from USD 0.13 Billion in 2026 to USD 1.20 Billion by 2035. The OFC 2025 demonstration of OpenConfig and TransportPCE control shows that open interfaces can widen the supplier pool.

Can Systems Integrators Capture Multivendor Open APN Projects?

Multivendor builds need an accountable party to design, test and accept paths that join equipment from several suppliers. Integrators and prime contractors grow from USD 0.51 Billion in 2026 to USD 3.81 Billion by 2035, and they are well placed to link metro sites that host edge AI inference with core data centers. Fujitsu's Open APN Lab in Düsseldorf showed how verification services can precede carrier orders.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Hardware 2025: $0.88 Billion | 2035: $6.38 Billion
Hardware
Software 2025: $0.19 Billion | 2035: $2.18 Billion
Software
Services 2025: $0.35 Billion | 2035: $2.34 Billion
Services
Hardware $0.88 Billion $6.38 Billion 21.2%
Software $0.19 Billion $2.18 Billion 27.2%
Services $0.35 Billion $2.34 Billion 20.4%

Which Offering Segment Leads the Open All Photonics Network Industry?

Hardware leads with USD 0.88 Billion in 2025, or about 62% of revenue, because carriers and data center operators buy wavelength and fiber path equipment before they invest in software layers. Software is the fastest growing group at 27.2% CAGR over 2026–2035, rising to USD 2.18 Billion, as APN-C control platforms and planning tools become increasingly important for multivendor operation. Among individual lines, hollow core fiber and cable grows fastest at 36.5% from a small base.

2025 (USD Billion)
2035 (USD Billion)
Data Center
Mobile Front
Midhaul and
Optical Acce
Metro and Re
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Data Center Interconnect (DCI) $10.0 USD Billion $40.0 USD Billion 25.0%
Mobile Fronthaul $17.1 USD Billion $51.1 USD Billion 11.0%
Midhaul and Backhaul $24.2 USD Billion $62.2 USD Billion 25.0%
Optical Access and Campus Networks $31.3 USD Billion $73.3 USD Billion 11.0%
Metro and Regional Transport $38.4 USD Billion $84.4 USD Billion 16.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Network Domain.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Telecom Oper
Cloud Servic
Data Center
Enterprise a
Government a
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Telecom Operators and Wholesale Carriers $10.0 USD Billion $40.0 USD Billion 27.0%
Cloud Service Providers $17.1 USD Billion $51.1 USD Billion 9.0%
Data Center and Colocation Operators $24.2 USD Billion $62.2 USD Billion 19.0%
Enterprise and Industrial Buyers $31.3 USD Billion $73.3 USD Billion 17.0%
Government and Public Sector $38.4 USD Billion $84.4 USD Billion 18.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Buyer Type.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Telecommunic
Cloud and Di
Financial Se
Manufacturin
Energy and U
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Telecommunications $10.0 USD Billion $40.0 USD Billion 14.0%
Cloud and Digital Infrastructure $17.1 USD Billion $51.1 USD Billion 24.0%
Financial Services $24.2 USD Billion $62.2 USD Billion 22.0%
Manufacturing and Industrial $31.3 USD Billion $73.3 USD Billion 12.0%
Energy and Utilities $38.4 USD Billion $84.4 USD Billion 27.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By End-User Industry.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Direct Vendo
Distributors
Systems Inte
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Direct Vendor Sales $10.0 USD Billion $40.0 USD Billion 24.0%
Distributors and Resellers $17.1 USD Billion $51.1 USD Billion 22.0%
Systems Integrators and Prime Contractors $24.2 USD Billion $62.2 USD Billion 20.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Sales Channel.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
Terrestrial
Submarine
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
Terrestrial $10.0 USD Billion $40.0 USD Billion 23.0%
Submarine $17.1 USD Billion $51.1 USD Billion 9.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Route Type.

Unlock Full Data
2025 (USD Billion)
2035 (USD Billion)
North Americ
Canada
Mexico
Europe: UK
Germany
Segment Item 2025 (USD Billion) 2035 (USD Billion) CAGR
North America: U.S. $10.0 USD Billion $40.0 USD Billion 21.0%
Canada $17.1 USD Billion $51.1 USD Billion 23.0%
Mexico $24.2 USD Billion $62.2 USD Billion 25.0%
Europe: UK $31.3 USD Billion $73.3 USD Billion 15.0%
Germany $38.4 USD Billion $84.4 USD Billion 16.0%

Segment-wise data is locked

Unlock complete segment-wise numbers for By Region.

Unlock Full Data

Growth Opportunities

Our analysis shows that three whitespace opportunities are positioned to generate outsized revenue within the forecast window.

Can Hollow Core Fiber and Cable Become a Premium APN Fiber Category?

Hollow core fiber lets light travel faster than in glass within the Open All Photonics Network Market, so path delay falls and cluster reach extends. Fiber and cable makers gain a premium category, and the segment grows from USD 0.02 Billion in 2026 to USD 0.33 Billion by 2035 in our forecast. Keio University, OKI and Lightera Japan demonstrated bidirectional wideband WDM over a single hollow core fiber in May 2026, a step toward commercial line systems.

Does APN Control Software Create a Recurring Revenue Layer for Vendors?

APN-C control and management software authenticates endpoints, sets admission policy and provisions wavelength paths. APN deployment therefore requires appropriate control and management functionality, generally implemented through APN-C and its associated management interfaces. Where vendors license this functionality as software, they earn license and upgrade fees, and the line grows from USD 0.13 Billion in 2026 to USD 1.20 Billion by 2035. The OFC 2025 demonstration of OpenConfig and TransportPCE control shows that open interfaces can widen the supplier pool.

Can Systems Integrators Capture Multivendor Open APN Projects?

Multivendor builds need an accountable party to design, test and accept paths that join equipment from several suppliers. Integrators and prime contractors grow from USD 0.51 Billion in 2026 to USD 3.81 Billion by 2035, and they are well placed to link metro sites that host edge AI inference with core data centers. Fujitsu's Open APN Lab in Düsseldorf showed how verification services can precede carrier orders.

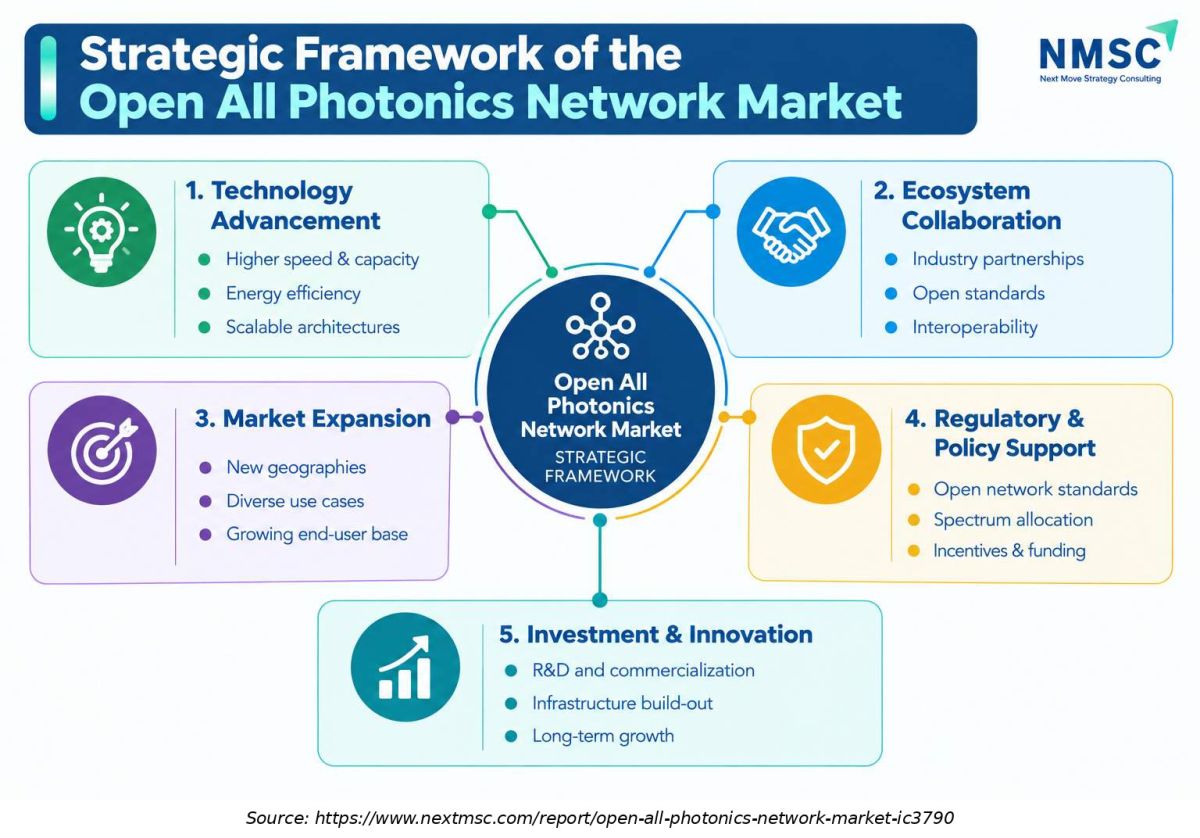
Strategic Framework of the Open All Photonics Network Market
Strategic Framework of the Open All Photonics Network Market
The strategic development of the Open All Photonics Network market depends on technological advancement, ecosystem collaboration, and sustained investment. Higher network capacity, energy efficiency, and scalable architectures can strengthen its value proposition. Industry partnerships and open standards are essential for interoperability, while supportive policies, infrastructure expansion, and continued R&D can accelerate commercialization and enable broader adoption across emerging applications.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

During our market evaluation, we noticed that competition spans equipment makers, optical component suppliers and fiber producers, each entering the Open APN value chain from a different direction.

Dimension Description
Market Structure Moderately concentrated, with one anchor operator driving early volumes and a mix of global and regional suppliers across equipment, software and fiber
Innovation Focus White box transponders, L and S band coherent optics, hollow core fiber and automated APN control software
M&A Activity Limited formal acquisitions; partnerships, supply agreements and joint demonstrations dominate

How Do Companies Compete in the Open All Photonics Network Industry?

Suppliers compete on conformance to the IOWN Global Forum architecture, power efficiency, automation and the ability to join multivendor trials. Fujitsu stated in 2023 that its 1FINITY Ultra Optical System, selected by NTT for core network verification, meets Open APN specifications, and NEC, Nokia and Ciena have each joined NTT led demonstrations. Pricing pressure rises as white box designs reduce the premium for integrated systems.

Which Supplier Archetypes Dominate the Market?

Three archetypes dominate. System vendors such as NEC, Nokia, Ciena and 1FINITY supply transceivers, gateways and controllers. Optical component specialists such as Coherent focus on pluggables and switching. Fiber and cable groups such as Sumitomo Electric, Furukawa Electric, Corning and Prysmian supply the path itself, while open optical specialists such as Smartoptics, Ekinops and PacketLight serve smaller buyers with cost focused designs.

How Are Leading Companies Differentiating Through Innovation?

Differentiation centers on automation, multiband capacity and fiber physics. Coherent presented 1.6T transceivers at OFC 2026, ZTE described a real time 1.2 Tb/s S band transceiver, and FiberHome promoted optical circuit switching for GPU clusters. Prysmian is scaling hollow core cable production, including investment at its Eindhoven site. Vendors that tie hardware to controller software gain stronger customer retention.

What Is the Level of M&A Activity in the Open APN Industry?

Formal acquisitions are rare in this niche, and partnerships carry most of the strategic weight. Prysmian and Relativity Networks reached a deployment milestone about 15 months after announcing their alliance, and Japan's Ministry of Internal Affairs and Communications selected a joint project by NTT, KDDI, Fujitsu, NEC and Rakuten Mobile in October 2024. We expect minority investments and joint ventures to grow as geographic expansion and pricing competition intensify.

Key Market Players

Based on research conducted by NMSC, the following 20 companies represent the leading participants in the Open All Photonics Network Market, listed in ranked order.

NEC Corporation Sumitomo Electric Industries, Ltd. Nokia Corporation 1FINITY Inc. Ciena Corporation Cisco Systems, Inc. Huawei Technologies Co., Ltd. ZTE Corporation Wuhan FiberHome Telecommunication Technologies Co., Ltd. Adtran Networks SE Ribbon Communications Inc. Tejas Networks Limited Ekinops S.A. Smartoptics Group ASA Padtec S.A. PacketLight Networks Ltd. Furukawa Electric Co., Ltd. Corning Incorporated Prysmian S.p.A. Coherent Corp.

Latest Developments

Our analysis shows that recent announcements cluster around standards, operator rollouts and hollow core fiber, which matches the demand drivers in this report.

Date Event
July 2026 Prysmian and Relativity Networks, working with Dura-Line, completed high-density deployment tests for ChronoCore hollow-core optical fiber cable in Dura-Line microducts. Testing confirmed installation at jetting speeds up to 350 feet per minute. The cable contains 24 hollow-core fibers in a 10 mm diameter design for AI data-center networks.
May 2026 OKI, Lightera Japan and Keio University demonstrated single-fiber, bidirectional wideband wavelength-division multiplexing using hollow-core fiber across 1.26–1.58 μm. The work combined OKI's prototype optical line system with Lightera's fiber and confirmed power optimization by switching to the most suitable optical line configuration.
May 2026 NTT outlined an IOWN All-Photonics Network rollout roadmap, targeting connections between major cities during fiscal 2026, expansion to prefectural capitals by fiscal 2027, and nationwide expansion by 2030 as demand develops. The plan also links network deployment with partner development of photonics-electronics convergence devices.
April 2026 At OFC 2026, IOWN Global Forum staged a multi-domain, multi-vendor demonstration of optical peering based on Open APN. The live showcase focused on interoperable photonics networking for scalable AI workloads and included industry discussions on optical circuit switches, co-packaged optics and open control interfaces.

Investment Opportunities

Where Are Capital Inflows Most Likely to Concentrate?

Capital is likely to flow toward control software, hollow core fiber capacity and integration capability, the segments with the highest growth in our forecast. Software is projected to reach USD 2.18 Billion by 2035, and hollow core fiber and cable reaches USD 0.33 Billion. Public funding also matters, as Japan's Beyond 5G fund backs cross carrier APN control work by NTT, KDDI, Fujitsu, NEC and Rakuten Mobile.

Which Infrastructure Investments Support Market Expansion?

Operators need to extend APN coverage from major cities to regional bases and data centers, which NTT plans through fiscal 2027 and toward nationwide expansion by 2030. Fiber makers also invest in capacity, and Prysmian is scaling ChronoCore hollow core fiber production, including at its Eindhoven facility. Investors should watch whether a second operator outside Japan commits to a wide commercial rollout.

How Do ESG Considerations Shape Open APN Investment?

Energy efficiency is the strongest ESG argument for the Open All Photonics Network Market. The IEA expects data center electricity demand to more than double to about 945 TWh by 2030, and photonic paths avoid electronic processing at intermediate nodes. In February 2025, NTT reported about 20% lower power use after adjusting active distributed units in a mobile fronthaul test, which supports the case for investment tied to emissions targets.

Key Benefits for Stakeholders

What Does This Report Offer Enterprise and Industry Leaders?

Enterprise and industry leaders receive segment and country forecasts that show when dedicated photonic paths become practical for their sites. Enterprise and Industrial Buyers grow from USD 0.11 Billion in 2025 to USD 0.98 Billion by 2035. The analysis helps buyers time procurement, compare route types and judge whether integrators or direct vendors suit their project size.

How Does This Report Support Investors and Financial Analysts?

Investors gain a reconciled forecast from USD 1.82 Billion in 2026 to USD 10.90 Billion by 2035, with segment CAGRs that show where growth concentrates. The risk matrix quantifies drivers and restraints, and the competitive analysis separates system vendors, component specialists and fiber producers. Analysts can use the data to test exposure to hollow core fiber, controller software and operator capital programs.

What Value Does This Report Provide to Technology Vendors and Product Teams?

Vendors and product teams can map each Open APN function, from APN-T pluggables to APN-C software, to its size and growth path. The report identifies which domains and buyers lead demand, how channels shift toward integrators, and where standards milestones may change requirements. Product teams can use these insights to prioritize interoperability testing and plan roadmaps around multiband and white box designs.

Key Market Segments Evaluated

By Offering

  • Hardware 
    • Open APN.WX Equipment
      • APN-T Pluggable Transceivers
      • APN-T Chassis Transponders and Muxponders
      • APN-G Gateways
      • APN-I Interchange Systems
      • APN-S Branching Equipment
      • Standalone APN Optical Line Amplifiers
      • Standalone APN Wavelength Converters
    • Open APN.FX Equipment
      • APN-FX Fiber Cross-Connects
      • APN-T(FX) Endpoint Transceivers
    • Dedicated APN Fiber and Passive Connectivity
      • Standard SMF Fiber and Cable
      • ULL SMF Fiber and Cable
      • Solid-Core MCF Fiber and Cable
      • Hollow-Core Fiber and Cable
      • Other APN-Qualified Fiber and Cable
      • Passive Connectivity Hardware
  • Software 
    • APN-C Control and Management Software
    • Standalone Network Management and Assurance Software
    • Network Planning and Simulation Software
  • Services 
    • Design and Integration Services
    • Deployment and Acceptance Services
    • Lifecycle Services

By Network Domain

  • Data Center Interconnect (DCI)
  • Mobile Fronthaul, Midhaul and Backhaul
  • Optical Access and Campus Networks
  • Metro and Regional Transport
  • Carrier Core and Long-Haul Transport
  • Other Dedicated APN Links

By Buyer Type

  • Telecom Operators and Wholesale Carriers
  • Cloud Service Providers
  • Data Center and Colocation Operators
  • Enterprise and Industrial Buyers
  • Government and Public Sector
  • Research and Education Institutions

By End-User Industry

  • Telecommunications
  • Cloud and Digital Infrastructure
  • Financial Services
  • Manufacturing and Industrial
  • Energy and Utilities
  • Healthcare and Life Sciences
  • Media and Broadcasting
  • Transportation and Logistics
  • Government and Defense
  • Education and Research
  • Other Industries

By Sales Channel

  • Direct Vendor Sales
  • Distributors and Resellers
  • Systems Integrators and Prime Contractors

By Route Type

  • Terrestrial
  • Submarine

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

Our findings suggest that the market moves from an operator led niche to a multiregion infrastructure category, expanding from USD 1.82 Billion in 2026 to USD 10.90 Billion by 2035. Growth comes from AI interconnect, standards progress and falling path latency, while region mix broadens as North America and Europe gain share. The outlook is strong yet depends on proven multivendor operation by 2028.

What Strategic Positioning Recommendations Does NMSC Offer?

We recommend that equipment vendors in the Open All Photonics Network Market align products with the Open APN functional blocks and invest early in controller interoperability. Fiber suppliers should qualify hollow core and ultra low loss products with carriers and data center operators. Integrators should build verification labs and acceptance services, and software vendors should prioritize open interfaces, because buyers reward suppliers that reduce multivendor risk.
How Strong Is the Investment Attractiveness of the Open All Photonics Network Market?

Investment attractiveness is high but selective. The projected USD 9.08 Billion increase in annual market value between 2026 and 2035 favors software, services and hollow core fiber over mature standard fiber, which grows only 10.5% CAGR. Early investors should favor suppliers with operator references, standards participation and recurring revenue, and should expect uneven order timing until a second major operator commits.

What Are the Market Shifts and Key Risks Facing the Open All Photonics Network Market?

The main shift is the move from telecom operator purchases to cloud and data center buyers, who become the fastest growing buyer group. Key risks include slow multivendor interoperability, concentration of early demand in Japan, integration cost with existing ROADM plant and supply limits for advanced optics. Delays in standards or in second operator commitments would lower near term revenue.

What Are the Primary Growth Pathways Through 2035?

Growth pathways run through data center interconnect, mobile fronthaul over photonic paths, financial services connectivity and submarine extensions. Each pathway needs the same building blocks, which are transceivers, gateways, controllers and low delay fiber. Suppliers that serve several pathways with one platform can spread development cost, while buyers can reuse skills and tools across projects.

Delivered Customizations

We have successfully delivered the following deep-dive customizations:

Client Request Customization Delivered Value Adds
Optical Component Trade Flow Analysis
  • Country-wise import and export analysis of optical transceivers, lasers, and photonic components using HS-coded customs data.
  • Identifies sourcing concentration and tariff exposure across photonic supply chains to support sourcing and localization decisions.
Vendor Technology Revenue Benchmarking
  • Company-level revenue split by optical technology and offering (coherent, DWDM, switching, software) where disclosed in filings.
  • Shows which technology lines are driving vendor growth to guide R&D and portfolio investment.
Historical Network Deployment Market Analysis
  • Historical market revenue and deployment trends by network domain and offering over the past several years.
  • Establishes a validated baseline growth rate to test the 2026–2035 forecast assumptions.
Route-Type Deployment Opportunity Assessment
  • Mapping of terrestrial long-haul, metro, subsea, and access route deployments with capacity and build activity by region.
  • Pinpoints the route corridors with the highest upgrade demand to prioritize targeted go-to-market efforts.
Buyer-Type Open Platform Adoption Analysis
  • Adoption profiling of open optical platforms across telecom operators, hyperscalers, government, and enterprise buyers by offering.
  • Identifies the buyer segments most likely to adopt disaggregated open optical architectures, sharpening customer targeting.
Channel-Led Pricing and Route-to-Market Benchmarking
  • Comparison of direct, distributor, and systems-integrator channel economics and pricing across regions.
  • Guides channel mix and pricing decisions to improve margins and regional reach.

FAQs

About the Author

Mihul Sharma

Mihul Sharma

Mihul Sharma is Research Associate at Next Move Strategy Consulting, where he has covered technology, industrial, and healthcare markets for 3 years. His work applies structured business research, market analysis, and secondary-source review to assess market trends, competitive developments, and growth opportunities. He supports report development by fully synthesizing industry data, company information, and market signals into concise findings for strategy and investment-focused research teams.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Semih Kavaklioglu

SEMIH KAVAKLIOGLU

Co-Founder & Sales Manager

Decortie

I work a lot in the marketing industry and I know that research is an essential part of any campaign. I have used Market research reports for my own products and I found them to be very informative and well-researched. The team here produces insightful reports for a good price

Henri Knyphausen

HENRI KNYPHAUSEN

Partner at Singulier [Ex-BCG]

Singulier

I recently engaged NEXTMSC.com for a commercial due diligence project within the intralogistics sector, and I am pleased to provide a reference based on my experience. In utilizing NEXTMSC.com's services, I found their report to offer valuable insights into market dynamics and key industry players. The initial report provided a solid foundation for our analysis. However, as we were investigating a smaller target in the market, and I had specific customization requests requiring additional research. These requests included detailed information on product portfolios of various players and sub-market sizes, both inclusive and exclusive of certain product categories. NEXTMSC.com demonstrated commendable responsiveness and agility in accommodating these customization requests. Within a timeframe of 1-2 weeks, they delivered a revised report that met our specific needs. Furthermore, they were receptive to my follow-up inquiries, ensuring clarity and understanding of the data provided. The final deliverable significantly contributed to our due diligence efforts. One of NEXTMSC.com's notable strengths lies in their qualitative research capabilities. However, for future engagements, I would recommend the inclusion of a quantified market model in Excel format. Such a model would offer the ability to conduct in-depth analyses and explore various market segments, including country-specific data and subcomponent breakdowns. Based on my positive experience, I would not hesitate to work with NEXTMSC.com again. Their responsiveness, willingness to accommodate customization requests, and commitment to delivering actionable insights make them a reliable partner for commercial research projects.

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Kevin Coker

KEVIN COKER

Founder, CEO and Board Diector

Proxima Clinical Research

I have been using Next MSC reports for product positioning in a new geography for a long time. They have by far the best reports I have found and the price is reasonable too!

Melanie Samko

MELANIE SAMKO

Director of Marketing

TOSOH BIOSCIENCE, INC.

The information provided by NMSC is incredibly valuable, thank you so much for such a excellent work. I really appreciate it. I will make sure to reference all of it, in my summary document.

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖