Hardware Security Module Market Global Industry Analysis and Forecast (2026–2035)

Hardware Security Module Market size was USD 2.48 Billion in 2025, projected to reach USD 8.84 Billion by 2035, growing at a CAGR of 12.3% from 2026 to 2035. Key drivers include post-quantum cryptography migration, the shift to FIPS 140-3 validated modules, and rising payment, cloud, and device key protection demand, with North America leading the market.
Download Free Sample PDF
Base Year (2025)
$3.12 Billion
Forecast (2035)
$8.84 Billion
CAGR (2026-2035)
12.3%
Top Region
North America

What Is the Hardware Security Module Market Size?
The global Hardware Security Module Market reached USD 2.48 Billion in 2025 and is estimated at USD 3.12 Billion in 2026. It is forecast to reach USD 8.84 Billion by 2035 at a CAGR of 12.3% between 2026 and 2035. North America leads with approximately 35% revenue share in 2025, while Standalone HSM holds about 82% of total revenue.
We observed that cryptographic key custody has moved from a niche compliance control to a core infrastructure layer. Banks, cloud providers, and device makers now treat tamper-resistant key storage as a baseline requirement. Post-quantum migration adds a replacement cycle on top of existing demand. Buyers must refresh modules that cannot run new algorithms, and that refresh is arriving alongside new cloud and embedded use cases.

We found that segment leadership is clear on every axis, and the fastest-growing segments differ from the largest ones.

Hardware Security Module Market Global Industry Analysis and Forecast (2026–2035) Revenue Forecast
Values in USD Billion

2025 $2.48 Billion
2025
2026 $3.12 Billion
2026
2027 $3.50 Billion
2027
2028 $3.93 Billion
2028
2029 $4.42 Billion
2029
2030 $4.96 Billion
2030
2031 $5.57 Billion
2031
2032 $6.26 Billion
2032
2033 $7.03 Billion
2033
2034 $7.89 Billion
2034
2035 $8.84 Billion
2035

Key Takeaways

By Form Factor: Standalone HSM held the largest share, expanding from USD 2.03 Billion in 2025 to USD 6.79 Billion by 2035; Embedded HSM Hardware is the fastest-growing at 15.20% CAGR from 2026–2035.

By Application: Payment Cryptography held the largest share, expanding from USD 0.60 Billion in 2025 to USD 1.68 Billion by 2035; Digital Asset Custody is the fastest-growing at 18.91% CAGR from 2026–2035.

By Buyer Type: Own Use End User held the largest share, expanding from USD 1.54 Billion in 2025 to USD 4.74 Billion by 2035; HSM Service Operator is the fastest-growing at 18.07% CAGR from 2026–2035.

By End User Industry: BFSI held the largest share, expanding from USD 0.75 Billion in 2025 to USD 2.23 Billion by 2035; Automotive is the fastest-growing at 16.17% CAGR from 2026–2035.

By Deployment Model: Customer Operated On Premises held the largest share, expanding from USD 1.49 Billion in 2025 to USD 4.41 Billion by 2035; Provider Operated Infrastructure is the fastest-growing at 17.62% CAGR from 2026–2035.

By Route to Market: Direct Manufacturer Sales held the largest share, expanding from USD 0.84 Billion in 2025 to USD 2.59 Billion by 2035; Marketplace and Platform Sales is the fastest-growing at 20.65% CAGR from 2026–2035.

Dominant Region: North America dominated with approximately 35% revenue share in 2025, anchored by federal validation rules and large bank and cloud estates.

Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR of 14.61% during 2026–2035, driven by instant payments and localization policies.

Dominant Country: The U.S. led the market with an estimated USD 0.80 Billion in 2025, supported by federal procurement and hyperscale cloud demand.

Fastest-Growing Country: India is projected to expand from USD 0.07 Billion in 2025 at a CAGR of 17.33%, driven by digital payments and local hosting rules.

This market presents an absolute opportunity of approximately USD 5.72 Billion between 2026 and 2035. That figure is the 2035 forecast of USD 8.84 Billion less the 2026 base of USD 3.12 Billion. Quantum-safe module refresh programs and provider-operated HSM services look like the most capital-efficient categories for investors.

According to NMSC analysis, the move from FIPS 140-2 to FIPS 140-3 validated modules is the most time-bound demand event in the industry. NIST moves every remaining FIPS 140-2 certificate to its Historical list on September 21, 2026. Federal and regulated buyers are therefore expected to specify FIPS 140-3 for new purchases.

Ecosystem Analysis of the Hardware Security Module Industry

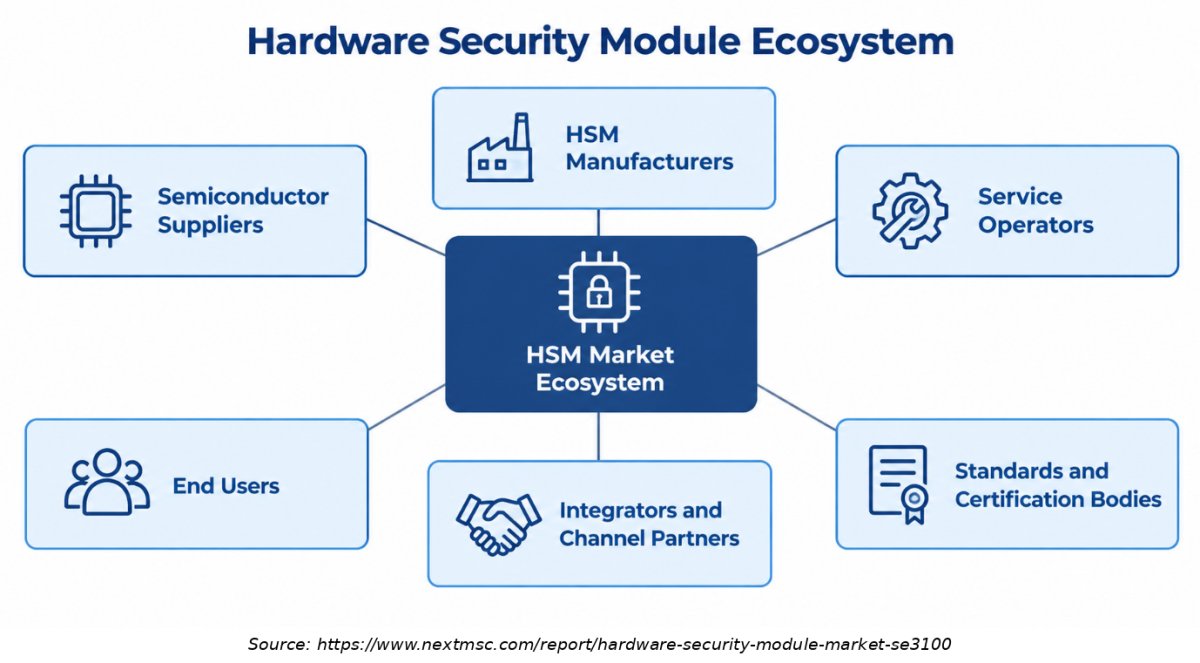
The above infographic presents the Hardware Security Module Market ecosystem in a simpler format, focusing on six core stakeholder groups: semiconductor suppliers, HSM manufacturers, service operators, end users, integrators and channel partners, and standards and certification bodies. It shows how these participants combine to deliver certified key protection, regulatory compliance, performance, and crypto agility across enterprise, payment, and embedded environments.
What does the Hardware Security Module Market Encompass?
The Hardware Security Module Market covers tamper-resistant hardware that generates, stores, and uses cryptographic keys inside a certified security boundary. It includes network appliances, PCIe cards, USB devices, embedded modules, and security silicon that perform HSM functions. Revenue counts the hardware and the firmware bundled with it. The scope excludes pure software key vaults and key management servers that lack a hardware root of trust.
Validation schemes shape almost every purchase decision. FIPS 140-3 under the NIST CMVP, Common Criteria, PCI PTS HSM, and eIDAS qualified signature creation device status act as buying gates for banks, governments, and trust service providers. NIST finalized FIPS 203, FIPS 204, and FIPS 205 in August 2024. Vendors now add ML-KEM, ML-DSA, and SLH-DSA to certified firmware, which makes crypto agility a standard buying criterion.

Market Drivers & Dynamics

Interactive Dataset
Post-quantum migration and crypto agility mandates driver +3.1% Global 2026–2035
FIPS 140-3 transition after FIPS 140-2 certificates move to Historical status driver +2.2% North America, Europe 2026–2029
Payment modernization and instant payment growth driver +1.9% Asia-Pacific, Latin America 2026–2033
Cloud and HSM as a service adoption by enterprises driver +1.7% North America, Europe 2026–2032
Device identity and software signing requirements driver +1.2% Global 2026–2031
Shorter public TLS certificate lifetimes raising signing volumes driver +0.8% Global 2026–2029
High unit cost and long certification timelines restraint −1.4% Global 2026–2035
Substitution by software key vaults and confidential computing restraint −0.9% North America, Europe 2026–2032
Integration complexity and shortage of key management skills restraint −0.7% Latin America, Middle East & Africa 2026–2031
Secure silicon supply constraints and long lead times restraint −0.5% Asia-Pacific, Europe 2026–2028
Source: Next Move Strategy Consulting

Growth Drivers

What Is the Primary Growth Driver in the Hardware Security Module Market?

Post-quantum migration is the primary growth driver. The first three post-quantum standards arrived in August 2024. Its draft IR 8547 proposes deprecating RSA and elliptic curve cryptography after 2030 and disallowing it after 2035. EU member states agreed on a roadmap in June 2025 that asks them to begin transitioning by the end of 2026. Modules that cannot update algorithms face early replacement, which lifts unit demand.

How Is the FIPS 140-3 Transition Driving the Market Growth?

Our analysis shows that validation status now decides eligibility in regulated procurement. CMVP stopped accepting new FIPS 140-2 submissions in September 2021. On September 21, 2026, the last active FIPS 140-2 certificates will become Historical. Historical modules stay usable in existing systems, but new federal acquisitions are expected to specify FIPS 140-3. Thales, Marvell, and Utimaco have obtained FIPS 140-3 validations, while Entrust has submitted nShield 5 firmware with post-quantum algorithms.

Growth Inhibitors

What Is Restraining the Hardware Security Module Market?

The primary restraint is the cost and time of certification, combined with competition from software key vaults. New modules must pass laboratory testing and the CMVP queue, which delays launches and keeps prices high. We found that cost-sensitive buyers in smaller banks and mid-sized enterprises often choose cloud key vaults over owned hardware. This substitution caps growth in lower assurance use cases, while payment, signing, and sovereign workloads still require certified modules.

What Are the Growth Opportunities?

Can Quantum Safe Module Refresh Programs Create a Replacement Wave?

Quantum safe refresh programs give vendors a defined replacement wave. The mechanism is firmware-upgradable platforms, such as Thales Luna 8 and Entrust nShield 5, that let banks and agencies retire modules unable to run ML-KEM and ML-DSA. This opportunity benefits the Network Attached HSM Appliance segment and the BFSI and Government and Defence industries, which hold the largest installed bases.

Can HSM Operators Turn Key Custody Into a Metered Cloud Service?

Service operators can convert key custody into a metered cloud service. The mechanism is PCIe adapters deployed in provider infrastructure, which spread hardware cost across many tenants and bill by the hour. This opportunity benefits the HSM Service Operator buyer type, which grows at 18.07% CAGR, and the Provider Operated Infrastructure deployment model at 17.62%. Enterprises gain certified protection without capital outlay.

Can Digital Asset and Device Identity Workloads Open New Volume Segments?

Digital asset custody and device identity open new volume categories. The mechanism is growing regulatory and supervisory emphasis on safeguarding digital assets and securing connected products, including requirements under the EU’s MiCA framework and the EU Cyber Resilience Act. The U.S. GENIUS Act establishes a payment-stablecoin framework; any direct HSM requirement should be substantiated separately. This opportunity benefits Digital Asset Custody at 18.91% CAGR and IoT and Embedded Device Security at 16.91%. Vendors with blockchain integrations and secure silicon portfolios gain first access.

Segmentation Analysis

2025 (USD Billion)
2035 (USD Billion)
Standalone HSM 2025: $2.03 Billion | 2035: $6.79 Billion
Standalone H
Network Attached HSM Appliance 2025: $1.36 Billion | 2035: $4.36 Billion
Network Atta
PCIe HSM Card and Cryptographic Coprocessor 2025: $0.50 Billion | 2035: $1.98 Billion
PCIe HSM Car
USB and Portable HSM 2025: $0.12 Billion | 2035: $0.33 Billion
USB and Port
Other Standalone HSM Format 2025: $0.05 Billion | 2035: $0.12 Billion
Other Standa
Embedded HSM Hardware 2025: $0.45 Billion | 2035: $2.05 Billion
Embedded HSM
Discrete Embedded HSM Module 2025: $0.20 Billion | 2035: $0.83 Billion
Discrete Emb
HSM-Enabled Security Silicon 2025: $0.25 Billion | 2035: $1.22 Billion
HSM-Enabled
Standalone HSM $2.03 Billion $6.79 Billion 11.51%
Network Attached HSM Appliance $1.36 Billion $4.36 Billion 11.01%
PCIe HSM Card and Cryptographic Coprocessor $0.50 Billion $1.98 Billion 13.51%
USB and Portable HSM $0.12 Billion $0.33 Billion 9.25%
Other Standalone HSM Format $0.05 Billion $0.12 Billion 7.67%
Embedded HSM Hardware $0.45 Billion $2.05 Billion 15.20%
Discrete Embedded HSM Module $0.20 Billion $0.83 Billion 14.07%
HSM-Enabled Security Silicon $0.25 Billion $1.22 Billion 16.03%

Which Form Factor Dominates the Hardware Security Module Market?

Standalone HSM leads with USD 2.03 Billion in 2025, rising to USD 6.79 Billion by 2035. Network Attached HSM Appliance forms the core of that revenue because banks, agencies, and certificate authorities need audited throughput and tamper response. Embedded HSM Hardware is the fastest-growing form factor at 15.20% CAGR from 2026–2035. HSM-Enabled Security Silicon grows at 16.03% as device makers move keys into silicon, while PCIe cards expand at 13.51% on cloud demand.

Supply Chain Analysis of the Hardware Security Module Industry

Supply Chain Analysis of the Hardware Security Module Industry
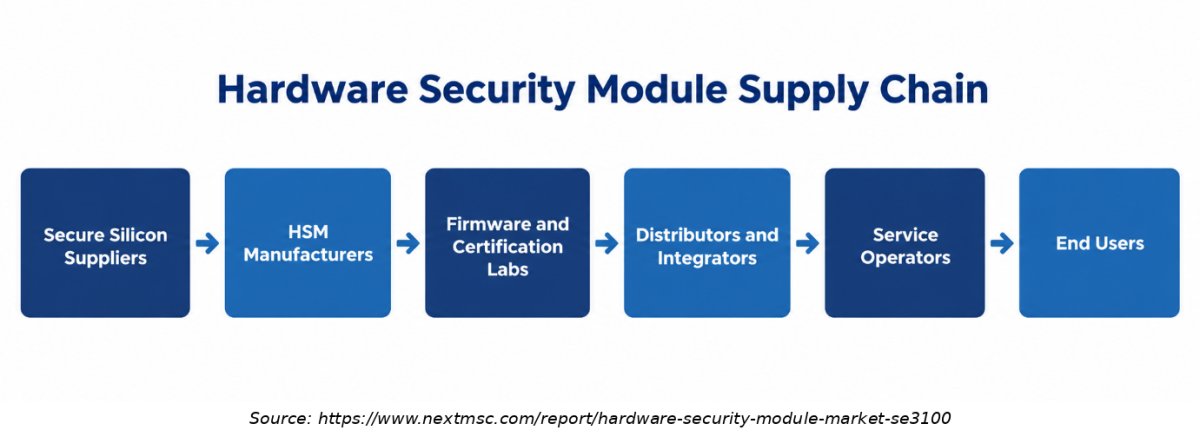
The above infographic maps the Hardware Security Module Market supply chain across secure silicon suppliers, HSM manufacturers, firmware and certification laboratories, distributors and integrators, service operators, and end users. It keeps the structure simple while showing how each stage supports tamper resistance, validated assurance, timely delivery, and lifecycle service for regulated and commercial buyers.
Growth Opportunities

Based on research conducted by NMSC, we found that three opportunities are positioned to generate outsized revenue for vendors that invest ahead of buyer demand.

Can Quantum Safe Module Refresh Programs Create a Replacement Wave?

Quantum safe refresh programs give vendors a defined replacement wave. The mechanism is firmware-upgradable platforms, such as Thales Luna 8 and Entrust nShield 5, that let banks and agencies retire modules unable to run ML-KEM and ML-DSA. This opportunity benefits the Network Attached HSM Appliance segment and the BFSI and Government and Defence industries, which hold the largest installed bases.

Can HSM Operators Turn Key Custody Into a Metered Cloud Service?

Service operators can convert key custody into a metered cloud service. The mechanism is PCIe adapters deployed in provider infrastructure, which spread hardware cost across many tenants and bill by the hour. This opportunity benefits the HSM Service Operator buyer type, which grows at 18.07% CAGR, and the Provider Operated Infrastructure deployment model at 17.62%. Enterprises gain certified protection without capital outlay.

Can Digital Asset and Device Identity Workloads Open New Volume Segments?

Digital asset custody and device identity open new volume categories. The mechanism is growing regulatory and supervisory emphasis on safeguarding digital assets and securing connected products, including requirements under the EU’s MiCA framework and the EU Cyber Resilience Act. The U.S. GENIUS Act establishes a payment-stablecoin framework; any direct HSM requirement should be substantiated separately. This opportunity benefits Digital Asset Custody at 18.91% CAGR and IoT and Embedded Device Security at 16.91%. Vendors with blockchain integrations and secure silicon portfolios gain first access.

Regional Outlook

2025 (USD Billion)
2035 (USD Billion)
North Americ
Europe
Asia-Pacific
Middle East
Latin Americ
Region 2025 (USD Billion) 2035 (USD Billion) CAGR (%)
North America $10.0 USD Billion $40.0 USD Billion 9.0%
Europe $17.1 USD Billion $51.1 USD Billion 27.0%
Asia-Pacific $24.2 USD Billion $62.2 USD Billion 25.0%
Middle East & Africa $31.3 USD Billion $73.3 USD Billion 23.0%
Latin America $38.4 USD Billion $84.4 USD Billion 12.0%

Regional data is locked

Unlock complete regional numbers for this market.

Unlock Full Data

Competitive Landscape

Our findings suggest that competition rewards validated assurance, algorithm agility, and delivery flexibility more than price.

Dimension Description
Market Structure Moderately concentrated. Diversified security groups lead general-purpose and payment HSMs, while specialists and silicon suppliers compete in cloud, embedded, and regional niches.
Innovation Focus Post-quantum firmware, FIPS 140-3 Level 3 validation, PCIe cloud adapters, and unified platforms that serve general-purpose and payment workloads.
M&A Activity Selective. Deals such as Entrust acquiring nCipher and Utimaco acquiring GEOBRIDGE show a preference for adding key management and service capability.

How Do Hardware Security Module Vendors Compete?

Vendors in the Hardware Security Module Market compete on validation status, algorithm support, performance, and ecosystem integrations rather than list price. Certifications such as FIPS 140-3 Level 3, Common Criteria, and PCI PTS HSM decide shortlists. Entrust cites more than 150 partner integrations for nShield, which lowers switching effort for buyers. Geographic expansion follows regulation, as seen in Thales bringing Luna 8 to EMEA and Utimaco opening Indian data centers. Pricing is shifting from one-time appliance sales toward subscriptions and metered cloud usage.
Which Vendor Archetypes Dominate the Hardware Security Module Market?

Five archetypes shape the industry. Diversified security groups such as Thales, Entrust, IBM, and Atos differentiate through breadth and compliance depth. HSM specialists such as Utimaco, Futurex, Securosys, Crypto4A, Kryptus, and DINAMO differentiate through focus and customization. Silicon and cloud suppliers such as Marvell, Infineon, Microchip, Renesas, and STMicroelectronics differentiate through density and cost. Token makers such as Yubico, FEITIAN, Swissbit, and Nitrokey serve portable use cases, and Sansec leads in China.

What Innovation and Differentiation Strategies Define the Market?

Innovation centers on post-quantum readiness and platform consolidation. Utimaco released its Quantum Protect package in April 2025 with a free simulator, and Entrust validated three NIST post-quantum algorithms on nShield in September 2025. Thales built Luna 8 on a new platform that will later support payShield 11K. Marvell differentiates through adapter density, with LiquidSecurity 2 supporting up to 45 partitions for multi-tenant clouds.

What Is the Level of M&A Activity in the Hardware Security Module Market?

M&A activity is selective rather than frequent. Entrust bought nCipher Security to add nShield HSMs to its identity and issuance portfolio. Utimaco acquired GEOBRIDGE to extend into key management and payment services. Thales built its data protection scale through its acquisition of Gemalto in 2019. We observed that buyers seek software, service, and cloud capability around the hardware core, so future deals are likely to target key management and managed HSM platforms.

Key Market Players

Our analysis shows that the following 20 companies define the competitive set for the Hardware Security Module Market.

Thales S.A. Entrust Corporation Utimaco GmbH Futurex LP Marvell Technology, Inc. International Business Machines Corporation Atos SE Securosys SA Sansec Technology Co., Ltd. Crypto4A Technologies Inc. Kryptus Segurança da Informação S.A. DINAMO Networks Tecnologia Ltda. FEITIAN Technologies Co., Ltd. Yubico AB Swissbit AG Nitrokey GmbH Microchip Technology Incorporated Infineon Technologies AG Renesas Electronics Corporation STMicroelectronics N.V.

Latest Developments

We observed that recent announcements cluster around post-quantum validation, cloud delivery, and certification deadlines.

Date Event
September 2026 Thales launches a UK-hosted Luna Cloud HSM service to help customers meet data residency needs.
August 2026 Thales launches Luna 8, the first next-generation HSM on its new platform, delivered as a network appliance with post-quantum support.
December 2025 Marvell and Microsoft expand LiquidSecurity-powered Azure key services in Europe after eIDAS and Common Criteria EAL4+ certifications.
October 2025 Utimaco announces that its LMS, ML-KEM, and ML-DSA implementations passed NIST CAVP testing.

Investment Opportunities

Where Is Capital Flowing in the Hardware Security Module Market?

Capital in the Hardware Security Module Market is flowing toward cloud-delivered HSM capacity, post-quantum firmware, and secure silicon. Microsoft's selection of Marvell adapters for Azure Cloud HSM and Utimaco's new Indian data centers show investment moving into service infrastructure. We found that vendors fund validation work early because FIPS 140-3 and Common Criteria status unlocks regulated tenders. Investors should weigh HSM Service Operator and Embedded HSM Hardware, which grow at 18.07% and 15.20% CAGR.
How Is Infrastructure Investment Shaping Hardware Security Module Demand?

Infrastructure investment follows data residency rules. Operators build in-country data centers to host customer-controlled keys, as Thales did with its UK-hosted service and Utimaco did in India. Each facility needs clustered modules, backup devices, and remote administration tools. Our findings suggest that this build-out lifts demand for network appliances and for PCIe cards, which grow at a 13.51% CAGR. Hyperscale operators add volume orders that favor adapter-based designs.

What ESG Considerations Matter for Hardware Security Module Investors?

Governance and security dominate ESG relevance. HSMs protect customer data, payments, and identity, which supports the governance pillar for regulated buyers. On the environmental side, dense PCIe adapters can replace several 1U or 2U appliances, which reduces rack space and power use. Investors should also review responsible sourcing and secure disposal, because retired tamper-resistant modules must be destroyed or zeroized to protect stored keys.

Key Benefits for Stakeholders

How Does This Report Help Enterprise and Industry Leaders?

Enterprise leaders gain a segment-level view of the Hardware Security Module Market and where certified key protection is growing fastest. The analysis separates Standalone HSM at 11.51% CAGR from Embedded HSM Hardware at 15.20%. It also shows how deployment models and sales routes differ. Security and procurement teams can use these forecasts to time refresh budgets against the FIPS 140-2 sunset and national post-quantum deadlines.
What Value Does This Report Offer Investors and Financial Analysts?

Investors receive reconciled forecasts that tie USD 3.12 Billion in 2026 to USD 8.84 Billion by 2035 across six segmentation axes and five regions. The report highlights faster-growing pockets such as Digital Asset Custody and Provider-Operated Infrastructure. It also profiles 20 companies and recent developments. Analysts can use these inputs to compare vendor exposure to regulated demand, cloud adoption, and embedded growth.

How Can Technology Vendors and Product Teams Use This Report?

Vendors can map product roadmaps to the buying gates described in the analysis, including FIPS 140-3, Common Criteria, PCI PTS HSM, and eIDAS status. The competitive section shows how peers position on post-quantum firmware, cloud delivery, and platform consolidation. Product teams can identify underserved channels, such as marketplace sales, and prioritize integrations that reduce switching effort for enterprise buyers.

Key Market Segments Evaluated

By Form Factor

  • Standalone HSM 
    • Network Attached HSM Appliance
    • PCIe HSM Card and Cryptographic Coprocessor
    • USB and Portable HSM
    • Other Standalone HSM Format
  • Embedded HSM Hardware 
    • Discrete Embedded HSM Module
    • HSM-Enabled Security Silicon

By Application

  • Payment Cryptography
  • PKI and Certificate Services
  • Data Encryption and Key Management
  • TLS and Network Cryptography
  • Code and Firmware Signing
  • Digital Asset Custody
  • Telecom Subscriber Authentication
  • IoT and Embedded Device Security
  • Other HSM Workloads

By Buyer Type

  • Own Use End User
  • HSM Service Operator
  • OEM and Device Manufacturer
  • Channel Intermediary
  • Other Direct Buyer

By End User Industry

  • BFSI
  • Government and Defence
  • IT and Cloud Services
  • Telecommunications
  • Healthcare and Life Sciences
  • Retail and E-Commerce
  • Automotive
  • Industrial and Manufacturing
  • Energy and Utilities
  • Digital Trust and Identity Services
  • Other Industries

By Deployment Model

  • Customer Operated On Premises
  • Customer Owned and Third Party Hosted
  • Provider Operated Infrastructure
  • OEM Embedded Deployment
  • Other Physical Deployment Model

By Route to Market

  • Direct Manufacturer Sales
  • Direct OEM Sales
  • Distributor-Led Sales
  • VAR and Reseller Sales
  • Systems Integrator-Led Sales
  • Marketplace and Platform Sales
  • Other Documented Channels

By Region

  • North America 
    • U.S.
    • Canada
    • Mexico
  • Europe 
    • UK
    • Germany
    • France
    • Italy
    • Spain
    • Sweden
    • Denmark
    • Finland
    • Netherlands
    • Rest of Europe
  • Asia-Pacific 
    • China
    • India
    • Japan
    • South Korea
    • Taiwan
    • Indonesia
    • Vietnam
    • Australia
    • Philippines
    • Malaysia
    • Rest of APAC
  • Middle East & Africa 
    • Saudi Arabia
    • UAE
    • Egypt
    • Israel
    • Turkey
    • Nigeria
    • South Africa
    • Rest of MEA
  • Latin America 
    • Brazil
    • Argentina
    • Chile
    • Colombia
    • Rest of LATAM

Conclusion & Recommendations

The outlook is one of steady, compliance-backed expansion. Revenue rises from USD 2.48 Billion in 2025 to USD 3.12 Billion in 2026 and USD 8.84 Billion by 2035. Growth of 12.3% a year from 2026 is supported by the retirement of quantum-vulnerable algorithms and the end of FIPS 140-2 as an active standard. Embedded and cloud-delivered modules lift growth above the core appliance base.

What Strategic Positioning Recommendations Does NMSC Offer?

Vendors in the Hardware Security Module Market should lead with upgradable platforms that carry FIPS 140-3 Level 3 and post-quantum algorithm validation. They should pair appliances with metered cloud services and local hosting options. Channel partners should prepare migration offers for installed FIPS 140-2 estates. Silicon suppliers should secure automotive and industrial design wins now, because key provisioning relationships tend to last for the life of a platform.

What Does Investment Attractiveness Look Like for the Hardware Security Module Market?

Investment attractiveness is strongest where regulation creates dated demand and recurring revenue. The market adds USD 5.72 Billion between 2026 and 2035. HSM Service Operator revenue grows at 18.07% CAGR, and Digital Asset Custody grows at 18.91%. Risks include certification delays, which postpone launches, and software key vaults, which can absorb lower assurance workloads.

What Are the Market Shifts and Key Risks in the Hardware Security Module Market?

Three shifts stand out: buyers are moving from owned appliances toward provider-operated capacity, from classical to hybrid algorithms, and from standalone devices toward embedded silicon. Key risks include long CMVP queues, uncertainty over final timelines in draft guidance such as IR 8547, and the pace at which cryptographically relevant quantum computers arrive. Vendors that stay crypto-agile can manage all three risks.

What Are the Primary Growth Pathways Through 2035?

Four pathways drive growth in the Hardware Security Module Market. First, quantum-safe replacement cycles in BFSI and government. Second, cloud and sovereign HSM services. Third, device identity in vehicles, meters, and factories. Fourth, digital asset and trust service workloads. Asia-Pacific, at 14.61% CAGR, offers the fastest regional expansion, while North America remains the largest base at USD 2.70 Billion by 2035.

FAQs

Sources & References

1.

NIST, FIPS 203 Module Lattice Based Key Encapsulation Standard

csrc.nist.gov/pubs/fips/203/final
2.

NIST, FIPS 204 Module Lattice Based Digital Signature Standard

csrc.nist.gov/pubs/fips/204/final
3.

NIST, FIPS 205 Stateless Hash Based Digital Signature Standard

csrc.nist.gov/pubs/fips/205/final
4.

NIST, IR 8547 Transition to Post Quantum Cryptography Standards (initial public draft)

csrc.nist.gov/pubs/ir/8547/ipd
5.

NIST, Cryptographic Module Validation Program

csrc.nist.gov
6.

European Commission, Coordinated Implementation Roadmap for the Transition to Post Quantum Cryptography

digital-strategy.ec.europa.eu
7.

European Commission, Post Quantum Cryptography policy page

digital-strategy.ec.europa.eu
8.

EUR-Lex, Regulation (EU) 2022/2554 (DORA)

eur-lex.europa.eu
9.

EUR-Lex, Regulation (EU) 2024/1183 (eIDAS 2.0)

eur-lex.europa.eu
10.

EUR-Lex, Regulation (EU) 2024/2847 (Cyber Resilience Act)

eur-lex.europa.eu
11.

EUR-Lex, Regulation (EU) 2023/1114 (MiCA)

eur-lex.europa.eu
12.

Thales, Luna 8 news release (August 4, 2026)

cpl.thalesgroup.com
13.

Thales, UK hosted Cloud HSM news release (September 14, 2026)

cpl.thalesgroup.com
14.

Thales, 2026 Data Threat Report

cpl.thalesgroup.com/data-threat-report
15.

Entrust, nShield HSM post-quantum algorithm validation release (September 10, 2025)

businesswire.com
16.

Entrust, nShield HSM product page

entrust.com/products/hsm
17.

Utimaco, Quantum Protect algorithms pass NIST testing (October 14, 2025)

utimaco.com
18.

Marvell, expanded Microsoft Azure collaboration in Europe (December 1, 2025)

marvell.com
19.

Marvell, LiquidSecurity selected for Microsoft Azure Cloud HSM (August 18, 2025)

jp.marvell.com
20.

Futurex, VirtuCrypt Cloud HSM

futurex.com/virtucrypt
21.

UK National Cyber Security Centre

ncsc.gov.uk
22.

Canadian Centre for Cyber Security

cyber.gc.ca
23.

Australian Signals Directorate, Cyber Security

cyber.gov.au
24.

The White House, National Security Memorandum 10

whitehouse.gov
25.

PCI Security Standards Council

pcisecuritystandards.org
26.

CA/Browser Forum

cabforum.org
27.

Banco Central do Brasil

bcb.gov.br
28.

Reserve Bank of India

rbi.org.in

About the Author

Mayurima Roy

Mayurima Roy

Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.

About the Reviewer

Supradip Baul

Supradip Baul

Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.

Download Free Sample

Ross J Mckenzie

ROSS J MCKENZIE

Business Insight Manager

Staysure Group

“Next MSC have been incredibly helpful in providing detailed & robust information on our market, alongside quantifying growth by different segments. The process to procure was simple and easy, with sample reports and regular contact to ensure we had what we needed. Succinct detail on their sources & methodologies is also greatly received, allowing transparency in this respect helps build trust in the detail you pay for. Joseph in particular was fantastic, and helped ensure efficient provision of the insight pack – thank you NMSC!”.

Pratyush Kumar Das

PRATYUSH KUMAR DAS

Assistant Manager

Polycab India Limited

We would like to express our appreciation for the data and insights provided by nextmsc. We are very pleased with the quality and depth of the information, which has proven to be highly valuable and beneficial for our business decision-making.

Mohit Agarwal

MOHIT AGARWAL

Chief Manager

DryChem India Pvt. Ltd.

Next Move Strategy Consulting is an amazing team of consultants. We required a market study report for our investors on top priority and the team went above and beyond our expectations to deliver the same with ample supporting data within a short time span enabling us to secure the investments and keep our project timeline maintained. Their professionalism, attention to detail, and timely delivery of actionable recommendations have left a lasting impression on our organization.

Rishabh Jogani

RISHABH JOGANI

Strategy Analyst

Accenture Japan

We are incredibly impressed with the market report on the real estate market in India provided by Next Move Strategy Consulting. The report was thorough, insightful, and well-structured, offering deep analysis and actionable recommendations. It not only captured the current trends and dynamics but also provided a forward-looking perspective that has been invaluable for our strategic planning. Their team demonstrated exceptional professionalism, attention to detail, and a profound understanding of the industry. The data-driven insights and clarity of presentation exceeded our expectations, making complex market trends easy to understand. We highly recommend Next Move Strategy Consulting to anyone looking for reliable and comprehensive market research services. Their expertise has given us the confidence to navigate the complexities of the Indian real estate market with clarity and foresight.

Robert Sean Trevino

ROBERT SEAN TREVINO

Sr. Director, Head of Strategic Insights & Analytics

Foundation Medicine

I realized that it was a reliable source of information. These days, there are many people who are looking for authentic data, and this is one of the only sources that can offer them with what they need;

Custom Market Research Services

We will customize the research for you if the listed report does not fully match your requirements.

Get 30% Free Customization

Select License

This website uses cookies to ensure you get the best experience on our website. Learn more

✖