Taiwan Fabric Care Market Size, By Product Type {Fabric Detergents (General Purpose, Baby Laundry Detergent, and Delicate Laundry Detergent), Fabric Softeners/Conditioners, and Others}, By Form (Liquid, Powder, Unit-Dose, Sheet & Wipe, and Spray), By Nature (Conventional and Eco-friendly / Organic), By Price Tier (Value, Mid-range, and Premium), By Distribution Channel (Online and Offline), and By End-User (Residential, Commercial, and Others) – Analysis & Forecast, 2025–2035
Industry: Retail and Consumer | Latest Edition: August 17, 2026 | No of Pages: 152 | No. of Tables: 49 | No. of Figures: 43 | Format: PDF | Report Code: RC4574
Taiwan Fabric Care Market Size & Forecast
|
Parameters |
Details |
|
Market Size in 2025 |
USD 6.38 Billion |
|
Market Size in 2026 |
USD 7.27 Billion |
|
Revenue Forecast in 2035 |
USD 11.56 Billion |
|
Growth Rate |
CAGR of 5.29% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Billion (USD) |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 companies |
Industry Outlook
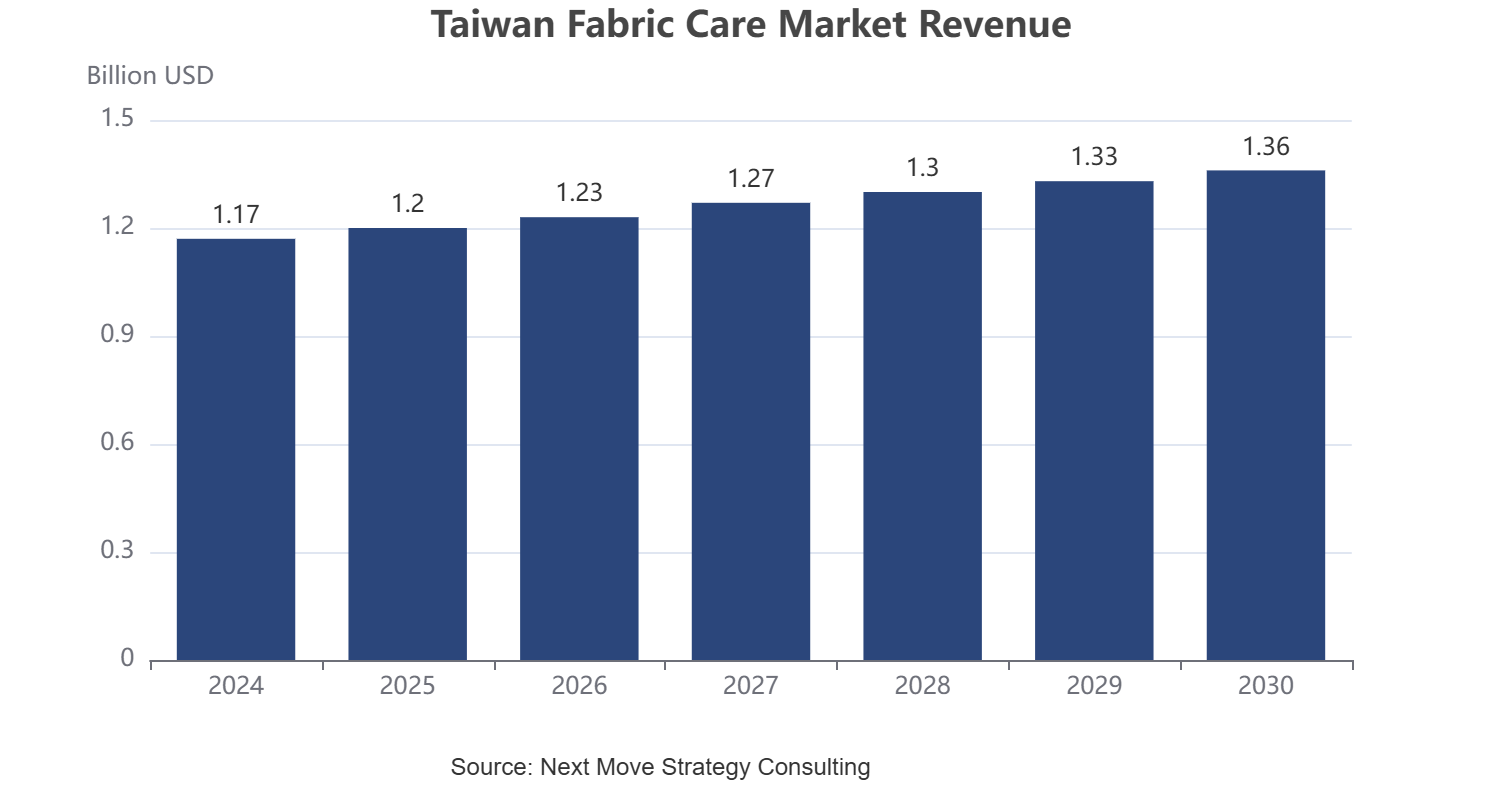
The Taiwan fabric care market was valued at USD 6.38 billion in 2025 and is estimated to reach USD 7.27 billion in 2026, supported by a mature but value-resilient category where consumers continue trading up despite limited volume growth. Between 2026 and 2035, the market is forecast to expand to USD 11.56 billion, registering a CAGR of 5.29%. Growth continues to be reinforced by premiumization toward concentrated liquid formats, water-efficiency concerns following past supply constraints, and the continued dominance of trusted imported detergent brands.
Ecosystem Analysis of the Taiwan Fabric Care Market
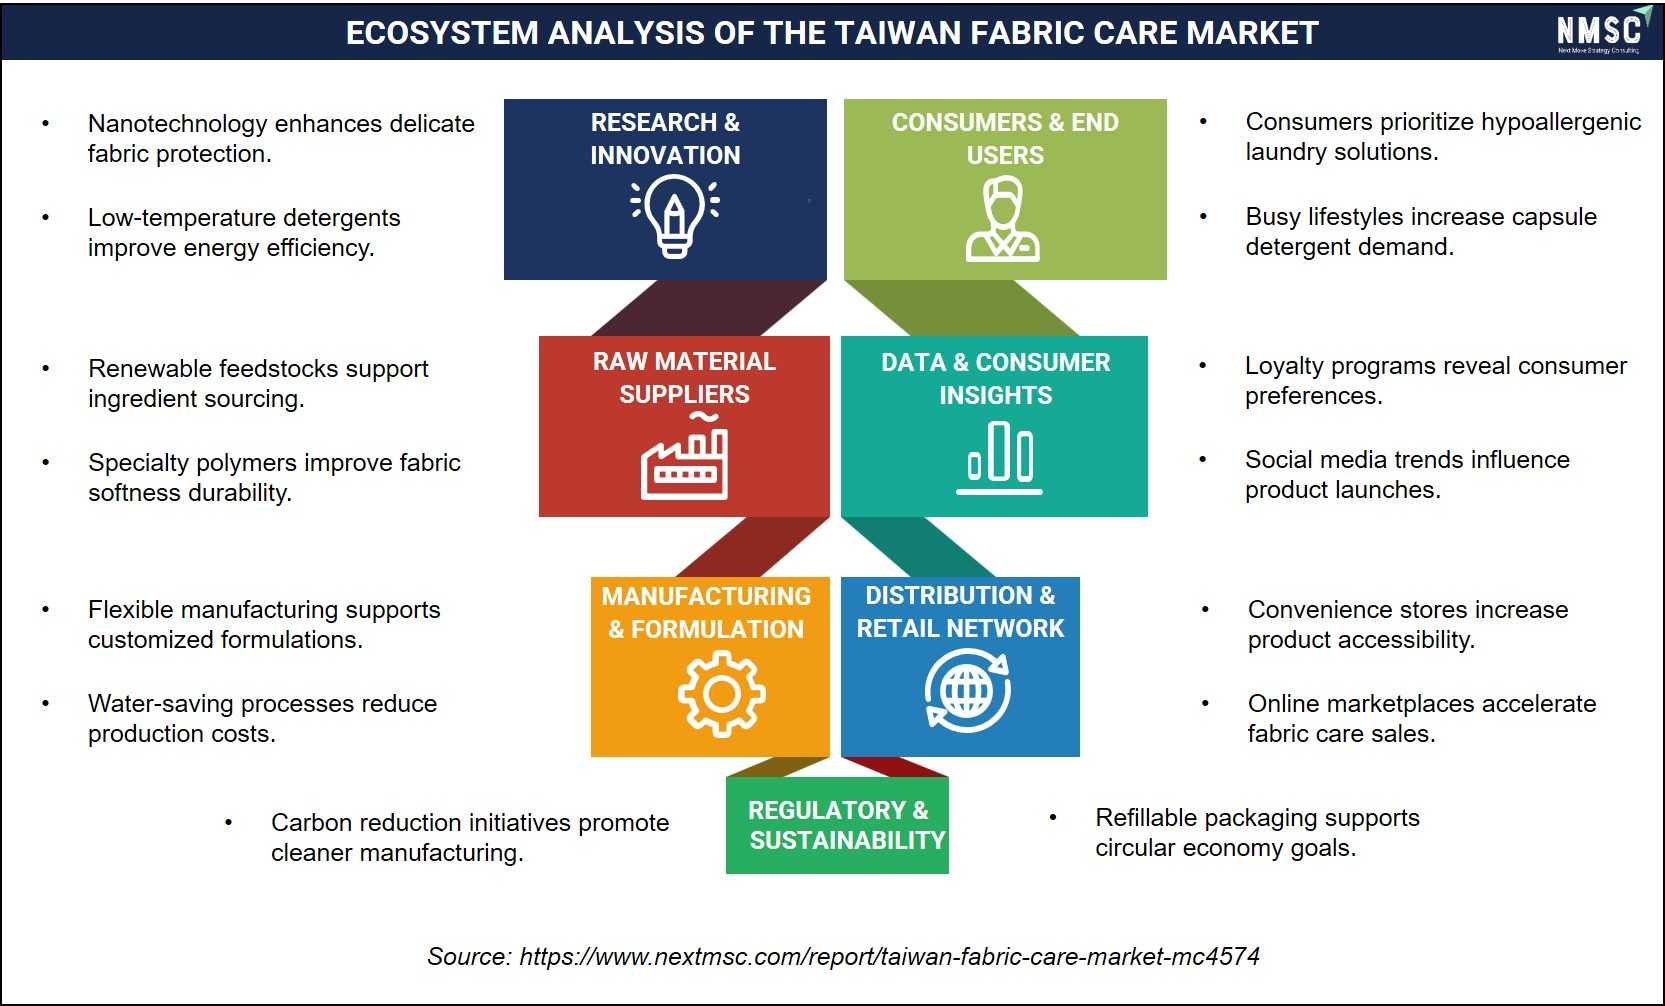
The above ecosystem analysis maps the key operational components, such as research and innovation, raw material suppliers, manufacturing and formulation, regulatory and sustainability, distribution and retail network, data and consumer insights, and consumers and end users, shaping the Taiwan fabric care industry. From our analysis, we observed that nanotechnology enhances delicate fabric protection, while low-temperature detergents improve energy efficiency. Renewable feedstocks and specialty polymers support ingredient sourcing and fabric durability. Consumers prioritize hypoallergenic solutions, busy lifestyles increase capsule detergent demand, and refillable packaging supports circular economy goals across the market ecosystem.
What Are the Key Drivers, Restraints, and Opportunities Shaping the Taiwan Fabric Care Market?
Growth Catalyst & Risk Assessment Matrix
|
Drivers / Restraints / Opportunities |
(+/-) % Impact on CAGR Forecast |
Geographic Relevance |
Impact Timeline |
|
Continued consumer trust in imported Japanese and Western detergent brands |
+1.4% |
Taipei, Taichung, Kaohsiung |
Long term (5–8 years) |
|
Shift toward concentrated liquid detergents amid water scarcity concerns |
+1.6% |
Nationwide, most acute in central and southern Taiwan |
Medium to long term (4–7 years) |
|
Rising e-commerce and subscription-based auto-reorder adoption |
+1.0% |
Urban Taiwan, led by Taipei metro |
Medium term (3–6 years) |
|
Low retail volume growth in a saturated, mature category |
−0.9% |
Nationwide |
Short to medium term (1–4 years) |
|
Consumption polarization creating premium and value sub-segments |
+1.1% |
Taipei and Kaohsiung metro areas |
Medium term (3–6 years) |
The Taiwan fabric care industry reflects a mature, low-volume-growth category in which value expansion is driven almost entirely by premiumization and format upgrading rather than new household formation. Long-standing consumer trust in imported Japanese and Western brands continues to shape competitive dynamics, while water scarcity concerns since the 2021 supply crisis have accelerated demand for concentrated, resource-efficient formulations. Consumption polarization between value and premium tiers is creating distinct opportunities for manufacturers positioned at either end of the category through 2035.
Growth Drivers
How Does Consumer Trust in Imported Brands Sustain Value Growth in Taiwan's Fabric Care Market?
Taiwanese consumers have long favored imported detergent brands such as Attack, Ariel, and Persil over local alternatives, valuing their exclusive laundry technology, long-term trust, and continuous product innovation sourced from Japan and other established markets. This brand loyalty allows imported products to command premium pricing even in a mature, slow-volume-growth category, sustaining steady value growth as manufacturers continue introducing new formulations and marketing campaigns to reinforce their position.
How Is Water Scarcity Driving Demand for Concentrated Detergents in Taiwan?
Taiwan's water insufficiency crisis since 2021 has heightened consumer and manufacturer attention to water-efficient laundry products, accelerating demand for concentrated liquid detergents that require smaller doses and less rinsing. Manufacturers are proactively marketing exclusive value-added formulations that reduce water and energy use per wash cycle, particularly in central and southern regions most affected by resource constraints, reinforcing a structural shift toward concentrated and low-suds product formats.
How Is E-Commerce Adoption Supporting Fabric Care Sales Growth in Taiwan?
Online retail is gaining steady traction in Taiwan's fabric care category, supported by subscription and auto-reorder models that appeal to convenience-seeking urban households in Taipei and other major cities. While offline retail remains dominant given the category's mature, low-volume nature, e-commerce provides both imported brands and local manufacturers a channel to reach digitally engaged consumers directly and offer promotional bundles that support incremental value growth.
Growth Inhibitor
What Factors Are Restraining Volume Growth in Taiwan's Fabric Care Market?
Taiwan's fabric care category is highly mature, with retail volume growth expected to remain low throughout the forecast period even as value growth continues at a steadier pace. Most product categories are seeing value gains except bar detergents, as consumers have gradually shifted away from this format over time. Intense competition, particularly in concentrated liquid detergents, has prompted manufacturers to compete increasingly on value-added features rather than price, compressing volume-driven growth opportunities.
Growth Opportunity
What Opportunities Does Consumption Polarization Offer Taiwan's Fabric Care Manufacturers?
Consumption polarization in Taiwan is creating clearer separation between value-tier and premium-tier fabric care demand, allowing manufacturers to target distinct consumer segments with tailored product strategies. Premium positioning built around water efficiency, imported technology, and specialty formulations for delicate or athletic fabrics offers a path to margin expansion, while value-tier players can capture cost-conscious households through simplified, affordable core detergent lines across supermarket and hypermarket channels.
How Is the Taiwan Fabric Care Market Segmented in This Report, and What Are the Key Insights?
By Distribution Channel Insights
How Does Distribution Channel Segmentation Reflect Evolving Consumer Purchase Behavior?
Based on distribution channel, the Taiwan Fabric Care Market is segmented into online and offline.
The market reflects a balanced retail ecosystem where traditional and digital channels collectively shape fabric care purchasing behavior. According to our analysis, we found that offline channels continue to provide convenient access to a wide range of products through supermarkets, hypermarkets, and department stores, supporting routine household purchases. Meanwhile, online channels are expanding steadily, with marketplaces, brand e-commerce platforms, and quick commerce services offering greater product variety, promotional benefits, and faster delivery, encouraging manufacturers to strengthen omnichannel retail strategies and direct consumer engagement.
By End-User Insights
How Does End-User Segmentation Reflect Fabric Care Consumption Patterns?
Based on end-user, the Taiwan Fabric Care Market is segmented into residential, commercial, and others.
The market demonstrates diverse consumption patterns, with demand varying across household and institutional laundry applications. According to our analysis, we found that residential end-users support consistent demand through routine home laundering and regular product replenishment, while commercial end-users, including hotels, healthcare facilities, laundries, restaurants, and other institutions, require high-performance and bulk fabric care solutions for large-scale operations. The other end-user segment addresses specialized cleaning requirements, encouraging manufacturers to develop tailored product portfolios that meet the evolving needs of diverse customer groups.
Supply Chain Structure of the Taiwan Fabric Care Market
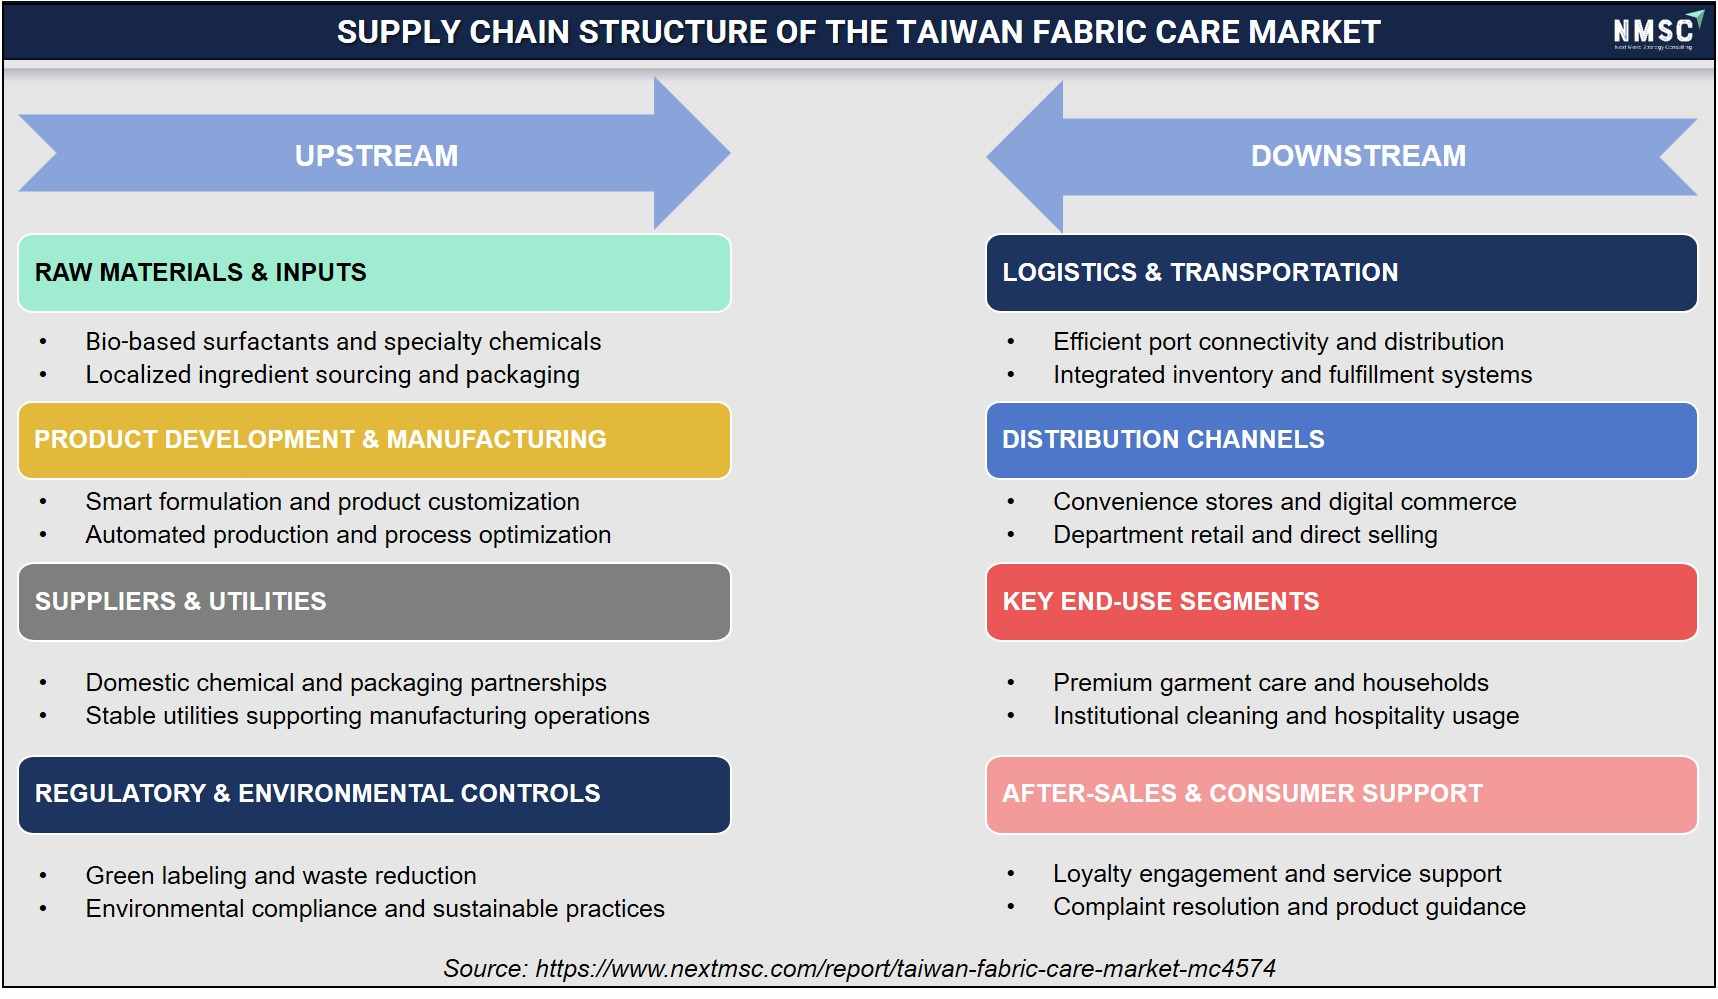
The above supply chain analysis maps the key operational stages, such as upstream and downstream, shaping the Taiwan fabric care industry. From our analysis, we observed that upstream activities include bio-based surfactants, localized ingredient sourcing, smart formulation, automated production, and domestic chemical partnerships, along with green labeling and environmental compliance. Downstream activities encompass efficient port connectivity, convenience stores, digital commerce, departmental retail, premium garment care, household usage, institutional cleaning, and loyalty engagement, reflecting a well-integrated supply chain across the market.
Key Segments
By Product Type
-
Fabric Detergents
-
General Purpose
-
Baby Laundry Detergent
-
Delicate Laundry Detergent
-
-
Fabric Softeners/Conditioners
-
Stain Removers/Bleach
-
Sanitizer
-
Other Products
By Form
-
Liquid
-
Powder
-
Unit-Dose
-
Pods
-
Sachets
-
-
Sheet & Wipe
-
Spray
By Nature
-
Conventional
-
Eco-friendly / Organic
By Price Tier
-
Value
-
Mid-range
-
Premium
By Distribution Channel
-
Online
-
Marketplaces
-
Brand E-com
-
Quick Commerce
-
-
Offline
-
Supermarkets
-
Hypermarkets
-
Department Stores
-
By End-User
-
Residential
-
Commercial
-
Others
Competitive Landscape
The competitive landscape of the Taiwan fabric care industry is defined by the continued leadership of multinational and imported brands over local manufacturers, reflecting decades of established consumer trust and consistent product innovation. Competitive intensity is concentrated in the concentrated liquid detergent segment, where manufacturers differentiate through water-efficiency claims and value-added formulations rather than price alone. Local players compete primarily in value-tier and niche specialty segments, seeking differentiation where multinational brand dominance is comparatively weaker.
Key Players of the Taiwan Fabric Care Market
-
Reckitt Benckiser Taiwan Ltd.
-
Kao Taiwan Corporation
-
SC Johnson Taiwan Ltd.
-
Diversey Taiwan Ltd.
-
Lion Taiwan Co., Ltd.
-
Colgate-Palmolive Taiwan Co., Ltd.
-
Wipro Unza Taiwan Co., Ltd.
-
Patanjali Ayurved Limited
-
Amway Taiwan Company Limited
-
Nice Enterprise Co., Ltd.
-
Mao Bao Inc.
-
Sanxinjia Co., Ltd.
-
Henkel Taiwan Ltd.
Key players shaping the Taiwan fabric care market include Procter & Gamble Taiwan Ltd., Reckitt Benckiser Taiwan Ltd., Unilever Taiwan Ltd., and Kao Taiwan Corporation, alongside manufacturers such as Lion Taiwan Co., Ltd., SC Johnson Taiwan Ltd., and Henkel Taiwan Ltd., and others, all of which compete through imported technology positioning, water-efficient formulation innovation, and distribution depth across Taiwan's modern retail and e-commerce channels.
Key Benefits for Stakeholders
Next Move Strategy Consulting (NMSC) presents a comprehensive analysis of the Taiwan fabric care market, covering the base year 2025 through the forecast period ending 2035. The study examines the market at the country level, providing quantitative projections and insights into key growth drivers, restraints, and opportunities across all major fabric care segments, including product type, form, nature, price tier, distribution channel, and end-user.
Investors and manufacturers benefit from visibility into a mature, value-resilient market where premiumization and water-efficient innovation drive margin expansion despite limited volume growth. Retailers, distributors, and new entrants gain strategic clarity through detailed segmentation and competitive profiling, supporting decisions on market entry, product positioning, and channel investment across Taiwan's established offline and growing digital retail landscape.
|
Parameters |
Details |
|
Customization Scope |
Free customization (equivalent to up to 80 analyst-working hours) after purchase. |
|
Pricing and Purchase Options |
Avail customized purchase options to meet your exact research needs. |
|
Approach |
In-depth primary and secondary research; proprietary databases; rigorous quality control and validation measures. |
|
Analytical Tools |
Porter's Five Forces, SWOT, value chain, and Harvey ball analysis to assess competitive intensity, stakeholder roles, and relative impact of key factors. |
Conclusion
The Taiwan fabric care industry presents a mature, value-led growth trajectory, supported by continued consumer trust in imported brands, water-efficiency-driven premiumization, and rising e-commerce adoption. With revenue projected to grow from USD 7.27 billion in 2026 to USD 11.56 billion by 2035 at a CAGR of 5.29%, the market offers steady opportunities for manufacturers able to serve both value and premium consumption tiers through concentrated, resource-efficient formulations, amid a competitive landscape led by long-established multinational brands.
About the Author
 Mayurima Roy
— Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

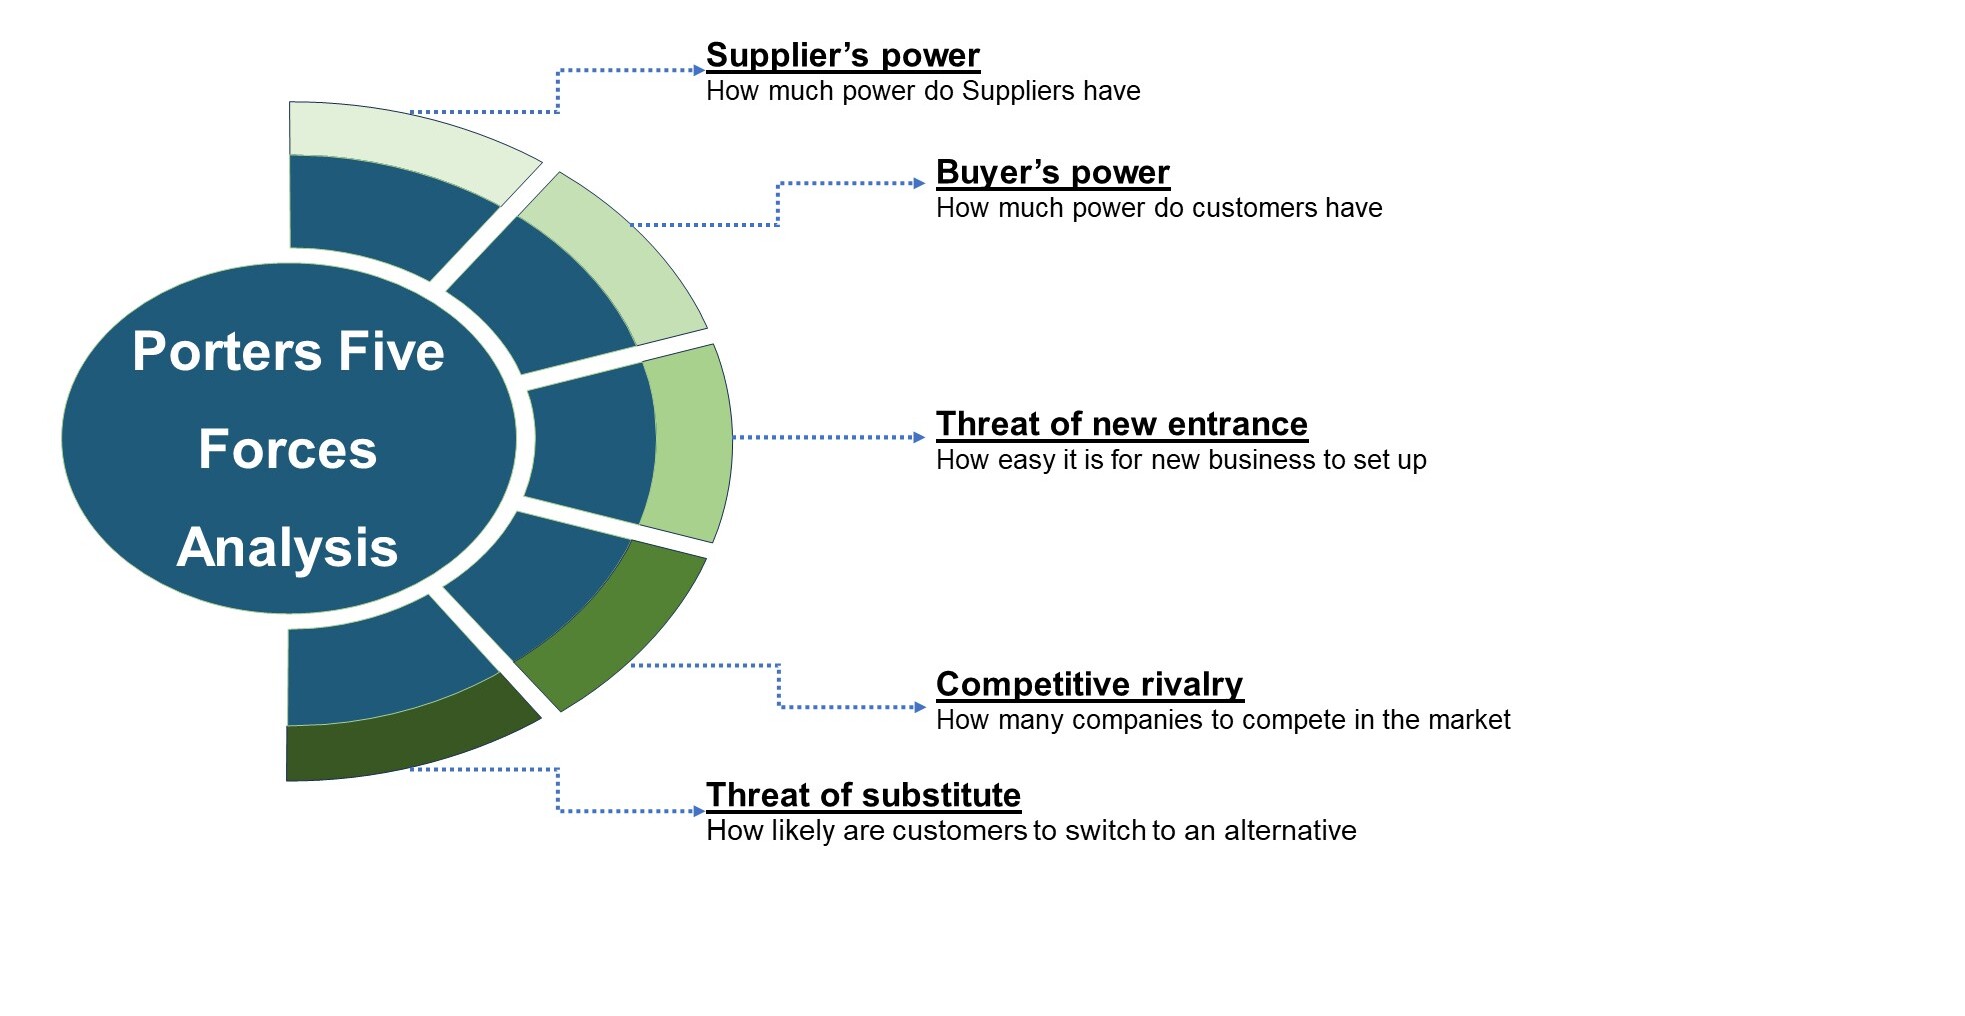
Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.




 Speak to Our Analyst