Asia-Pacific Autonomous Mobile Robot (AMR) Market By Product Type (Autonomous Transport Robots, Autonomous Picking Robots, & Others), By Navigation Technology (LiDAR, Vision Navigation, & Others), By Payload Capacity (<100 KG, 100–1000 KG, & Others), By Deployment Environment (Indoor & Outdoor), By Commercial Model (Direct Sales, System Integrator Sales, & Others), By End-User Industry (Warehousing and Distribution, Manufacturing, & Others) – Opportunity Analysis & Forecast, 2025–2035
Industry: Semiconductor & Electronics | Latest Edition: September 28, 2026 | No of Pages: 1208 | No. of Tables: 615 | No. of Figures: 600 | Format: PDF | Report Code: SE4273
What Is the Asia-Pacific Autonomous Mobile Robot (AMR) Market Size?
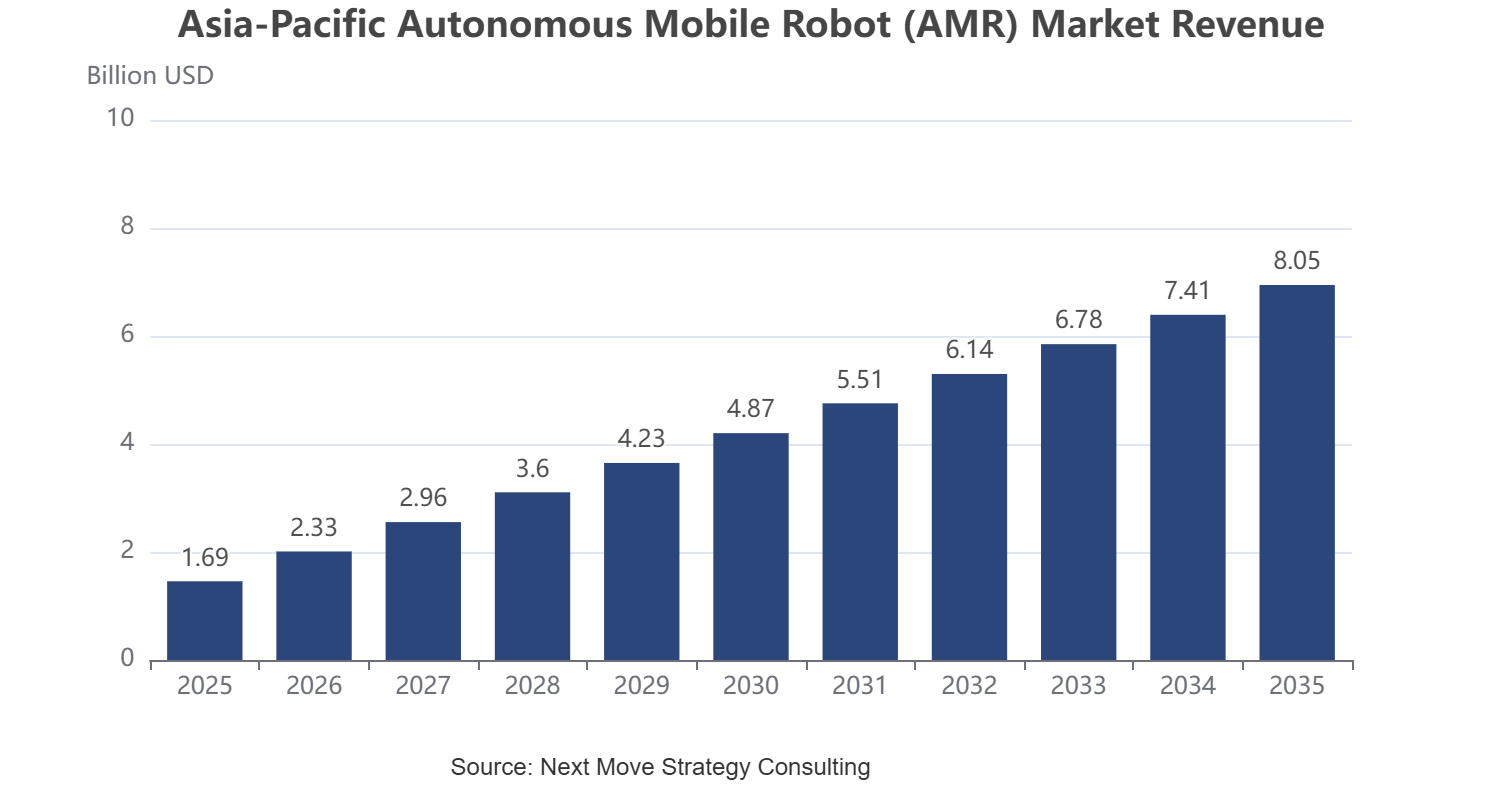
The Asia-Pacific Autonomous Mobile Robot (AMR) Market size was valued at USD 1.69 billion in 2025 and is estimated at USD 2.07 billion in 2026, forecast to reach USD 8.05 billion by 2035, expanding at a 16.26% CAGR between 2026 and 2035. Autonomous Transport Robots dominate the market by product type. In terms of volume, the Asia-Pacific AMR market recorded 46 thousand units in 2025, with forecasts indicating growth to 70 thousand units by 2026 and further to 371 thousand units by 2035, reflecting a CAGR of 20.44% over the forecast period.
We observed that market growth is supported by rapid warehouse and factory automation, rising labor costs across manufacturing hubs, and continuous innovation in navigation, fleet management, and artificial intelligence (AI) chip integration through 2035.
|
Key Takeaways |
|
By Product Type: Autonomous Transport Robots is the dominant segment, while Autonomous Mobile Manipulators is the fastest-growing segment. |
|
By Navigation Technology: LiDAR is the dominant segment, while Sensor Fusion Navigation is the fastest-growing segment. |
|
By Payload Capacity: 100 Kgs to 1000 Kgs is the dominant segment, while 1001 Kgs to 5000 Kgs is the fastest-growing segment. |
|
By Deployment Environment: Indoor Autonomous Mobile Robots is the dominant segment, while Outdoor Autonomous Mobile Robots is the fastest-growing segment. |
|
By Commercial Model: Direct Sales is the dominant segment, while Robotics as a Service is the fastest-growing segment. |
|
By Revenue Stream: Robot Hardware is the dominant segment, while Software is the fastest-growing segment. |
|
By End User Industry: Warehousing and Distribution is the dominant segment, while Healthcare is the fastest-growing segment. |
Market Opportunity: The Asia-Pacific Autonomous Mobile Robot (AMR) market is expected to create an absolute dollar opportunity of USD 5.98 billion between 2026 and 2035, presenting significant investment potential across warehousing automation, healthcare robotics, and Robotics as a Service adoption.
According to NMSC's analysis, rising demand for Robotics as a Service commercial models is lowering adoption barriers for small and mid-sized operators across the Asia-Pacific Autonomous Mobile Robot (AMR) Market.
What does the Asia-Pacific Autonomous Mobile Robot (AMR) Market Encompass?
The Asia-Pacific AMR Market encompasses transport robots, picking robots, mobile manipulators, forklift robots, and specialized robots deployed across warehousing, manufacturing, healthcare, and retail facilities. Our assessment indicates that the market includes LiDAR, vision, and sensor fusion navigation technologies delivered through direct sales, system integrator sales, and Robotics as a Service commercial models. Regional industrial robotics ecosystems in China, Japan, South Korea, and India anchor demand for these systems.
The market has evolved from fixed-path automated guided vehicles toward dynamically navigating, sensor-driven robots capable of adapting to changing facility layouts. We observed that national manufacturing policies in China, Japan, and South Korea, alongside labor-shortage pressures, are accelerating factory automation mandates. NMSC's analysis indicates that growing integration of simultaneous localization and mapping technology, cloud-based fleet orchestration, and Robotics as a Service adoption continues to reshape deployment models, competitive positioning, and purchasing decisions across the Asia-Pacific Autonomous Mobile Robot (AMR) Market.
|
Parameters |
Details |
|
Market Size in 2025 |
USD 1.69 Billion |
|
Market Size in 2026 |
USD 2.07 Billion |
|
Revenue Forecast in 2035 |
USD 8.05 Billion |
|
Market Size Growth Rate |
CAGR of 16.26% from 2026 to 2035 |
|
Market Volume in 2025 |
46 Thousand Units |
|
Market Volume in 2026 |
70 Thousand Units |
|
Volume Forecast in 2035 |
371 Thousand Units |
|
Market Volume Growth Rate |
CAGR of 20.44% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Billion (USD) |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 companies |
Key Emerging Trends
Based on research conducted by NMSC, we found that four structural trends are reshaping deployment models, fleet economics, and competitive dynamics across the Asia-Pacific Autonomous Mobile Robot (AMR) Market.
How Is AI-Enabled Fleet Orchestration Transforming Warehouse Operations?
Cloud-based fleet management platforms embedding AI-driven task allocation are becoming central to large-scale AMR deployments across the region. We observed that operators managing hundreds of units, such as Geekplus's deployment at Toyota Motor Corporation plants in Japan, increasingly rely on adaptive routing software to coordinate mixed fleets across inbound, picking, and processing zones without manual intervention, improving throughput and reducing on-site labor workload.
Why Are Labor Shortages Accelerating Factory-Floor Automation Adoption?
Demographic decline and tightening labor regulations across Japan, South Korea, and China are pushing manufacturers toward robotic in-plant logistics. Our findings suggest that automotive, electronics, and semiconductor producers are prioritizing AMR fleets to offset shrinking workforces, with Japanese manufacturers publicly citing new truck-driver labor rules and population decline as direct triggers for expanded moving-type robot deployments on production floors.
How Is Interoperability Standardization Reshaping Competitive Dynamics?
Open interoperability frameworks that allow AMRs from different vendors to share facility infrastructure are gaining traction across regional automation hubs. We observed that companies such as OMRON have opened dedicated automation centers in Singapore built around interoperability standards, enabling mixed-vendor fleets to coordinate movement, reduce integration costs, and address space constraints common in dense Asia-Pacific manufacturing corridors.
What Role Does Humanoid and Mobile-Manipulation Convergence Play in Innovation?
Convergence between mobile bases and manipulator arms is emerging as a distinct innovation trend among regional robotics developers. Our analysis indicates that companies including Addverb are extending mobile-robot platforms with upper-body manipulation modules for picking, sorting, and material handling tasks, signaling a gradual shift from pure transport robots toward multi-function autonomous systems within Asia-Pacific facilities.
Ecosystem Analysis of the Asia-Pacific Autonomous Mobile Robot (AMR) Market
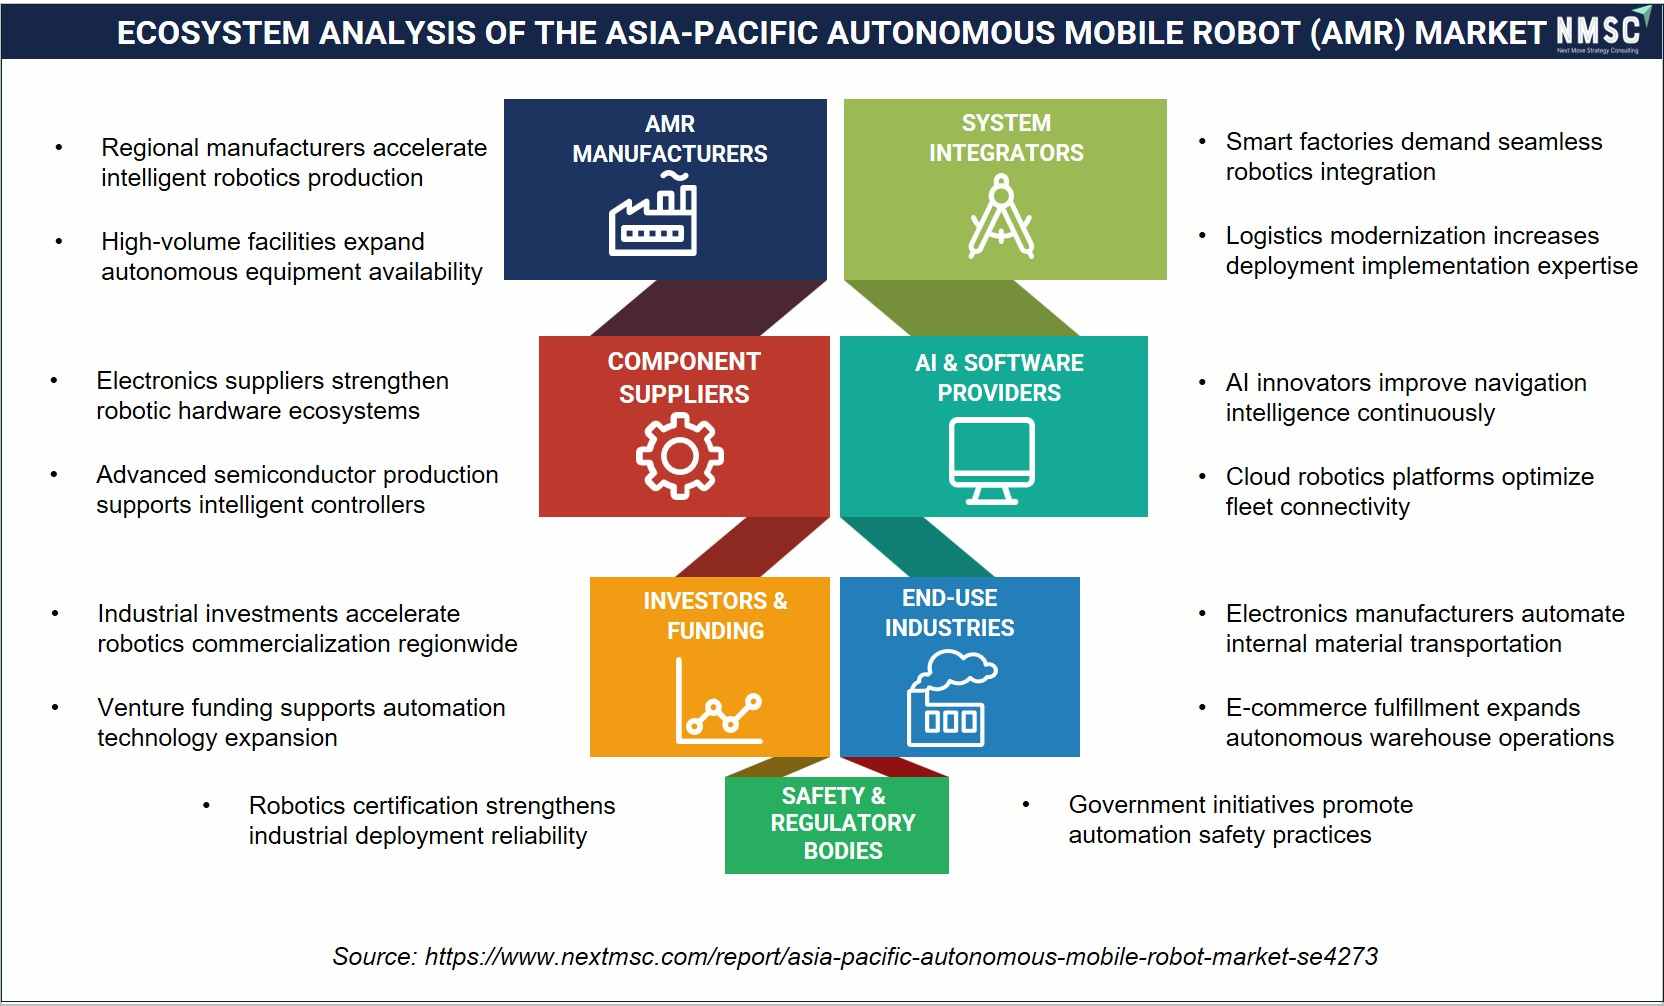
The above ecosystem analysis maps the key operational components, such as AMR manufacturers, system integrators, component suppliers, AI and software providers, investors and funding, end-use industries, and safety and regulatory bodies, shaping the Asia-Pacific AMR market. From our analysis, we observed that AMR manufacturers and component suppliers drive production advancements, while AI and software providers enhance autonomous capabilities. System integrators ensure seamless deployment, whereas investors and funding support market expansion. End-use industries across logistics, manufacturing, and healthcare drive adoption, while safety and regulatory bodies ensure compliance standards across the market ecosystem.
Growth Drivers and Restraints
Growth Catalyst and Risk Assessment Matrix
|
Factors |
Type |
(+/−) % Impact on CAGR |
Geographic Relevance |
Impact Timeline |
|
Rising labor costs and workforce shortages across manufacturing hubs increasing AMR adoption for material transport |
Driver |
+3.85% |
China, Japan, South Korea |
Medium to Long term (2–6 years) |
|
Rapid expansion of semiconductor and electronics manufacturing capacity requiring flexible intralogistics automation |
Driver |
+3.42% |
China, Taiwan, South Korea, Japan |
Long term (2–7 years) |
|
Government-backed smart manufacturing and Industry 4.0 initiatives promoting factory automation investment |
Driver |
+2.67% |
China, Japan, India, South Korea |
Long term (2–9 years) |
|
Growth in e-commerce and new energy battery production expanding logistics and lifting automation demand |
Driver |
+2.31% |
China, India, Southeast Asia |
Long term (2–8 years) |
|
High upfront capital costs and integration complexity limiting adoption among small and mid-sized manufacturers |
Restraint |
−1.92% |
India, Southeast Asia |
Short to Medium term (1–4 years) |
|
Fragmented interoperability standards across vendors constraining mixed-fleet deployment efficiency |
Restraint |
−1.48% |
China, Japan, South Korea |
Short to Medium term (1–3 years) |
What Is the Primary Growth Driver of the Asia-Pacific Autonomous Mobile Robot (AMR) Market?
Rising labor costs and shrinking factory workforces across China, Japan, and South Korea are the primary growth drivers of the Asia-Pacific Autonomous Mobile Robot (AMR) market. Japan's population aged 15–64 has continued to decline according to the Statistics Bureau of Japan, pressuring manufacturers to substitute manual material handling with autonomous transport. We observed that this demographic pressure is directly cited by manufacturers deploying moving-type AMR fleets across automotive and electronics plants.
How Is Semiconductor Manufacturing Expansion Driving Market Growth?
Continued expansion of semiconductor fabrication and packaging capacity across Taiwan, South Korea, China, and Japan is accelerating demand for flexible intralogistics automation. Manufacturers are deploying autonomous transport robots and autonomous forklift robots to move wafers, panels, and components between production and testing stages. Our assessment indicates that investments in cleanroom-compatible navigation and precision payload handling are enabling companies to differentiate their offerings within high-value semiconductor manufacturing environments.
What Is Restraining Asia-Pacific Autonomous Mobile Robot (AMR) Market Expansion?
High upfront capital investment and system integration complexity continue to restrain broader market expansion, particularly among small and mid-sized manufacturers in Southeast Asia and India. Fragmented interoperability standards across vendors further complicate mixed-fleet deployments in shared facilities. We found that companies with limited automation budgets face longer payback periods, constraining adoption pace despite favorable long-term productivity and labor-substitution economics across the region.
Segmentation Analysis
By Navigation Technology Insights
How Is the Asia-Pacific Autonomous Mobile Robot (AMR) Market Segmented by Navigation Technology?
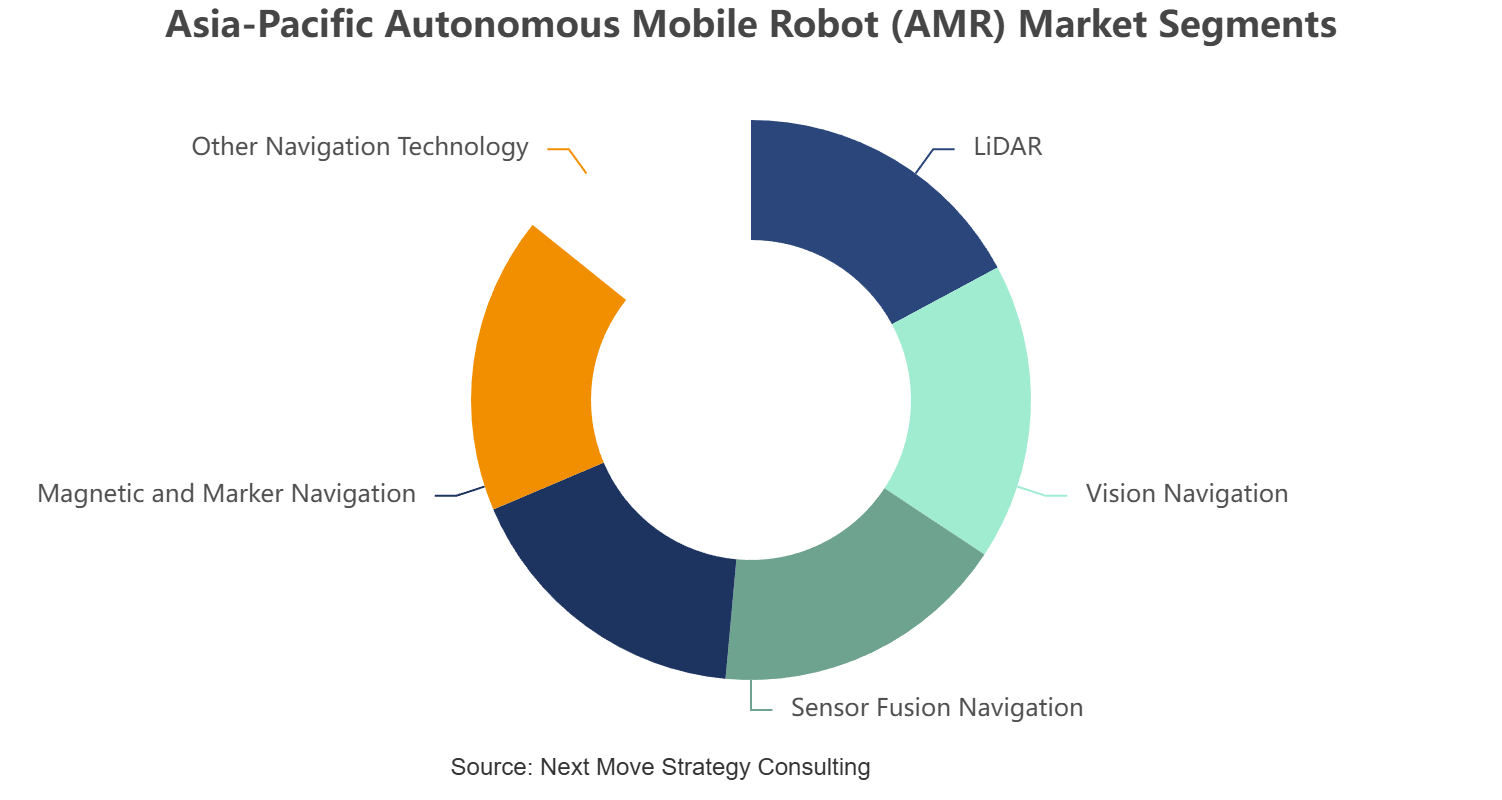
Based on navigation technology, the Asia-Pacific Autonomous Mobile Robot (AMR) Market is segmented into LiDAR, vision navigation, sensor fusion navigation, magnetic and marker navigation, and other navigation technology.
LiDAR-based systems rely on laser ranging to build precise facility maps and detect obstacles in real time, while vision navigation uses camera arrays and image processing to interpret surroundings at comparatively lower hardware cost. Sensor fusion navigation combines LiDAR, cameras, and inertial data to improve reliability in cluttered or variable environments, whereas magnetic and marker navigation depends on fixed infrastructure such as embedded strips or reflective tags for simpler, lower-cost deployments.
Facilities requiring dynamic rerouting around unpredictable obstacles increasingly favor sensor fusion approaches over single-sensor systems. Our findings suggest that operators managing mixed indoor and outdoor deployments are prioritizing navigation technologies capable of handling variable lighting, weather exposure, and irregular surfaces, pushing continued innovation toward multi-sensor architectures that reduce dependency on facility-specific infrastructure modifications.
By Commercial Model Insights
How Is the Asia-Pacific Autonomous Mobile Robot (AMR) Market Segmented by Commercial Model?
Based on commercial model, the Asia-Pacific Autonomous Mobile Robot (AMR) Market is segmented into direct sales, system integrator sales, and Robotics as a Service.
Direct sales involve manufacturers selling AMR units and software licenses directly to end users, typically favored by large-scale operators with dedicated automation teams. System integrator sales route deployments through third-party specialists who combine hardware, software, and facility-specific customization into turnkey automation projects. Robotics as a Service allows operators to access AMR fleets through subscription-based arrangements, shifting capital expenditure into predictable operating costs.
Smaller manufacturers and logistics operators with constrained capital budgets are increasingly drawn toward subscription-based access models that lower entry barriers. Our analysis indicates that this shift is reshaping vendor revenue structures, encouraging providers to bundle maintenance, software updates, and fleet analytics into ongoing service contracts rather than one-time equipment sales across the Asia-Pacific Autonomous Mobile Robot (AMR) Market.
Growth Opportunities
We observed that three forward-looking opportunities are emerging for stakeholders positioned across hardware, software, and systems integration within the Asia-Pacific Autonomous Mobile Robot (AMR) Market.
How Can E-Commerce Fulfillment Operators Benefit from Robotics as a Service?
Rapid growth of e-commerce fulfillment volumes across China and Southeast Asia creates substantial opportunity for vendors offering subscription-based Robotics as a Service models. Companies packaging goods-to-person picking robots into service contracts can capture recurring revenue while lowering adoption barriers for fulfillment operators seeking to scale capacity without large upfront capital commitments.
Where Does Healthcare Facility Automation Create New Revenue Streams?
Hospitals and pharmaceutical facilities across Japan and South Korea are gradually adopting specialized healthcare and laboratory robots for material transport and delivery tasks. Vendors that develop compliant, safety-certified mobile robots tailored to healthcare environments can capture premium pricing while addressing staffing shortages in hospital logistics and laboratory sample handling operations.
How Can Outdoor-Capable AMRs Unlock Value in Logistics Terminals?
Logistics terminal and industrial yard operators require ruggedized AMRs capable of operating in outdoor conditions with variable weather and uneven surfaces. Vendors offering sensor fusion navigation systems calibrated for outdoor deployment can capture premium contracts while helping terminal operators automate container and pallet movement across expanding regional logistics infrastructure.
Which Country is Dominating the Asia-Pacific AMR Market?
Through NMSC's market evaluation, we found that Japan dominates the Asia-Pacific Autonomous Mobile Robot (AMR) Market, underpinned by its highly advanced robotics ecosystem, strong manufacturing base, and longstanding focus on industrial automation. As labor shortages and an aging workforce increase the need for efficient operations, businesses are increasingly adopting AMRs to automate material handling and streamline intralogistics. This demand is further supported by Japan's leadership in robotics innovation, widespread Industry 4.0 adoption, and presence of established automation companies, enabling broader AMR deployment across manufacturing, warehousing, and logistics applications.
Which Country is Set to Witness the Fastest Growth?
Our assessment suggests that Vietnam is set to witness the fastest growth in the Asia-Pacific Autonomous Mobile Robot (AMR) Market through 2035, driven by rapid industrialization, expanding manufacturing activities, and increasing foreign direct investment. As global manufacturers establish production facilities in the country, demand for automated material handling and efficient intralogistics is rising across factories and warehouses. This momentum is further supported by labor cost pressures, growing e-commerce activity, and increasing adoption of Industry 4.0 technologies, creating favorable conditions for accelerated AMR deployment across diverse industries.
Competitive Landscape
We observed that the Asia-Pacific Autonomous Mobile Robot (AMR) market features a highly competitive landscape, with regional robotics specialists competing alongside global industrial automation conglomerates and material handling equipment manufacturers.
|
Key Takeways |
Description |
|
Market Structure |
Moderately consolidated with regional robotics specialists including Geekplus Japan Kabushiki Kaisha and Hangzhou Iplusmobot Technology Co., Ltd. competing alongside global industrial automation companies such as OMRON Corporation, KUKA Robotics Manufacturing Shanghai Co., Ltd., and ABB Shanghai Motors Co., Ltd. |
|
Innovation Focus |
AI-enabled fleet orchestration, interoperability standards, precision navigation for semiconductor and electronics facilities, and mobile-manipulation convergence dominate current product development strategies across leading manufacturers. |
|
M&A Activity |
Strategic partnerships, manufacturing capacity expansion, and technology licensing continue to shape the competitive landscape as companies strengthen positions in high-growth new energy and semiconductor end-user segments. |
How Do Companies Compete in the Asia-Pacific Autonomous Mobile Robot (AMR) Market?
Companies compete primarily through navigation precision, payload versatility, fleet-management software, and integration capability with existing production lines. Leading manufacturers such as OMRON Corporation and KUKA Robotics Manufacturing Shanghai Co., Ltd. leverage established industrial automation portfolios and extensive distribution networks to maintain market leadership. Meanwhile, regional specialists including Geekplus Japan Kabushiki Kaisha and Hangzhou Iplusmobot Technology Co., Ltd. differentiate through flexible system design and rapid deployment capability.
Which Competitive Archetypes Dominate the Asia-Pacific Autonomous Mobile Robot (AMR) Market?
Two primary competitive archetypes characterize the market. The first comprises diversified industrial automation conglomerates offering AMRs alongside broader factory automation portfolios, including OMRON Corporation, ABB Shanghai Motors Co., Ltd., and Toyota Material Handling China Co., Ltd. The second includes dedicated AMR and warehouse robotics specialists such as Geekplus Japan Kabushiki Kaisha, PT GreyOrange Indonesia, Quicktron Korea Co., Ltd., and Hangzhou Iplusmobot Technology Co., Ltd., which focus exclusively on mobile robotics innovation and fleet software.
How Are Companies Differentiating Through Innovation in Asia-Pacific AMR Deployment?
Innovation strategies increasingly focus on AI-driven navigation, cloud-based fleet orchestration, and cleanroom-compatible precision handling for semiconductor applications. Companies are investing in interoperability standards and mobile-manipulation convergence, extending transport robots with picking and sorting capability. Our analysis indicates that manufacturers combining software differentiation with hardware reliability are strengthening competitive positioning across electronics, automotive, and new energy end-user segments.
What Expansion Activity Is Shaping the Asia-Pacific Autonomous Mobile Robot (AMR) Market?
Manufacturing capacity expansion, regional subsidiary establishment, and large-scale fleet deployment partnerships continue to shape competition across the market. Leading companies are strengthening positions through expanded production facilities, deeper integration with automotive and electronics manufacturers, and increased research and development investment. These initiatives enable manufacturers to broaden product portfolios and respond more effectively to evolving automation demand across the Asia-Pacific region.
Key Market Players
Our assessment indicates that the following 15 companies are actively shaping fleet innovation, capacity expansion, and competitive dynamics within the Asia-Pacific Autonomous Mobile Robot (AMR) Market.
-
Geekplus Japan Kabushiki Kaisha
-
PT GreyOrange Indonesia
-
Quicktron Korea Co., Ltd.
-
Hangzhou Iplusmobot Technology Co., Ltd.
-
Jungheinrich Lift Truck Shanghai Co., Ltd.
-
KUKA Robotics Manufacturing Shanghai Co., Ltd.
-
AGILOX China Co., Ltd.
-
Toyota Material Handling China Co., Ltd.
-
ABB Shanghai Motors Co., Ltd.
-
Addverb Technologies Australia Pty Ltd
-
Yujin Robot Co., Ltd.
-
Hanwha Robotics Co., Ltd.
-
AGVE Korea Ltd.
Investment Opportunities
What Capital Inflows Are Targeting the Asia-Pacific Autonomous Mobile Robot (AMR) Market?
Capital inflows are increasingly directed toward fleet-scale manufacturing capacity, navigation software development, and expansion into new energy and semiconductor end-user segments. Leading robotics companies continue to invest in production capacity and research and development to strengthen competitive positioning. We observed that investors favor companies demonstrating scalable deployment track records, such as multi-hundred-unit fleet rollouts, as key indicators of long-term commercial viability.
How Is Infrastructure Investment Supporting the Asia-Pacific Autonomous Mobile Robot (AMR) Market?
Infrastructure investment is expanding manufacturing capacity, regional automation centers, and interoperability testing facilities across the region. Our findings suggest that companies are investing in dedicated automation centers, such as OMRON's Singapore facility, to support mixed-fleet coordination and address regional logistics challenges including labor scarcity and limited facility space, strengthening long-term market penetration across Asia-Pacific manufacturing hubs.
What ESG Considerations Are Shaping Investment Decisions in the Asia-Pacific Autonomous Mobile Robot (AMR) Market?
Environmental, social, and governance considerations increasingly influence investment decisions, with energy-efficient battery systems, workplace safety improvements, and labor-condition enhancements emerging as key priorities. We found that investors favor companies demonstrating measurable progress in reducing energy consumption per deployed unit and improving worker safety outcomes through automation of physically demanding material-handling tasks across manufacturing facilities.
Key Benefits for Stakeholders
How Does This Report Benefit Enterprise and Industry Leaders?
Enterprise and industry leaders gain access to validated market segmentation, competitive benchmarking, and regional demand forecasts that support strategic planning and fleet procurement decisions across the Asia-Pacific AMR Market. Our analysis shows that detailed assessments of component, payload capacity, and end-user industry trends help companies identify high-growth opportunities and strengthen automation roadmaps.
How Does This Report Benefit Investors and Financial Analysts?
Investors and financial analysts benefit from consistent market size estimates, growth forecasts, and competitive assessments that support capital allocation decisions across the Asia-Pacific Autonomous Mobile Robot (AMR) Market. We observed that detailed analysis of new energy, semiconductor, and logistics end-user segments enables stakeholders to identify companies and categories with the strongest long-term growth potential through 2035.
How Does This Report Benefit Technology Vendors and Product Teams?
Technology vendors and product development teams gain insights into emerging innovation trends, including AI-enabled fleet orchestration, interoperability standardization, and mobile-manipulation convergence transforming the Asia-Pacific robotics industry. Our findings suggest that this analysis helps research and development teams prioritize product pipelines and align offerings with evolving manufacturer requirements across the region.
Supply Chain Structure of the Asia-Pacific Autonomous Mobile Robot (AMR) Market
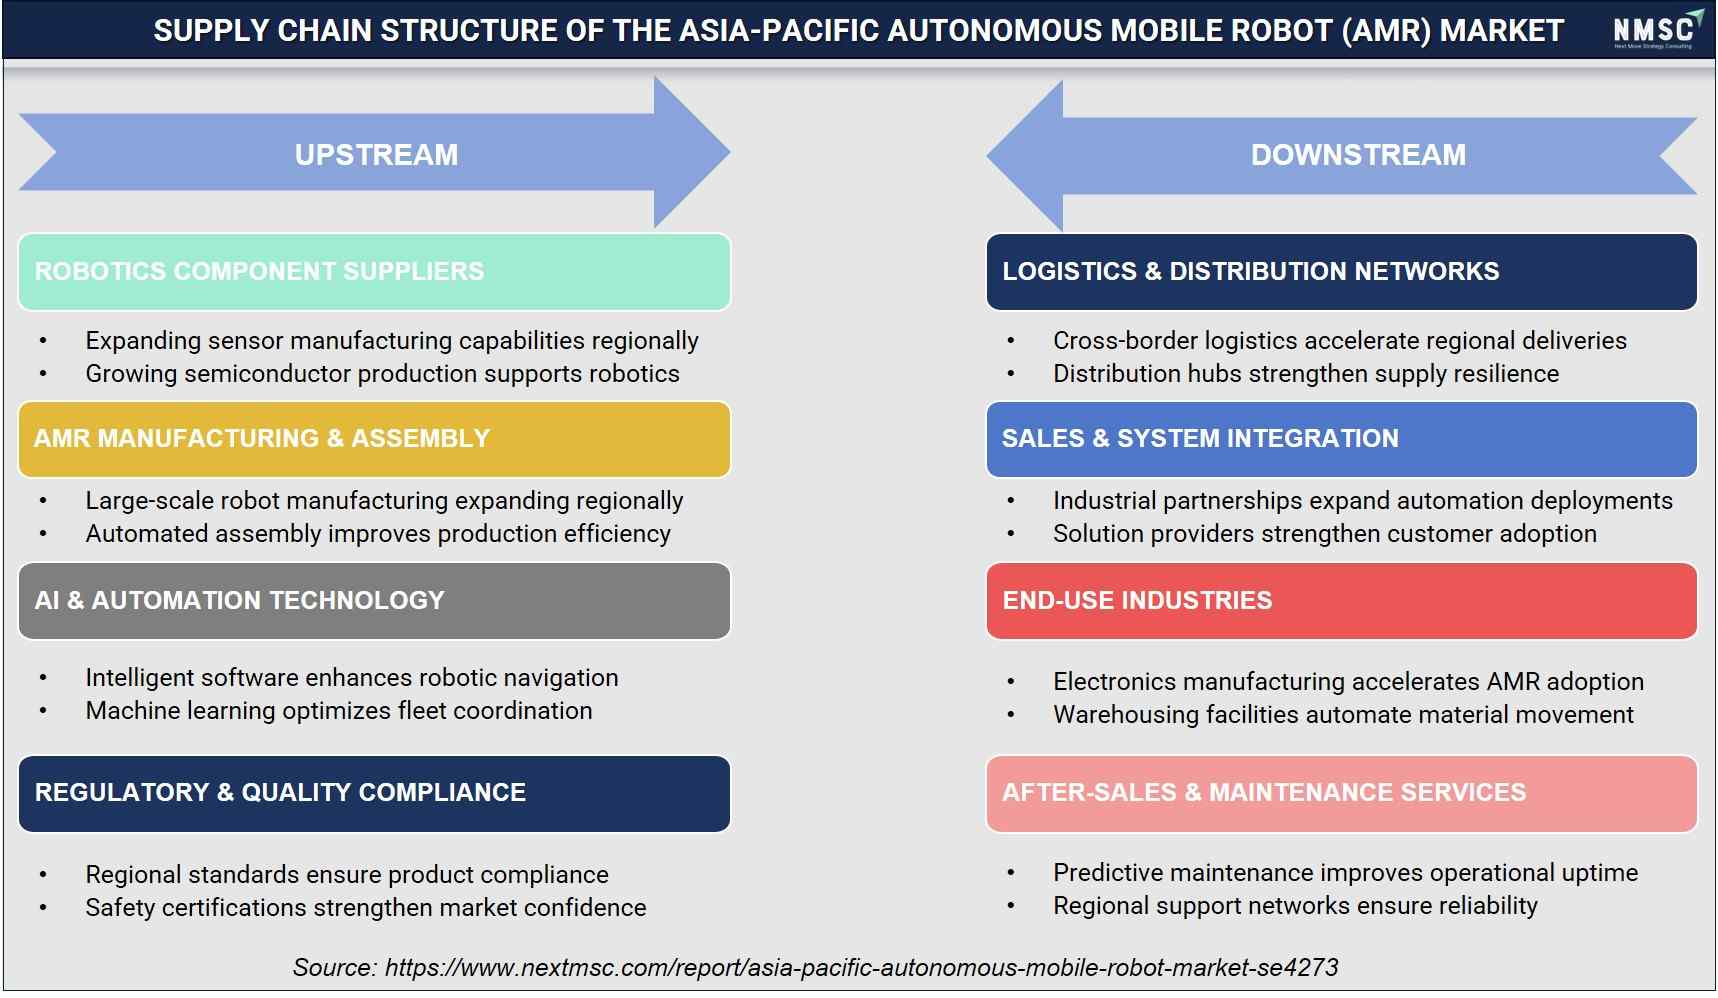
The above supply chain analysis maps the key operational stages, such as upstream and downstream, shaping the Asia-Pacific AMR market. From our analysis, we observed that upstream activities include sensor manufacturing, semiconductor production, large-scale robot assembly, AI software, machine learning, and regional safety certifications, while downstream activities encompass cross-border logistics, industrial partnerships, electronics manufacturing, warehousing automation, and predictive maintenance, reflecting a well-integrated supply chain across the market.
Key Market Segments
By Product Type
-
Autonomous Transport Robots
-
Tugger
-
Cart
-
Pallet
-
Shelf and Rack
-
Conveyor
-
Other Transport Robots
-
-
Autonomous Picking Robots
-
Goods to Person
-
Person to Goods
-
Piece Picking
-
Case Picking
-
Other Picking Robots
-
-
Autonomous Mobile Manipulators
-
Robotic Arm
-
Inspection Manipulators
-
Maintenance Manipulators
-
Other Mobile Manipulators
-
-
Autonomous Forklift Robots
-
Counterbalance Forklift
-
Reach Forklift
-
Stacker Forklift
-
Pallet Truck
-
Other Forklift Robots
-
-
Specialized AMRs
-
Healthcare Robots
-
Laboratory Robots
-
Retail Robots
-
Security Robots
-
Other Specialized Robots
-
By Navigation Technology
-
LiDAR
-
Vision Navigation
-
Sensor Fusion Navigation
-
Magnetic and Marker Navigation
-
Other Navigation Technology
By Payload Capacity
-
< 100 Kgs
-
100 Kgs to 1000 Kgs
-
1001 Kgs to 5000 Kgs
-
> 5000 Kgs
By Deployment Environment
-
Indoor Autonomous Mobile Robots
-
Warehouse Environment
-
Manufacturing Environment
-
Healthcare Environment
-
Retail Environment
-
Laboratory Environment
-
-
Outdoor Autonomous Mobile Robots
-
Industrial Yard Environment
-
Logistics Terminal Environment
-
Other Outdoor Environment
-
By Commercial Model
-
Direct Sales
-
System Integrator Sales
-
Robotics as a Service
By Revenue Stream
-
Robot Hardware
-
Software
-
Fleet Management Software
-
Navigation Software
-
Robot Operating Software
-
Analytics Software
-
AI Software
-
-
Services
-
Installation and Deployment
-
Integration Services
-
Maintenance Services
-
Robotics as a Service
-
By End User Industry
-
Warehousing and Distribution
-
E-commerce Fulfillment
-
Third Party Logistics
-
Retail Distribution
-
-
Manufacturing
-
Automotive
-
Electronics and Semiconductors
-
Machinery and Equipment
-
Food and Beverage Manufacturing
-
Other Manufacturing
-
-
Healthcare
-
Hospitals
-
Laboratories
-
Pharmaceutical Facilities
-
-
Retail
-
Other Industries
By Region
-
China
-
Japan
-
India
-
South Korea
-
Vietnam
-
Philippines
-
Malaysia
-
Australia
-
Indonesia
-
Rest of APAC
Conclusion and Recommendations
What Is the Long-Term Outlook for the Asia-Pacific Autonomous Mobile Robot (AMR) Market?
The long-term outlook remains positive, supported by persistent labor shortages, expanding semiconductor and new energy manufacturing capacity, and continued government-backed automation initiatives. We observed that growing adoption of AI-enabled fleet orchestration and interoperable hardware will continue to drive market expansion across electronics, automotive, and logistics segments throughout the forecast period to 2035.
What Strategic Positioning Should AMR Companies Pursue?
Manufacturers should prioritize investments in interoperable navigation software, cleanroom-compatible precision handling, and mobile-manipulation capability while strengthening partnerships with semiconductor and new energy producers. Our assessment indicates that companies expanding software-defined fleet orchestration and payload versatility will be well positioned to capture premium segments within the Asia-Pacific AMR Market.
How Attractive Is the Asia-Pacific Autonomous Mobile Robot (AMR) Market for New Investment?
The market presents an attractive investment opportunity, supported by a 20.44% volume CAGR and rapid capacity expansion across new energy and semiconductor manufacturing. We found that investment potential is particularly strong for companies focused on fleet-management software, precision navigation, and mobile-manipulation convergence, enabling them to capitalize on sustained regional automation demand.
What Market Shifts and Key Risks Should Stakeholders Monitor?
Stakeholders should monitor fragmented interoperability standards, high upfront capital costs limiting adoption among smaller manufacturers, and intensifying competition from new entrants. Our analysis shows that companies unable to demonstrate software differentiation or scalable deployment economics may face increasing competitive pressure as hardware costs continue to compress across the Asia-Pacific Autonomous Mobile Robot (AMR) Market.
What Are the Key Growth Pathways for the Asia-Pacific Autonomous Mobile Robot (AMR) Market?
Key growth pathways include expanding new energy and semiconductor fleet deployments, accelerating interoperability standardization, and strengthening mobile-manipulation product lines. NMSC's analysis indicates that companies successfully combining software differentiation, precision hardware, and regional manufacturing partnerships will be best positioned to capture the market's projected growth through 2035.
About the Author
 Mayurima Roy
— Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.

SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.




 Speak to Our Analyst