North America Autonomous Mobile Robot (AMR) Market By Product Type (Autonomous Transport Robots, Autonomous Picking Robots, & Others), By Navigation Technology (LiDAR, Vision Navigation, & Others), By Payload Capacity (<100 KG, 100–1000 KG, & Others), By Deployment Environment (Indoor & Outdoor), By Commercial Model (Direct Sales, System Integrator Sales, & Others), By End-User Industry (Warehousing and Distribution, Manufacturing, & Others) – Opportunity Analysis & Forecast, 2025–2035
Industry: Semiconductor & Electronics | Latest Edition: August 21, 2026 | No of Pages: 632 | No. of Tables: 312 | No. of Figures: 296 | Format: PDF | Report Code: SE4249
What Is the North America Autonomous Mobile Robot (AMR) Market Size?
The North America Autonomous Mobile Robot (AMR) Market was valued at USD 732.2 Million in 2025 and is estimated at USD 903.1 Million in 2026, forecast to reach USD 3,599.6 Million by 2035, expanding at a 16.61% CAGR between 2026 and 2035. Autonomous Transport Robots dominate the market by product type, driven by widespread deployment of tugger, cart, and pallet-moving robots across warehouse floors.In terms of volume, the North America AMR market recorded 23 thousand units in 2025, with forecasts indicating growth to 30 thousand units by 2026 and further to 160 thousand units by 2035, reflecting a CAGR of 20.66% over the forecast period.
We observed that market growth is supported by persistent labor shortages across logistics and manufacturing, rising e-commerce fulfillment volumes, and continuous innovation in sensor fusion navigation, fleet orchestration software, and Robotics as a Service delivery models through 2035.
|
Key Takeaways |
|
By Product Type: Autonomous Transport Robots is the dominant segment, while Autonomous Mobile Manipulators is the fastest-growing segment. |
|
By Navigation Technology: LiDAR is the dominant segment, while Sensor Fusion Navigation is the fastest-growing segment. |
|
By Payload Capacity: 100 Kgs to 1000 Kgs is the dominant segment, while 1001 Kgs to 5000 Kgs is the fastest-growing segment. |
|
By Deployment Environment: Indoor Autonomous Mobile Robots is the dominant segment, while Outdoor Autonomous Mobile Robots is the fastest-growing segment. |
|
By Commercial Model: Direct Sales is the dominant segment, while Robotics as a Service is the fastest-growing segment. |
|
By Revenue Stream: Robot Hardware is the dominant segment, while Software is the fastest-growing segment. |
|
By End User Industry: Warehousing and Distribution is the dominant segment, while Healthcare is the fastest-growing segment. |
Market Opportunity: The North America Autonomous Mobile Robot (AMR) Market is expected to create an absolute dollar opportunity of USD 2,696.5 Million between 2026 and 2035, presenting significant investment potential across sensor fusion navigation, Robotics as a Service delivery, and heavy-payload forklift automation segments.
According to NMSC's analysis, companies are increasingly investing in modular payload configurations, subscription-based commercial models, and interoperable fleet software, strengthening their competitive position in the North America Autonomous Mobile Robot (AMR) Market through 2035.
What does the North America Autonomous Mobile Robot (AMR) Market Encompass?
The North America Autonomous Mobile Robot (AMR) Market encompasses self-navigating robotic platforms that transport, pick, and manipulate materials across warehousing, manufacturing, healthcare, and retail environments without relying on fixed infrastructure. Our assessment indicates that the market spans transport, picking, manipulator, and forklift robot categories sold through direct sales, system integrators, and subscription-based commercial models across the United States, North America, and Mexico.
The market has evolved from single-function transport robots into multi-capability platforms supporting picking, manipulation, and inspection tasks within integrated warehouse automation programs. Regulatory oversight from the Occupational Safety and Health Administration and voluntary adoption of interoperability frameworks such as VDA5050 continue to shape safety and integration requirements, while rising adoption of sensor fusion navigation and AI-based fleet software is accelerating deployment across e-commerce fulfillment, automotive, and healthcare facilities throughout North America.
|
Parameters |
Details |
|
Market Size in 2025 |
USD 732.2 Million |
|
Market Size in 2026 |
USD 903.1 Million |
|
Revenue Forecast in 2035 |
USD 3,599.6 Million |
|
Market Size Growth Rate |
CAGR of 16.61% from 2026 to 2035 |
|
Market Volume in 2025 |
23 Thousand Units |
|
Market Volume in 2026 |
30 Thousand Units |
|
Volume Forecast in 2035 |
160 Thousand Units |
|
Market Volume Growth Rate |
CAGR of 20.66% from 2026 to 2035 |
|
Analysis Period |
2025–2035 |
|
Base Year Considered |
2025 |
|
Forecast Period |
2026–2035 |
|
Market Size Estimation |
Million (USD) |
|
Companies Profiled |
15 |
|
Market Share |
Available for 10 companies |
Key Emerging Trends
Based on research conducted by NMSC, we found that four structural trends are reshaping product design, navigation technology, and commercial delivery models across the North America Autonomous Mobile Robot (AMR) Market.
How Is Sensor Fusion Navigation Transforming Deployment Reliability?
Sensor fusion navigation combining LiDAR, vision cameras, and radar is becoming a key differentiator across the North America Autonomous Mobile Robot (AMR) Industry. We observed that operators are increasingly favoring multi-sensor platforms over single-technology navigation to improve obstacle detection and path planning accuracy in dynamic, mixed-traffic facility floors. As a result, manufacturers such as Seegrid Corporation are expanding multi-layer perception suites to strengthen deployment confidence across manufacturing and warehousing environments.
Why Is Robotics as a Service Gaining Momentum as a Commercial Model?
Subscription-based Robotics as a Service delivery is gaining traction as enterprises seek to avoid large upfront capital commitments. Our findings suggest that providers are bundling hardware, software, and maintenance into flexible contracts, enabling faster fleet scaling during demand surges. This commercial model is expanding AMR adoption beyond large enterprises into mid-market logistics and manufacturing operations across the United States, North America, and Mexico.
How Are Autonomous Picking Robots Reshaping Fulfillment Operations?
Autonomous picking robots supporting goods-to-person and piece-picking workflows are transforming e-commerce fulfillment center operations. We observed that operators are deploying picking robots alongside transport robots to reduce walking time and improve order accuracy in high-volume distribution environments. This trend is strengthening throughput across third-party logistics and retail distribution operations while reducing dependency on manual piece-picking labor.
What Role Do Autonomous Mobile Manipulators Play in Inspection and Maintenance?
Autonomous mobile manipulators equipped with robotic arms are expanding beyond material transport into inspection and maintenance applications. Our analysis indicates that manufacturers are integrating manipulator payloads onto mobile platforms to automate equipment inspection and routine maintenance tasks in manufacturing environments. This trend is enabling facilities to extend automation coverage into tasks previously requiring dedicated fixed robotic infrastructure.
Ecosystem Analysis of the North America Autonomous Mobile Robot (AMR) Market
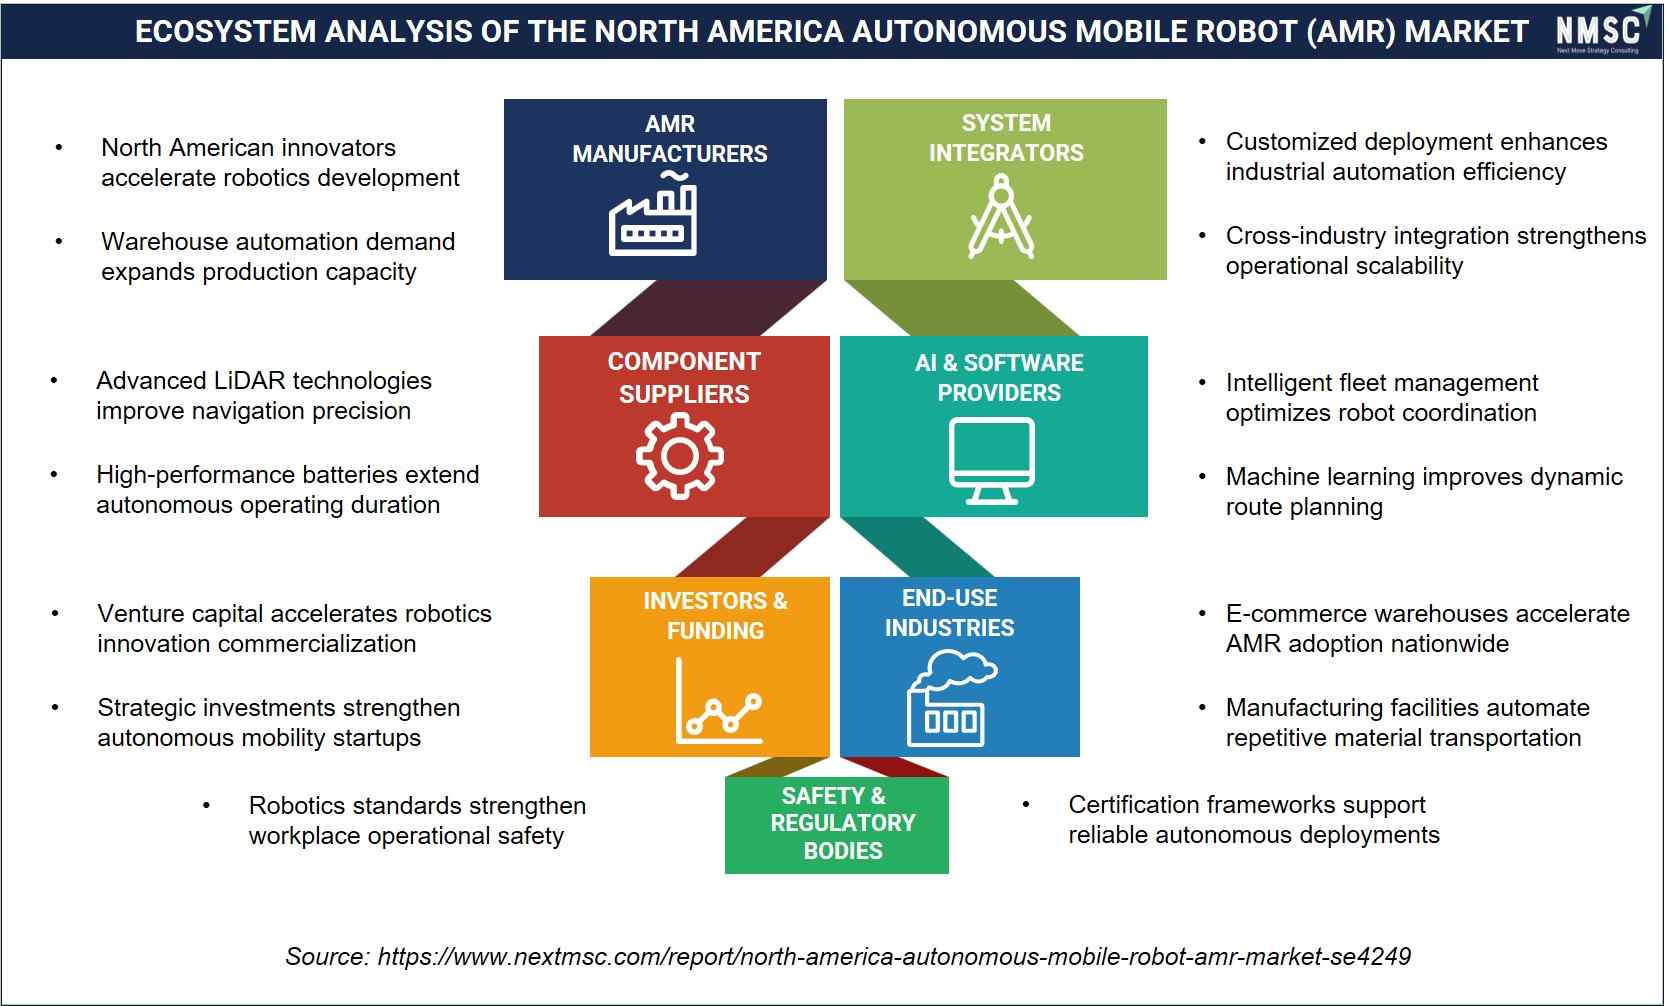
The above ecosystem analysis maps the key operational components, such as AMR manufacturers, system integrators, component suppliers, AI and software providers, investors and funding, end-use industries, and safety and regulatory bodies, shaping the North America AMR market. From our analysis, we observed that AMR manufacturers and component suppliers drive production advancements, while AI and software providers enhance autonomous capabilities. System integrators ensure seamless deployment, whereas investors and funding support market expansion. End-use industries across logistics, manufacturing, and e-commerce drive adoption, while safety and regulatory bodies ensure compliance standards across the market ecosystem.
Growth Drivers and Restraints
Growth Catalyst and Risk Assessment Matrix
|
Factors |
Type |
(+/−) % Impact on CAGR |
Geographic Relevance |
Impact Timeline |
|
Persistent warehouse and manufacturing labor shortages accelerating automation adoption |
Driver |
+3.85% |
North America (nationwide; strongest in U.S. logistics hubs) |
Medium to Long term (2–6 years) |
|
Rising e-commerce fulfillment volumes requiring scalable picking and transport capacity |
Driver |
+3.21% |
North America (U.S. and North America e-commerce corridors) |
Long term (2–7 years) |
|
Growing adoption of sensor fusion navigation and fleet orchestration software |
Driver |
+2.64% |
North America (nationwide) |
Long term (2–8 years) |
|
Expanding Robotics as a Service commercial models lowering adoption barriers |
Driver |
+1.98% |
North America (nationwide; strongest among mid-market enterprises) |
Medium term (2–5 years) |
|
Growing reshoring investment in electronics and automotive manufacturing capacity |
Driver |
+1.75% |
North America (U.S. manufacturing clusters) |
Medium term (2–5 years) |
|
High upfront integration and facility retrofitting costs limiting small enterprise adoption |
Restraint |
−1.62% |
North America (nationwide; strongest among small and mid-sized enterprises) |
Short to Medium term (1–4 years) |
|
Interoperability gaps across multi-vendor picking and transport fleets |
Restraint |
−1.24% |
North America (nationwide) |
Short to Medium term (1–3 years) |
|
Cybersecurity vulnerabilities in connected fleet management systems |
Restraint |
−0.98% |
North America (nationwide) |
Short to Medium term (1–4 years) |
What Is the Primary Growth Driver of the North America Autonomous Mobile Robot (AMR) Market?
Persistent labor shortages across warehousing and manufacturing are the primary growth driver of the North America AMR Market. According to the U.S. Bureau of Labor Statistics, job openings in transportation, warehousing, and manufacturing have remained structurally elevated relative to available labor supply. We observed that enterprises are increasingly deploying transport, picking, and forklift robots to sustain throughput without proportional headcount growth across distribution and production facilities.
How Is Sensor Fusion Navigation Driving North America Autonomous Mobile Robot (AMR) Market Growth?
Continuous innovation in sensor fusion navigation and fleet orchestration software is accelerating growth across the North America Autonomous Mobile Robot (AMR) Market. Manufacturers are expanding multi-sensor platforms that improve obstacle detection and path planning across mixed transport and picking robot fleets. Our assessment indicates that these capabilities are enabling companies to differentiate hardware offerings, strengthen customer retention, and capture growing demand from e-commerce fulfillment and manufacturing end users.
What Is Restraining North America AMR Market Expansion?
High upfront integration costs and facility retrofitting requirements continue to restrain market expansion, particularly for small and mid-sized enterprises. Manufacturers face increasing pressure to demonstrate measurable return on investment while navigating interoperability gaps across multi-vendor picking and transport fleets. We found that smaller operators are especially affected, as capital constraints and limited in-house automation expertise can delay large-scale AMR fleet deployment relative to well-capitalized enterprise customers.
Segmentation Analysis
By Product Type Insights
How Is the North America Autonomous Mobile Robot (AMR) Market Segmented by Product Type?
Based on product type, the North America Autonomous Mobile Robot (AMR) Market is segmented into autonomous transport robots, autonomous picking robots, autonomous mobile manipulators, autonomous forklift robots, and specialized AMRs.
Transport robots covering tugger, cart, pallet, and shelf-and-rack configurations continue to represent extensive deployment scale given their versatility across warehousing and manufacturing floors, while picking robots supporting goods-to-person and piece-picking workflows are expanding rapidly alongside e-commerce fulfillment growth. Mobile manipulators and specialized AMRs, including healthcare and laboratory robots, are gradually broadening the product category beyond pure material movement into inspection, maintenance, and service-oriented applications across diverse facility types.
By Navigation Technology Insights
How Is the North America Autonomous Mobile Robot (AMR) Market Segmented by Navigation Technology?
Based on navigation technology, the North America Autonomous Mobile Robot (AMR) Market is segmented into LiDAR, vision navigation, sensor fusion navigation, magnetic and marker navigation, and other navigation technology.
LiDAR-based systems remain widely deployed given their mapping precision and established integration pathways across facility environments, while sensor fusion navigation combining multiple detection modalities is gaining preference among enterprises deploying mixed fleets in complex, high-traffic environments. Providers are increasingly layering vision-based perception atop LiDAR to improve object recognition, reflecting a broader shift toward multi-modal navigation architectures supported by advances in industrial automation software and edge computing hardware.
Growth Opportunities
Building on these structural trends, three forward-looking opportunities stand out for stakeholders positioning within the North America Autonomous Mobile Robot (AMR) Market.
How Can Robotics as a Service Expand Mid-Market Adoption in North America?
Subscription-based Robotics as a Service commercial models create opportunity for providers targeting mid-market logistics and manufacturing enterprises previously deterred by high capital costs. Companies bundling hardware, software, and maintenance into flexible contracts can accelerate fleet scaling among enterprises with limited in-house automation budgets.
Where Do Autonomous Picking Robots Create New Fulfillment Demand in North America Autonomous Mobile Robot (AMR) Industry?
Expanding e-commerce fulfillment volumes create substantial opportunity for providers of goods-to-person and piece-picking robots. Companies developing high-accuracy picking platforms can capture demand from third-party logistics and retail distribution operators seeking to reduce manual picking labor dependency.
How Can Autonomous Mobile Manipulators Unlock Inspection Automation Value?
Growing enterprise interest in automated equipment inspection and maintenance creates opportunity for providers of autonomous mobile manipulators. Companies integrating robotic arms onto mobile platforms can capture value from manufacturing facilities seeking to extend automation coverage beyond material transport into inspection and maintenance tasks.
Which Country is Dominating the North America Autonomous Mobile Robot (AMR) Market?
Through NMSC's assessment, we found that the U.S. dominates the North America Autonomous Mobile Robot (AMR) Market because its well-established automation ecosystem is accelerating AMR adoption across warehouses, manufacturing facilities, and distribution centers. As e-commerce expands and labor shortages increase, businesses are increasingly turning to AMRs to improve operational efficiency and reduce dependence on manual material handling. This growing demand is further supported by strong investments in artificial intelligence, machine vision, and autonomous navigation, while the presence of leading robotics companies and advanced R&D capabilities continues to reinforce the country's market leadership.
Which Country is Set to Witness the Fastest Growth?
Based on NMSC's research, we found that Mexico is set to witness the fastest growth in the North America Autonomous Mobile Robot (AMR) Market through 2035, driven by expanding manufacturing, nearshoring investments, and rising demand for efficient intralogistics. As global manufacturers establish and expand production facilities in Mexico, the need to automate material movement and streamline warehouse operations is increasing. This momentum is further strengthened by labor cost pressures and growing adoption of Industry 4.0 technologies, encouraging businesses to integrate AMRs and accelerating the country's market growth.
Competitive Landscape
We observed that the North America Autonomous Mobile Robot (AMR) Market features a highly competitive landscape, with diversified industrial automation conglomerates competing alongside specialized AMR pure-plays and material handling equipment providers.
|
Key Takeaways |
|
Market Structure: Highly competitive with diversified industrial automation conglomerates alongside specialized AMR pure-play providers. Large multinational manufacturers account for a significant share of the North America Autonomous Mobile Robot (AMR) Market, while pure-play specialists continue to strengthen their presence through navigation software differentiation and Robotics as a Service models. |
|
Innovation Focus: Sensor fusion navigation, autonomous picking robotics, mobile manipulator integration, and Robotics as a Service delivery models dominate current product development strategies across leading manufacturers. |
|
M&A Activity: Strategic partnerships, technology licensing, and portfolio expansion continue to shape the competitive landscape as companies strengthen positions in picking robotics, heavy-payload forklift automation, and cross-vendor interoperability. |
How Do Companies Compete in the North America Autonomous Mobile Robot (AMR) Market?
Companies compete primarily through navigation software sophistication, product type breadth, and commercial model flexibility. Leading manufacturers such as OMRON Corporation, Toyota Industries Corporation, and ABB Ltd leverage extensive research capabilities, established distribution networks, and broad industrial automation portfolios to maintain market leadership. Meanwhile, specialized providers including Seegrid Corporation and Vecna Robotics, Inc. differentiate themselves through transport and forklift robot expertise, proprietary orchestration engines, and Robotics as a Service delivery models.
Which Competitive Archetypes Dominate the North America Autonomous Mobile Robot (AMR) Market?
Two primary competitive archetypes characterize the market. The first comprises diversified industrial automation conglomerates offering AMRs alongside broader robotics and automation portfolios, supported by extensive global distribution. Companies such as OMRON Corporation, KUKA Aktiengesellschaft, ABB Ltd, and Honeywell International Inc. represent this category. The second includes AMR pure-play specialists such as Seegrid Corporation, Vecna Robotics, Inc., and Mobile Industrial Robots Mexico, S. de R.L. de C.V., which focus on transport and forklift robotics, proprietary navigation software, and flexible subscription delivery models.
How Are Companies Differentiating Through Innovation in North America Autonomous Mobile Robot (AMR) Solutions?
Innovation strategies increasingly focus on sensor fusion navigation, autonomous picking capability, and mobile manipulator integration. Companies are investing in fleet management platforms capable of coordinating mixed transport, picking, and forklift robot fleets while expanding payload ranges to serve heavier pallet handling use cases. Our analysis indicates that manufacturers combining navigation sophistication with flexible commercial models are strengthening their competitive positioning across the North American AMR industry.
What Partnership and Expansion Activity Is Shaping the North America Autonomous Mobile Robot (AMR) Market?
Strategic technology partnerships and portfolio expansion continue to shape competition across the market. Leading companies are strengthening positions through perception and compute technology integrations, expanding manufacturing capabilities, and enhancing fleet interoperability standards. These initiatives enable manufacturers to broaden product type portfolios, enter high-growth picking and manipulator categories, and respond more effectively to evolving enterprise demand for scalable, interoperable automation solutions.
Key Market Players
Our assessment indicates that the following 15 companies are actively shaping product innovation, navigation technology, and competitive dynamics within the North America Autonomous Mobile Robot (AMR) Market.
-
Teradyne, Inc.
-
Seegrid Corporation
-
Vecna Robotics, Inc.
-
Agilox North America Inc.
-
Jungheinrich Lift Truck North America Inc.
-
Toyota Industries Corporation
-
KUKA Aktiengesellschaft
-
ABB Ltd
-
Daifuku Co., Ltd.
-
Dematic Corp.
-
SSI SCHAEFER System International Ltd.
-
Honeywell International Inc.
-
Mecalux México, S.A. de C.V.
Latest Developments
We found that recent developments within the North America Autonomous Mobile Robot (AMR) Market are concentrated on perception technology integration, interoperability standardization, and expanded payload configurations, reflecting the industry's growing emphasis on scalable, software-defined automation.
|
Date |
Event |
|
May 2025 |
Honeywell International Inc. and Teradyne Robotics partnered in the United States to deploy autonomous mobile robot (AMR) solutions for warehouses, combining Honeywell's software with MiR AMRs to improve material handling, productivity, and automation efficiency. |
Investment Opportunities
What Capital Inflows Are Targeting the North America Autonomous Mobile Robot (AMR) Market?
Capital inflows into the North America AMR Market are increasingly directed toward sensor fusion navigation, autonomous picking robotics, and Robotics as a Service delivery platforms. Leading industrial automation companies continue to invest in perception technology partnerships and interoperability compliance to strengthen competitive positioning. We observed that investors favor companies demonstrating strong software differentiation, established enterprise customer bases, and scalable subscription-based commercial models.
How Is Infrastructure Investment Supporting the North America Autonomous Mobile Robot (AMR) Market?
Infrastructure investment is expanding manufacturing capabilities, research facilities, and fleet interoperability frameworks across the North American AMR industry. Our findings suggest that companies are investing in advanced production technologies and supply chain management platforms to improve operational efficiency and accelerate deployment timelines. In addition, manufacturers are strengthening partnerships with system integrators and semiconductor fabrication facilities to enhance market penetration across North America.
What ESG Considerations Are Shaping Investment Decisions in the North America Autonomous Mobile Robot (AMR) Market?
Environmental, social, and governance considerations are becoming integral to investment decisions, with energy-efficient drive systems, extended battery life, and workplace safety emerging as key priorities. We found that investors increasingly favor companies demonstrating measurable progress in reducing facility energy consumption, improving worker safety through collision-avoidance systems, and maintaining transparent supply chain governance across their hardware component sourcing.
Key Benefits for Stakeholders
How Does This Report Benefit Enterprise and Industry Leaders?
Enterprise and industry leaders gain access to validated market segmentation, competitive benchmarking, and technology trend analysis that support strategic planning, fleet procurement, and automation roadmap development across the North America AMR Market. Our analysis shows that detailed assessments of product type, navigation technology, and end-user industry trends help companies identify high-growth opportunities and strengthen automation investment decisions.
How Does This Report Benefit Investors and Financial Analysts?
Investors and financial analysts benefit from consistent market size estimates, growth forecasts, and competitive assessments that support investment evaluation and capital allocation decisions across the North America Autonomous Mobile Robot (AMR) Market. We observed that the report's detailed analysis of product type, revenue stream, and commercial model segments enables stakeholders to identify companies with the strongest long-term growth potential through 2035.
How Does This Report Benefit Technology Vendors and Product Teams?
Technology vendors and product development teams gain valuable insights into emerging innovation trends, including sensor fusion navigation, autonomous picking robotics, and Robotics as a Service delivery models transforming the North American AMR industry. Our findings suggest that this analysis helps research and development teams prioritize future product pipelines and align offerings with evolving enterprise expectations.
Porter's Five Forces Analysis of the North America Autonomous Mobile Robot (AMR) Market
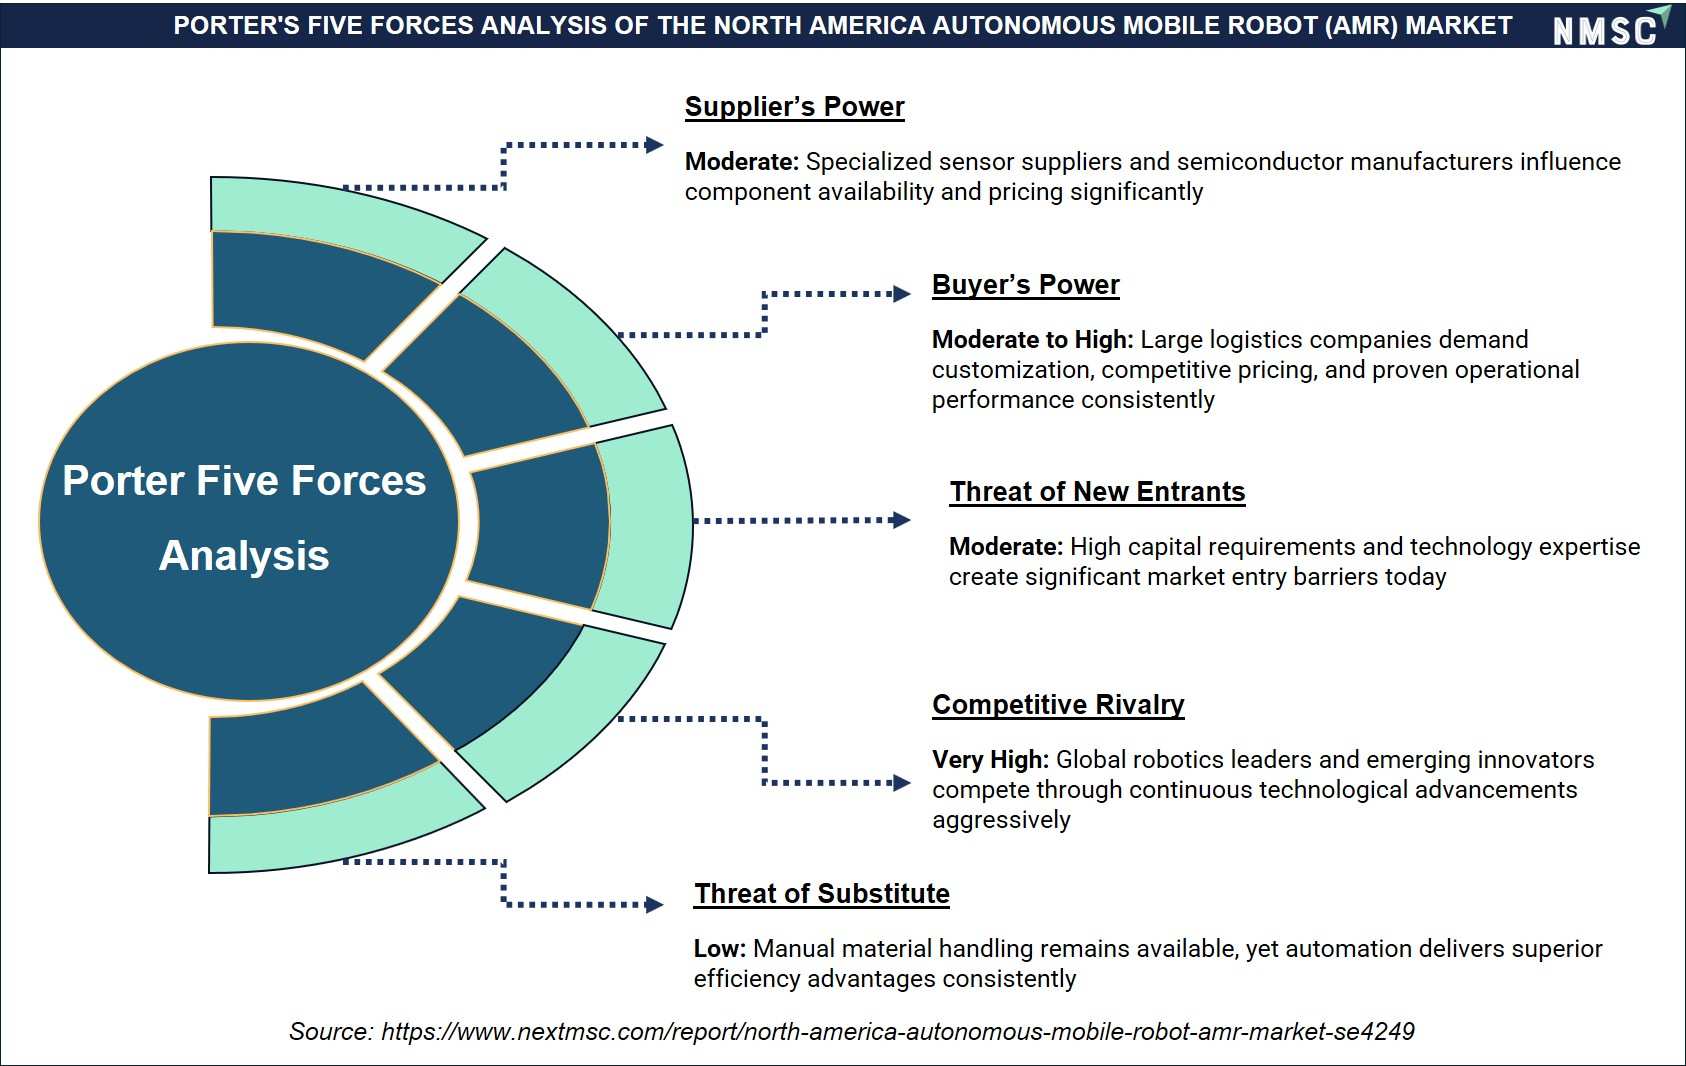
The above Porter's Five Forces analysis maps the key competitive forces, such as threat of new entrants, bargaining power of suppliers, bargaining power of buyers, threat of substitutes, and industry rivalry, shaping the North America AMR market. From our analysis, we observed that industry rivalry remains intense with major technology players competing across sectors, while the bargaining power of suppliers is moderate due to specialized component dependencies. The threat of new entrants is limited by high R&D investments, whereas the bargaining power of buyers is growing with logistics and manufacturing applications driving demand, and the threat of substitutes remains low given AMR versatility.
Key Market Segments
By Product Type
-
Autonomous Transport Robots
-
Tugger
-
Cart
-
Pallet
-
Shelf and Rack
-
Conveyor
-
Other Transport Robots
-
-
Autonomous Picking Robots
-
Goods to Person
-
Person to Goods
-
Piece Picking
-
Case Picking
-
Other Picking Robots
-
-
Autonomous Mobile Manipulators
-
Robotic Arm
-
Inspection Manipulators
-
Maintenance Manipulators
-
Other Mobile Manipulators
-
-
Autonomous Forklift Robots
-
Counterbalance Forklift
-
Reach Forklift
-
Stacker Forklift
-
Pallet Truck
-
Other Forklift Robots
-
-
Specialized AMRs
-
Healthcare Robots
-
Laboratory Robots
-
Retail Robots
-
Security Robots
-
Other Specialized Robots
-
By Navigation Technology
-
LiDAR
-
Vision Navigation
-
Sensor Fusion Navigation
-
Magnetic and Marker Navigation
-
Other Navigation Technology
By Payload Capacity
-
< 100 Kgs
-
100 Kgs to 1000 Kgs
-
1001 Kgs to 5000 Kgs
-
> 5000 Kgs
By Deployment Environment
-
Indoor Autonomous Mobile Robots
-
Warehouse Environment
-
Manufacturing Environment
-
Healthcare Environment
-
Retail Environment
-
Laboratory Environment
-
-
Outdoor Autonomous Mobile Robots
-
Industrial Yard Environment
-
Logistics Terminal Environment
-
Other Outdoor Environment
-
By Commercial Model
-
Direct Sales
-
System Integrator Sales
-
Robotics as a Service
By Revenue Stream
-
Robot Hardware
-
Software
-
Fleet Management Software
-
Navigation Software
-
Robot Operating Software
-
Analytics Software
-
AI Software
-
-
Services
-
Installation and Deployment
-
Integration Services
-
Maintenance Services
-
Robotics as a Service
-
By End User Industry
-
Warehousing and Distribution
-
E-commerce Fulfillment
-
Third Party Logistics
-
Retail Distribution
-
-
Manufacturing
-
Automotive
-
Electronics and Semiconductors
-
Machinery and Equipment
-
Food and Beverage Manufacturing
-
Other Manufacturing
-
-
Healthcare
-
Hospitals
-
Laboratories
-
Pharmaceutical Facilities
-
-
Retail
-
Other Industries
By Region
-
U.S.
-
Canada
-
Mexico
Conclusion and Recommendations
What Is the Long-Term Outlook for the North America Autonomous Mobile Robot (AMR) Market?
The long-term outlook for the North America AMR Market remains positive, supported by persistent labor shortages, rising e-commerce fulfillment volumes, and continued innovation in sensor fusion navigation and picking robotics. We observed that growing adoption of Robotics as a Service models and expanding manufacturing automation investment will continue to drive market expansion across product type and revenue stream segments throughout the forecast period.
What Strategic Positioning Should AMR Companies Pursue?
Manufacturers should prioritize investments in sensor fusion navigation, autonomous picking capability, and flexible commercial models while strengthening Robotics as a Service delivery capabilities. Our assessment indicates that companies expanding payload flexibility and cross-vendor fleet coordination will be well positioned to strengthen customer retention and capture growing demand within the North America Autonomous Mobile Robot (AMR) Industry.
How Attractive Is the North America Autonomous Mobile Robot (AMR) Market for New Investment?
The North America Autonomous Mobile Robot (AMR) Market presents an attractive investment opportunity, supported by growing enterprise automation spending, rising fulfillment center construction, and continued innovation in navigation and picking technologies. We found that investment potential is particularly strong for companies focused on autonomous picking robotics, cross-vendor interoperability, and subscription-based delivery models.
What Market Shifts and Key Risks Should Stakeholders Monitor?
Stakeholders should closely monitor evolving interoperability standards, increasing competition from emerging AMR specialists, and fluctuations in component and semiconductor input costs. Our analysis shows that companies unable to continuously innovate navigation software or demonstrate measurable return on investment may face increasing competitive pressure across the North American AMR market.
What Are the Key Growth Pathways for the North America Autonomous Mobile Robot (AMR) Market?
Key growth pathways include expanding autonomous picking robotics, accelerating cross-vendor interoperability compliance, strengthening Robotics as a Service delivery models, and enhancing sensor fusion navigation capabilities. NMSC's analysis indicates that companies successfully combining navigation sophistication, payload flexibility, and flexible subscription delivery will be best positioned to capture the North America Autonomous Mobile Robot (AMR) Industry projected growth through 2035.


About the Author
 Mayurima Roy
— Mayurima Roy is Research Analyst at Next Move Strategy Consulting, where she has spent 4 years working across the firm's full industry coverage rather than a single fixed vertical. Her work centers on structured research, ongoing trend tracking, competitive assessment, and insight-led content development, translating complex market data into clear, decision-ready narratives that support informed client decision-making across diverse global industries, market sectors, and world regions every day.
About the Reviewer
 Supradip Baul
— Supradip Baul is an accomplished business consultant and strategist with over a decade of rich experience in market intelligence, strategy, technology, and business transformation. His work has included rigorous qualitative and quantitative analysis across multiple industries, helping clients shape investment decisions and long-term roadmaps. Earlier in his career, he was associated with Gartner, where he contributed to industry-leading reports and market share analyses. He has worked with leading global companies and holds an MBA with a dual specialization in Marketing and Finance.
At Next Move Strategy Consulting, we understand that insightful market research is the cornerstone of successful business decisions. That's why we employ a robust and multifaceted approach, combining various methodologies to deliver the most accurate and actionable data for our clients.

Research Landscape
We navigate the world of research with two primary approaches:
Qualitative Approach
Our qualitative research methodologies involve immersive techniques such as in-depth interviews, focus groups, and observational studies. By engaging directly with individuals and stakeholders, we uncover valuable insights that quantitative data alone may overlook.

Quantitative Research
In tandem with qualitative methodologies, NMSC leverages the power of Quantitative Research to provide a robust foundation of numerical insights. Through systematic data collection and analysis, we quantify patterns, preferences, and market trends, offering a comprehensive view of the business landscape.
Our quantitative research approach employs diverse tools, including surveys, experiments, and statistical modelling. These methodologies enable us to gather data from a large and representative sample, ensuring the statistical significance of our findings. By employing structured questionnaires and standardized data collection methods, we guarantee the reliability and validity of the information we present to our clients.
Quantitative research is particularly effective in measuring the prevalence of trends, assessing market size, and gauging the impact of various factors on consumer behavior. The numerical precision attained through this approach equips our clients with actionable insights, facilitating data-driven decision-making and strategy formulation.


Our Specialized Toolbox for Industry-Specific Market Research
We deploy a specialized arsenal of techniques tailored to meet your unique requirements. Here's a glimpse into our comprehensive toolbox:

Information Procurement
The stage entails acquiring market data or relevant information through various sources and methodologies.


Market Research Approach
We utilize both top-down and bottom-up approaches in market research analysis to achieve a comprehensive understanding of the market dynamics, leveraging the broad perspective of industry trends and macroeconomic factors alongside detailed insights from specific segments and individual companies.

Porters Five Forces Analysis
We conduct Porter's Five Forces analysis to evaluate the competitive landscape of an industry, providing us with insights into factors that affect profitability and strategic positioning.
SWOT Analysis

Forecasting
We utilize a forecasting model to predict future consumption by considering parameters like population, economics, regulations, market competition, drivers, constraints, technology, and pricing. We also employ statistical techniques such as multilinear regression, exponential smoothing, moving average, ARIMA, and Monte Carlo simulations for accurate predictions. In econometric forecasting, we analyzed short-term and long-term event impacts, attributing values based on regulatory frameworks, economic factors, and market events.




 Speak to Our Analyst